Pepsi Cratered in 2026: Goldman Sachs Says It’s Going Up 40% Soon
PepsiCo has cratered while every major beverage rival rallied, and now Goldman Sachs sees a 40% rebound ahead. But that call rests on three pillars, and one is already showing serious cracks.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
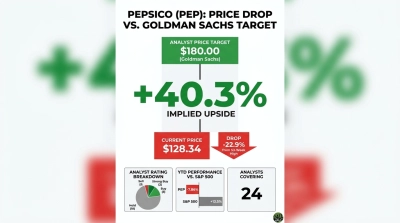
PepsiCo (NASDAQ:PEP | PEP Price Prediction) trades at $128.34, and analysts’ consensus target sits at $148.64. That works out to about 15.8% of implied upside.
PepsiCo owns Lay’s, Doritos, Gatorade, Pepsi and Mountain Dew. Goldman Sachs analyst Bonnie Herzog set a target of $180.00, meaning roughly 40.3% upside from current levels.
Frito-Lay’s Profit Slide and a Guidance Cut Sent Shares 22.9% Below Their 52-Week High
The biggest problem is North American snacks. Core operating profit at Frito-Lay North America fell 12% in the third quarter, and segment revenue stayed flat at $6.504B. The stock slipped all year. It was $155.28 around the first-quarter report, $143.30 at the second and $123.74 going into the third. It now sits 22.9% below its 52-week high of $166.41.
Management cut its 2026 outlook for core constant-currency EPS growth to +1% to +2%, down from +4% to +6%, citing rising input costs. Core operating margin contracted 35 bps. Leadership said “the consumer is worse than what we had anticipated and driven mainly by gas prices.”
The quarter itself beat expectations. EPS was $2.34 against a $2.2964 estimate, and revenue was $25.27B. Shares rose 3.73% on the report despite the guidance cut.
Goldman’s $180 Target Rests on Three Pillars, and One Is Cracking
Herzog’s first pillar is pricing power at Frito-Lay, assuming PepsiCo can pass through input cost inflation without structural volume decay. The 12% profit drop strains this assumption. Management argues value spending is working: “A category that was negative in volume now is positive in volume.”
The second pillar, international growth, is holding up. Organic growth reached +9% in both EMEA and Asia Pacific, and Latin America Foods revenue rose 14%. Management expects the international business to “cross $40 billion in this year.”
The third pillar is productivity. Per the CEO, “additional structural cost reduction actions are being identified and will be implemented in the coming months.” management expects better Q4 profit performance than Q3, making the next earnings report the first test.
Goldman is an outlier. The Street counts two Strong Buys, three Buys, 18 Holds and one Sell. The 2026 EPS consensus has had 18 downward revisions in 30 days, falling from 8.6388 to 8.5536. The fourth-quarter estimate drew 12 upward revisions in the past week.
Coca-Cola, Monster and Keurig Dr Pepper Rallied While PepsiCo Sank
PepsiCo fell on its own. Its beverage peers rallied this year.
Coca-Cola (NYSE:KO) is up 28% year to date at $87.76, with an average target of $94.43 meaning 7.6% upside.
Monster Beverage (NASDAQ:MNST) has gained 13.86% to $43.65, with a target of $50.02 meaning 14.6% upside.
Keurig Dr Pepper (NASDAQ:KDP) is up 15.13% to $31.26, with a target of $36.21 meaning 15.8% upside and no Sell ratings.
On consensus targets, Keurig Dr Pepper and PepsiCo offer similar upside. Goldman’s $180 call is the largest estimate in the group. PepsiCo’s gap exists because its price fell while peers rose.
PepsiCo Trails the S&P 500 by More Than 20 Points This Year
PepsiCo is down 7.86% year to date and 7.3% over the past month. The S&P 500 is up 13.5% year to date. Across 24 analysts, the average target of $148.64 meaning 15.8% upside from $128.34.
The valuation is modest at about 15x forward earnings. The dividend yields 4.36% after the company’s 54th consecutive annual increase, which brought the annual payout to $5.92 per share. That 54-year streak puts PepsiCo firmly in Dividend King territory, and we ranked our ten favorites in the club by valuation in a free report here.
A 4% Dividend Yield Meets a $180 Target That Needs a Frito-Lay Turnaround
The thesis improves if Frito-Lay’s volume gains turn into profit growth and the new cost cuts bring back margin expansion over the next few quarters. The downside risk grows if input inflation keeps pushing guidance lower and earnings estimates keep falling. In that case, a 15x multiple could just be the new normal.
The setup looks modestly constructive. Getting to Goldman’s $180 requires all three assumptions to hold at once, and the Frito-Lay pillar is clearly weakening. A move toward the $148.64 consensus is more realistic. The yield above 4% provides income while management works to prove the recovery.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.