Intel Is Down 20% From Its September High. Will $100 Hold?
Intel has shed a fifth of its value since September while burning through billions in its foundry division, and the round-number level traders have been watching now sits within arm's reach of the after-hours price.

Intel (NASDAQ:INTC | INTC Price Prediction) closed at $101.35 on Monday after a 3.20% session decline. It reached an intraday low of $100.71 and slipped to $100.18 after hours, just above the round number chart watchers have been tracking.
The stock now sits 20.4% below its September 24 close of $127.39, which was its highest since early August. It is also 28% below its record close of $140.94, set on June 22.
Those are large drops for a company worth $532.55 billion. Even so, Intel is still up 178.66% over the past year, so this drawdown sits inside a large rally.
The stock has fallen in six of the last seven sessions. The selling likely reflects a market repricing a story that ran ahead of the evidence before earnings.

Four Headlines Knocked Intel Off Its September Peak
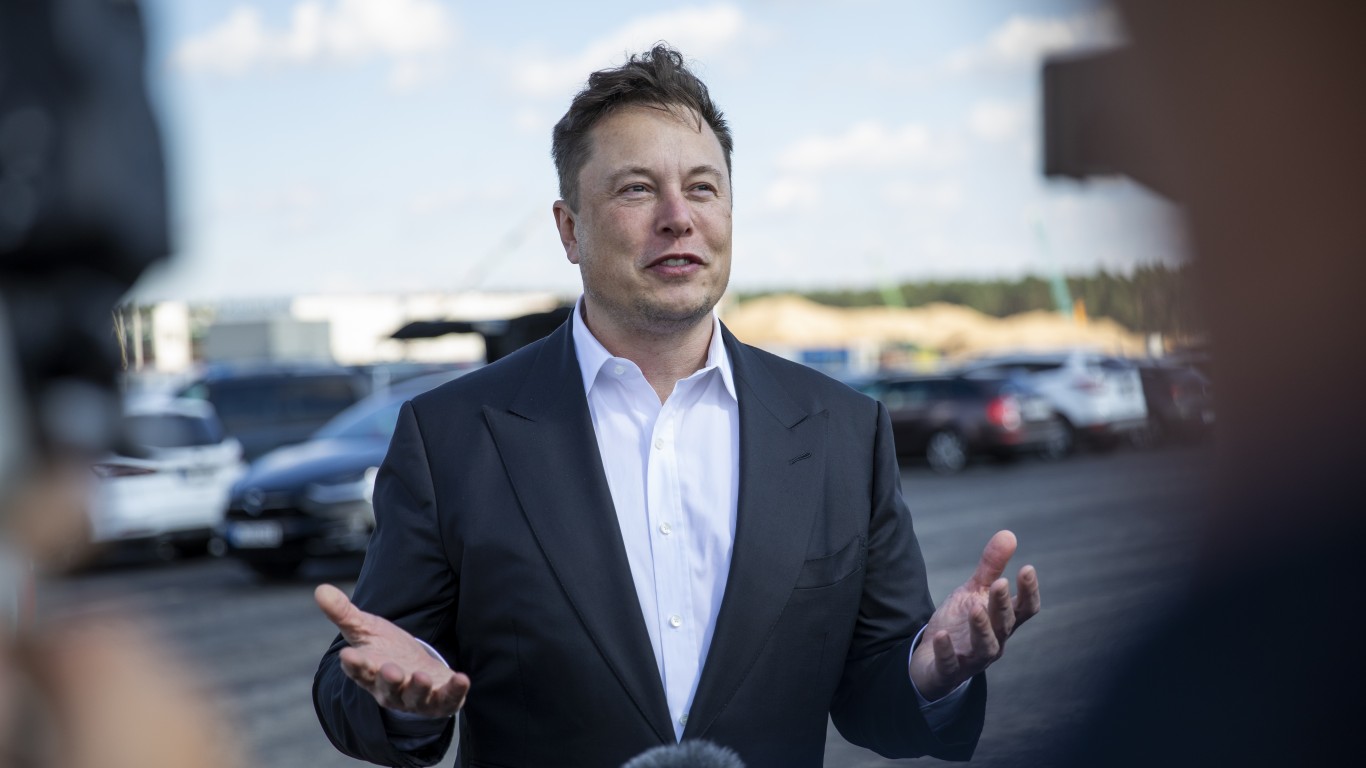
On October 4, Elon Musk confirmed talks about Taiwan Semiconductor Manufacturing (NYSE:TSM) joining his Terafab chip project, which Intel had joined in April. Musk said: “Just discussions, but something may come of it.”
Intel said it “would continue to participate in Terafab,” but the stock fell more than 4% the next session. Intel’s foundry dream depends on being the chosen alternative manufacturer, and a second alternative inside the same project reduces that role.
A sell-side estimate then showed Intel’s share of CPU models slipping 3.9 points in the third quarter to 68.1%. Because supply already caps how many chips Intel can ship, that loss matters more for the story than for revenue.
On October 8, chip stocks generally sold off after a report put OpenAI’s annualized revenue at about $50 billion, below earlier estimates. Intel lost 5.34% that day in a sector-wide move, part of a 12.3% decline over the five sessions ending October 9.
A Capital Warning Lands on the Hungriest Balance Sheet
On Monday, Intel’s chief executive and Broadcom’s (NASDAQ:AVGO) chief executive spoke at an event in Singapore. They warned that a lack of capital could become the AI industry’s biggest bottleneck.
That warning hits Intel directly. It raised its 2026 capital spending outlook to “more than $20 billion” and expects 2027 spending to be “significantly above the 2026 levels.”
Intel Foundry still lost $2.1 billion in the second quarter. Management has said Intel “may need to tap the capital markets” if it is very successful, and a tighter funding cycle raises the cost of that plan.
The operating business held up through the slide. Second-quarter revenue rose 25.42% to $16.13 billion, and Data Center and AI revenue grew 59%.

Chart Watchers Have Drawn Their Line Between $100 and $103
Technical analysts point to a support zone from $100 to $103. It includes the 50-day moving average of $103.30 with a Fibonacci retracement level of $100.54. A support zone is a price range where buyers have previously stepped in strongly enough to stop a decline.
Below that, the next support zone is $87 to $88, with the 200-day moving average near $83 as deeper support. This view comes from chart analysts and is separate from sell-side fundamental research. It describes past trading behavior.
Wall Street’s Hold-Heavy Consensus Wants Proof
Coverage stands at 20 Buy, 27 Hold and 2 Sell ratings. Analysts’ mean price target of $109.06 implies about 7.6% upside.
That is thin next to a 178.66% one-year gain. With holds in the majority, analysts are waiting for evidence before calling the stock cheap.
The average target has trailed the stock’s moves. At its September peak, Intel traded well above today’s average target.
Intel reports third-quarter results after the close on Thursday, October 29. It guided to revenue of $15.8 billion to $16.8 billion and adjusted EPS of about $0.38, and a chart level may give way once those numbers come out.

Valuation Gap Leaves Intel Trailing NVIDIA on Analyst Upside
Intel looks fully valued at current levels. The upside to the average target is small, and the stock trades at 63x forward earnings while its foundry lost $2.1 billion in the second quarter.
There’s substance to the optimism, because server demand is exceeding supply and Intel has beaten its own forecasts for seven consecutive quarters. But the past year’s gain already prices in much of that progress.
NVIDIA (NASDAQ:NVDA) carries a stronger valuation profile. At $226.32 against an average target of $328.72, it carries about 45.2% implied upside at 25x forward earnings, with 49 Buy ratings.
Analyst targets remain estimates for both stocks, and the key distinction is that NVIDIA’s earnings already support its valuation, while Intel’s earnings still have to catch up.
My view fails if Intel tops $16.8 billion in revenue on October 29 and closes back above $103.30. A close below $100 before then would point toward the $87 area instead.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.