Two Reasons Keep Me Buying Amazon Without Fear
AWS is accelerating while spending $200 billion, and the math behind it either makes this the most confident buy of the decade or a very expensive lesson in timing.

I keep adding to my Amazon (NASDAQ:AMZN | AMZN Price Prediction) position, and every earnings report gives me another reason to buy more. My retirement account already holds plenty of income stocks. Amazon is the compounder I keep feeding because it owns two cash generators that keep getting stronger at once. Those two generators are why I buy without fear.
Reason One: AWS Keeps Accelerating From a Giant Base
Cloud businesses this large usually slow down. AWS keeps speeding up. Growth rose from 20% in Q3 2025, to 24% in Q4 2025, to 28% in Q1 2026, and 37% in Q2 2026. Last quarter AWS revenue reached $42.23 billion at a 39.4% operating margin. CEO Andy Jassy said on the July call that “AWS is booming, growing 36.7% year-over-year in Q2”.
The visibility gives me conviction. AWS carries a $496 billion backlog that is growing triple digits year over year. Its AI and chips businesses each passed $25 billion annualized run rates with triple-digit growth. Management said the “lion’s share of capacity in 26” is largely reserved. Jassy now believes AWS could “very possibly be a trillion dollar annual revenue business for us in time”.
Reason Two: Ads, Retail and a Fortress Balance Sheet Compound Together
Amazon’s second generators gets less attention than it deserves. Advertising grew 26% to $19.81 billion last quarter, and worldwide paid units rose 17%. Total revenue grew 19.6% to $200.61 billion, while operating income rose 43.24% to $27.46 billion. When operating income outpaces revenue, I know the higher-margin businesses are taking a larger share of the mix.
The balance sheet lets me sleep. Debt-to-equity sits at 0.37, interest coverage at 35.17x, and cash at $78.21 billion. I pay roughly 36 times earnings, and the stock has returned 530.72% over ten years.
Why My Money Skips Microsoft and Walmart
The obvious cloud alternative is Microsoft (NASDAQ:MSFT), and Azure is excellent. I still prefer Amazon. Microsoft’s book value multiple is 9.08, compared with Amazon’s 6.81, and its More Personal Computing segment declined 4% in fiscal Q4. Amazon gives me cloud plus a growing ad and retail momentum.
Walmart (NASDAQ:WMT) lures retirees, but its dividend yields under 1% and its P/E of 41 runs higher than Amazon’s. Walmart’s operating margin sits near 4% against Amazon’s 11.16%. I would rather own the higher-margin business at the lower multiple.
Real Risk: A $200 Billion Spending Year
Amazon plans about $200 billion of capex in 2026. Q2 capex alone reached $54.21 billion, and trailing free cash flow turned negative at -$7.6 billion. Headline EPS also flatters the picture: Q2’s $5.75 includes a $53.4 billion pre-tax Anthropic gain, with comparable EPS near $1.88. If AI demand cools before these data centers fill, returns will suffer.
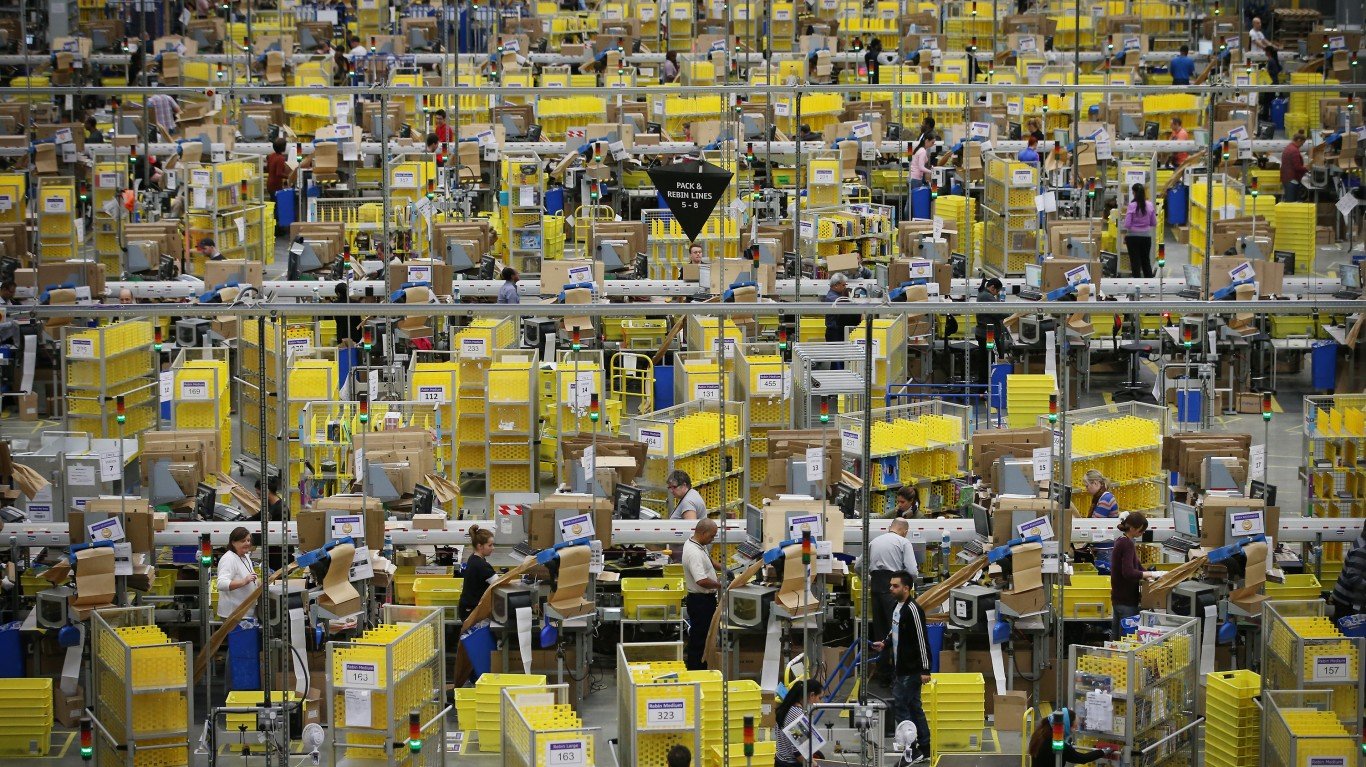
My thesis holds up because of how this spending pays back. Management said data centers can be monetized for 30-plus years, servers break even in a little less than three years, and most AI capacity is contracted for at least five-year terms. Customers sign up before the concrete dries.
The capex is enormous, but it is going into the picks-and-shovels of the AI expansion, the power, cooling, and networking layer that gets less attention than the chipmakers (we covered seven of those suppliers in a free report here: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers)).
What Keeps My Buy Button Active
Q3 guidance calls for operating income of $22.5 billion to $26.5 billion, up from $17.4 billion a year earlier. Management says 85% of global IT spend is still on-premises, so the migration has decades left to run. Amazon is spending today to own the infrastructure the next 30 years will run on, and I want a bigger piece of it every quarter.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.