Forget the Semiconductor Index: What Wall Street Says to Watch Instead
Chip stocks are sliding hard, but Jim Cramer says investors are watching the wrong signal entirely. The real tell has nothing to do with the semiconductor index, and the data buried in Micron's latest filing may prove he's right.

Chip stocks opened Wednesday under pressure. Micron Technology (NASDAQ:MU | MU Price Prediction) traded at $940.76 in the premarket. That was down 1.3% on the session and 10.0% over the past week. Nvidia (NASDAQ:NVDA) traded at $228.00 premarket, down 0.2% and still off 4.5% for the week. On Mad Money on October 13, Jim Cramer said, “The semiconductor index has now fallen 7.22% in these last six days. That’s the longest losing streak since May of last year.”
That evening, two different CNBC programs looked at the selloff and reached the same conclusion: it shows nervousness, and the demand data still points up.
Cramer Says to Watch the Showroom Instead of the Index
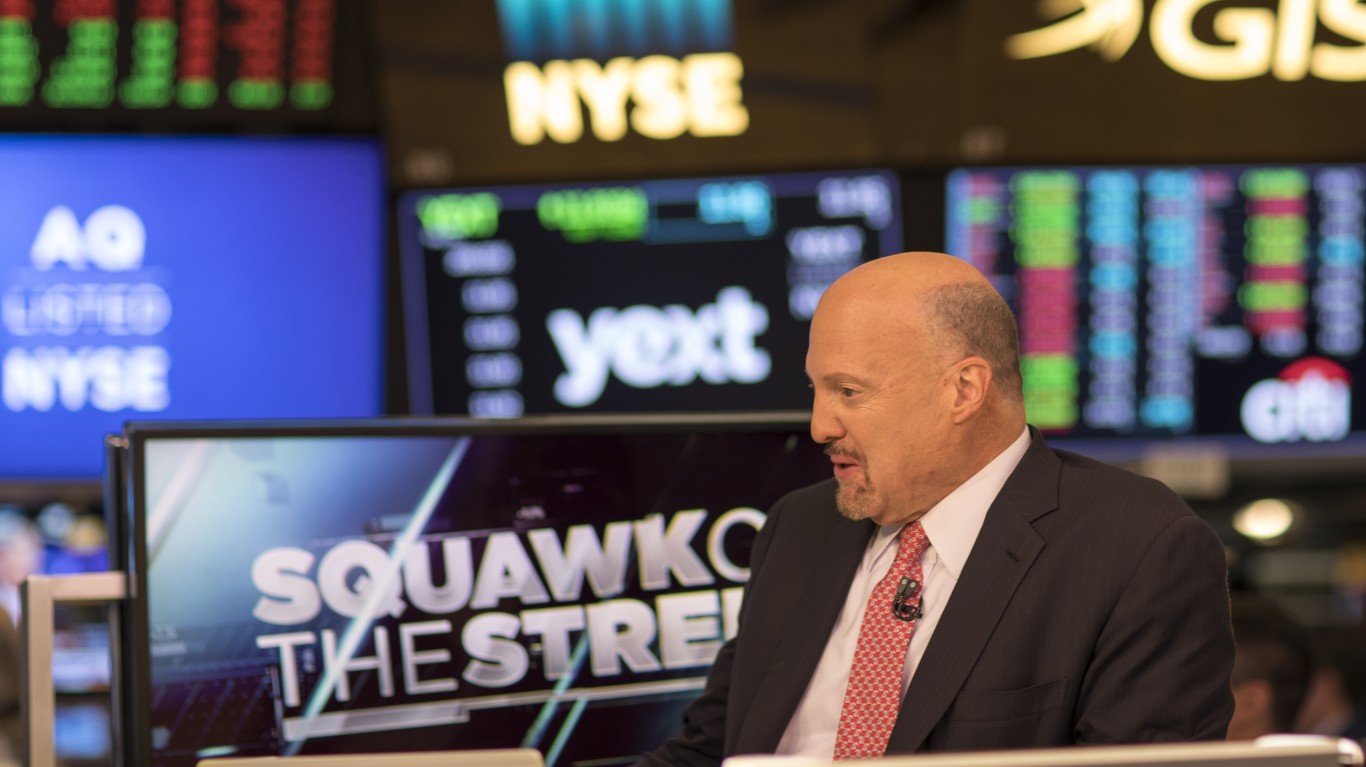
Cramer opened by explaining why U.S. names are trading on what happens overseas: “SK Hynix is so big that it’s become the key to the semiconductor solar system. Not Nvidia. SK Hynix.” When Korean memory giant SK Hynix (NASDAQ:SKHY) slips, Micron gets pulled down with it.
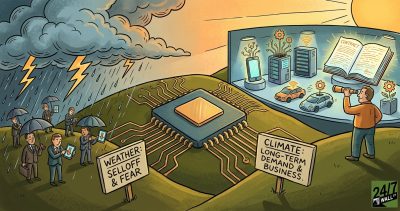
Cramer then addressed the China DRAM fear, which grew after Elon Musk flagged a China chip threat on Tuesday: “If the Chinese competition were so serious, why would anyone take these long-term leases? Are they idiots?” He also told investors what to watch: “Before you decide to bail from the semis because you can’t take the pain, see the showroom. Go see where these chips are really used. Don’t watch the semiconductor index, watch the devices, watch the business.”
Micron’s Contracts Back Up the Argument
Micron’s fiscal fourth-quarter results illustrate what that business looks like. Revenue came in at $54.23 billion, ahead of the $50.97 billion consensus. Non-GAAP EPS of $33.42 beat the $31.35 estimate, according to its earnings release filed with the SEC. Non-GAAP gross margin reached 87.0%, compared with 45.7% a year earlier.

The long-term leases Cramer mentioned show up in the filing. Micron has signed 26 take-or-pay strategic customer agreements, which it estimates cover “over 35% of our revenue through 2030.” Customers have committed $32 billion, most of it as cash deposits. Remaining performance obligations total about $150 billion. CEO Sanjay Mehrotra said that “more than 75% of our output is already committed for 2027.”

Nvidia’s numbers show the same thing from the buyer’s side. It reported extreme pricing conditions in memory, and its supply obligations rose to $279.0 billion, mostly tied to memory for Vera Rubin production.
Fast Money Reached the Same Conclusion
On October 13, CNBC’s Fast Money described the selloff this way: “Investors should recognize the difference between weather and climate. The weather piece here is this nervousness. There is no magic bullet. No magic bullet around memory, no magic bullet around frontier models. Just knowing that piece should be somewhat reassuring.”
Also on Fast Money, Gene Munster of Deepwater Asset Management said, “In five years there’s going to be dramatically more agents. Agents run on tokens. Tokens are inference. Inference is memory. So the best memory to buy in my mind is Micron.”
What Would Prove the Bulls Wrong
Micron’s drop needs to be considered against how far it ran. The stock is still up 234.0% year to date, even after the past week’s decline. Shares were at $1,071.88 when results came out and were trading below $960 apiece at last look.
Management has also flagged its own risks. Some server platforms may see a “modestly lower rate of content growth than prior expectations,” and the company expects a “more moderate rate of price increases” after fiscal Q1. The biggest risk is China. If Chinese DRAM makers start winning long-term supply agreements away from the current suppliers, Cramer’s argument falls apart.
Our Take and the Signal to Check
The evidence backs Cramer’s advice. Take-or-pay volumes, cash deposits, and buyers’ memory commitments all point to sustained demand even as the index falls. The next check is Micron’s fiscal first-quarter report, forecast at $60.0 billion to $63.0 billion in revenue. A drop in the agreement count, the $32 billion in commitments, or the 75% of 2027 output already committed would show the case cracking. Until that happens, the weather is choppy and the climate is holding.


Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.