Credo Stock Has a Powerful Growth Story, but Is It Already Priced In?
Credo just posted triple-digit revenue growth and its eighth straight earnings beat, yet the stock lost a third of its value in a month. Two big customers and one valuation gap might explain why the market and our model disagree.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

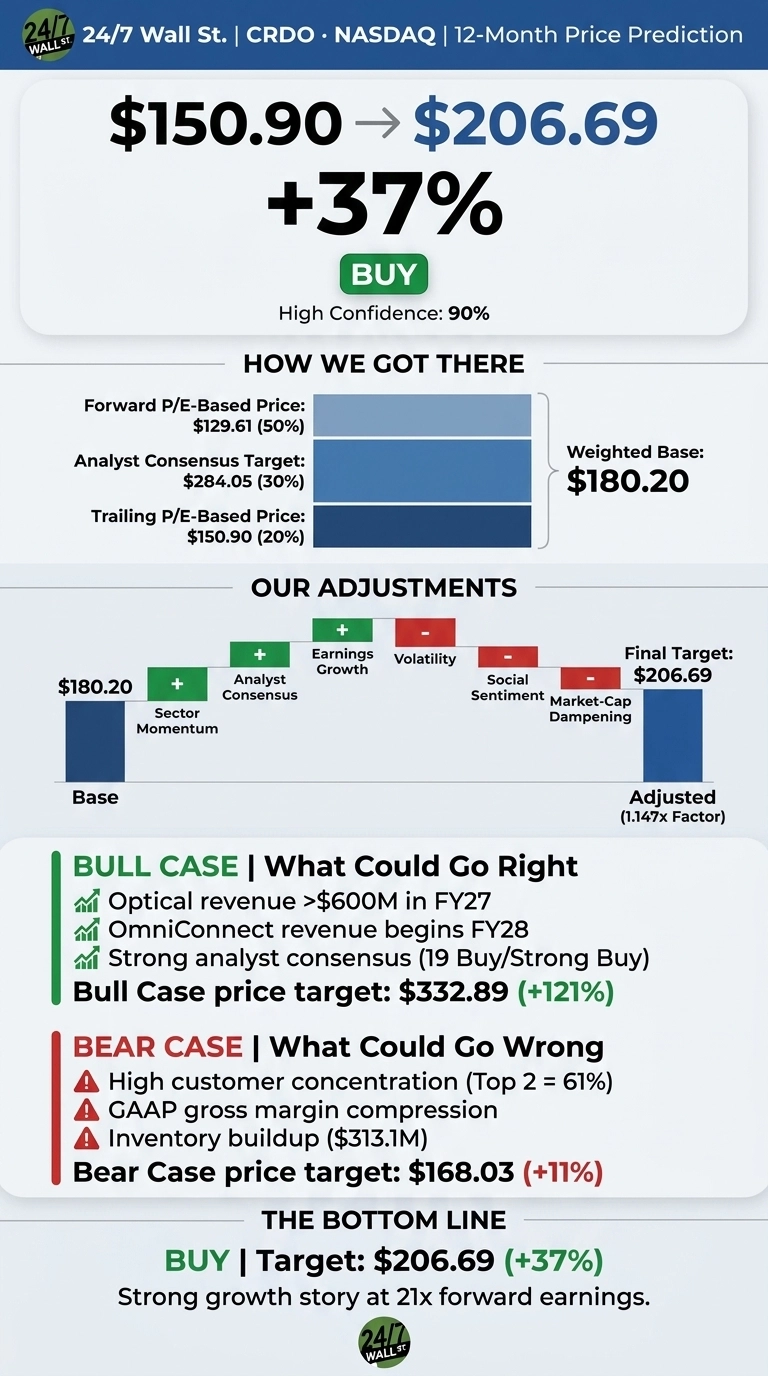
The 24/7 Wall St. price target for Credo (NASDAQ:CRDO | CRDO Price Prediction) is $206.69. The target implies 36.97% upside from the $150.90 close on November 3, 2026, and our model carries high conviction.
| Metric | Value |
|---|---|
| Current Price | $150.90 |
| Price Target from 24/7 Wall St. | $206.69 |
| Upside/Downside | 36.97% |
| Recommendation | BUY |
| Confidence Level | 90% |

Credo shares are down sharply even as the business continues accelerating. Management expects fiscal 2027 revenue growth above 85%. The recent selloff has already taken a lot of the excitement out of the stock price. Shares were showed at $145.80 ahead of the November 4 open.

A 33% One-Month Slide Resets Expectations
Credo fell 12.92% over the past week and 33.32% over the past month. That leaves it up just 1.33% year to date. At $150.90, the stock trades 51% below its 52-week peak of $308.67 and 74% above its trough of $86.48. The drop came after a strong quarter.
Q1 fiscal 2027 revenue of $479.0M rose 114.7% and beat the $470.4M consensus. Non-GAAP EPS of $1.20 exceeded the $1.17 estimate, making it Credo’s 8th consecutive beat. Q2 guidance calls for revenue of $525M-$535M.
Optics Could Drive Credo Toward $332
The bull case reaches $332.89, a 120.61% gain. Management expects optical revenue above $600 million in fiscal 2027. ZeroFlap optics, silicon photonics PICs and optical DSPs should each contribute more than $100 million.
OmniConnect, which begins generating revenue in fiscal 2028, could add “thousands of dollars of Credo content per GPU.” Wall Street is overwhelmingly bullish. Analysts list 5 Strong Buys, 14 Buys, one Hold and no Sells. Their consensus target of $284.05 implies 88% upside.

Customer Concentration Is the Risk to Watch
Credo’s largest customer accounted for 33% of revenue last quarter, and the next largest accounted for 28%. GAAP gross margin slipped to 64.5% from 68.2%. Most of that decline reflects amortization from the Dust Photonics acquisition, which raised goodwill to $986.45M. On a non-GAAP basis, gross margin held at 68%.
Stock-based compensation reached $87.98M, and inventory rose to $313.1 million. Management says the inventory build is intentional supply preparation. Our bear case of $168.03 still sits above today’s price. However, last month’s slide shows that a stock with this much volatility can fall further than any model expects.
How Credo Compares to Broadcom, Marvell and Astera Labs
The scale benchmark for AI networking is Broadcom (NASDAQ:AVGO). Its AI semiconductor revenue reached $16.70 billion, up 221%. Credo has narrower exposure but grows faster in total (we covered seven of these AI infrastructure suppliers, from power to networking, in a free report you can grab here).
Marvell Technology (NASDAQ:MRVL) competes directly in optical DSPs. Its revenue grew 36.55% with a non-GAAP gross margin of 58.9%, below Credo’s 68%.
Astera Labs (NASDAQ:ALAB) is the closest pure-play comparison. The multiple sits at 185x earnings, while Credo trades at 21x forward earnings. Against this group, our target looks conservative.
| Company | Latest Quarter Revenue Growth | Latest Non-GAAP EPS |
|---|---|---|
| Credo | 114.7% | $1.20 |
| Broadcom | 85.5% | $3.32 |
| Marvell | 36.55% | $0.94 |
| Astera Labs | 153.67% | $1.32 |
Triple-Digit Growth at 21x Forward Earnings Tips the Scale
Our 24/7 Wall St. price target remains $206.69, with a buy rating and 90% confidence. The deciding factor for me is the valuation: a business growing triple digits now trades at 21x forward earnings.
The bull case strengthens if the optical ramps meet the $600 million target. The thesis weakens if the largest customers start cutting orders. At today’s price, I think the growth story has been marked down too far.
Our model projects the following path over a longer horizon, given current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $206.69 |
| 2027 | $216.19 |
| 2028 | $266.82 |
| 2029 | $311.81 |
| 2030 | $348.03 |
The projections rest on Credo continuing to carry out its optical and copper strategy. A shift in hyperscaler AI spending could drive results well above or below this path.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.