Wall Street Is Getting More Interested in Credo. Here’s My Price Prediction
Credo just posted triple-digit revenue growth and still trades at a steeper discount than its closest rivals, yet the stock has fallen nearly 20% in a single month. Something in this picture does not add up, and the answer points…

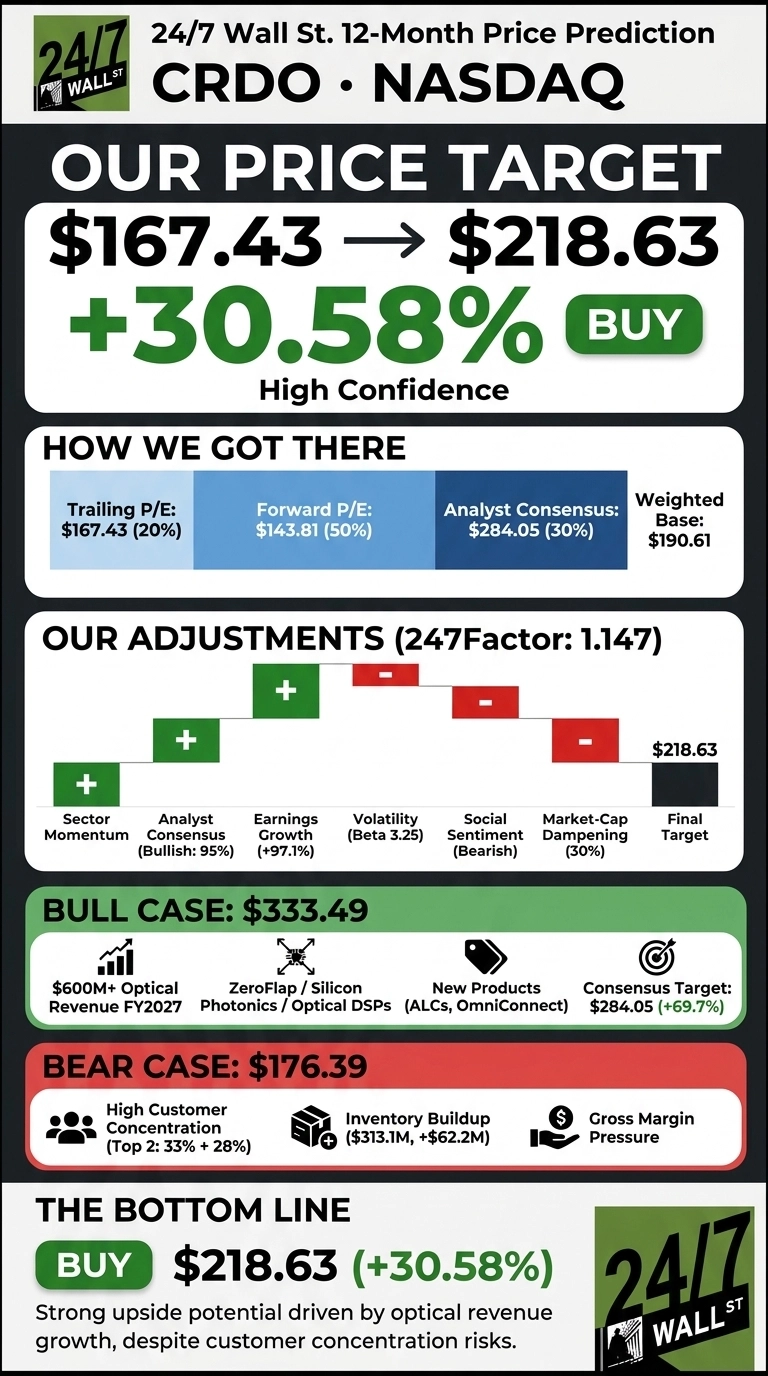
Wall Street is warming to Credo (NASDAQ:CRDO | CRDO Price Prediction) even as the stock has pulled back. The 24/7 Wall St. price target for Credo is $218.63, which implies 30.58% upside from the $167.43 close.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $167.43 |
| 24/7 Wall St. Price Target | $218.63 |
| Upside/Downside | 30.58% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our model rates Credo a buy, and we hold that view with high conviction. Analysts agree: 19 of 20 rate the stock a buy or strong buy.
Big funds have been adding too. In the June quarter, seven of 15 tracked filers bought shares and two opened new positions. Millennium Management, Renaissance Technologies and Balyasny each more than doubled their stakes.
A Record Quarter Met a 20% Monthly Slide
Shares fell 19.83% over the past month and 1.38% over the past week. They are still up 17.55% year to date. Credo trades 45.8% below its 52-week peak of $308.67 and 93.6% above its low of $86.48.
The business continues getting stronger. Fiscal Q1 2027 revenue grew 114.7% to $479 million, ahead of the $470.38 million estimate. Non-GAAP EPS of $1.20 beat the $1.17 consensus, the eighth consecutive EPS beat. Management guided Q2 revenue to $525 million to $535 million and expects more than 85% revenue growth for the full year.

Optics Could Send Credo Toward $333
In our bull case, Credo hits $333.49. Optics is the main driver. Management expects more than $600 million of optical revenue this fiscal year, with ZeroFlap optics, silicon photonics PICs and optical DSPs each exceeding $100 million.
Active LED Cables and OmniConnect are due to start generating revenue in fiscal 2028. OmniConnect alone could add “thousands of dollars of Credo content per GPU.” The consensus target of $284.05 implies 69.7% upside.

Customer Concentration Tops the Risk List
Credo’s largest customer accounted for 33% of Q1 revenue, and its second-largest added 28%. GAAP gross margin slipped to 64.5% from 68.2%. Most of that drop reflects amortization from an acquisition, and non-GAAP gross margin held at 68%.
Inventory rose $62.2 million, which management linked to stocking up for a second-half increase. Even our bear case of $176.39 remains above the current price.

Credo Trades Cheaper Than Its Closest Rivals
Astera Labs (NASDAQ:ALAB) competes with Credo head-on in retimers and AI rack connectivity. Its revenue grew 104.45%, close to Credo’s rate, yet it trades at 40 times forward earnings.
Marvell Technology (NASDAQ:MRVL) goes up against Credo in optical DSPs. It grew 36.55% and trades at 31 times forward earnings.
| Company | Forward P/E | Latest Revenue Growth |
|---|---|---|
| Credo | 23x | 114.7% |
| Astera Labs | 40x | 104.45% |
| Marvell | 31x | 36.55% |
Credo is growing the fastest of the three and trades at the lowest multiple. Next to these peers, our 24/7 Wall St. price target looks conservative.
This Pullback Makes the Math Work
The 24/7 Wall St. price target of $218.63 comes with a buy rating and 90% confidence. Valuation is what convinces me: Credo has triple-digit growth and still trades at a discount to its peers. That case gets stronger if optics delivers the $600 million management expects.
It gets weaker if a top hyperscaler cuts spending, which is why we continues an eye on the broader connectivity and infrastructure suppliers riding the same expansion (we rounded up seven of them, from power to networking, in a free AI infrastructure report).
Credo Price Prediction 2026-2030
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $186.02 |
| 2027 | $206.56 |
| 2028 | $255.01 |
| 2029 | $281.24 |
| 2030 | $331.64 |
Credo would need to keep executing on its current strategy for these projections to hold. A faster 1.6T increase could drive the stock far past them, and a pause in AI spending could pull it far below.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.