Suze Orman Says That Without This 1 Document, Your Spouse Could Lose Access to All Your Accounts
Most married couples assume decades of shared finances means shared legal access, but a single health crisis can expose a gap that freezes retirement accounts, stalls bill payments, and forces families into costly court battles before anyone can touch a…

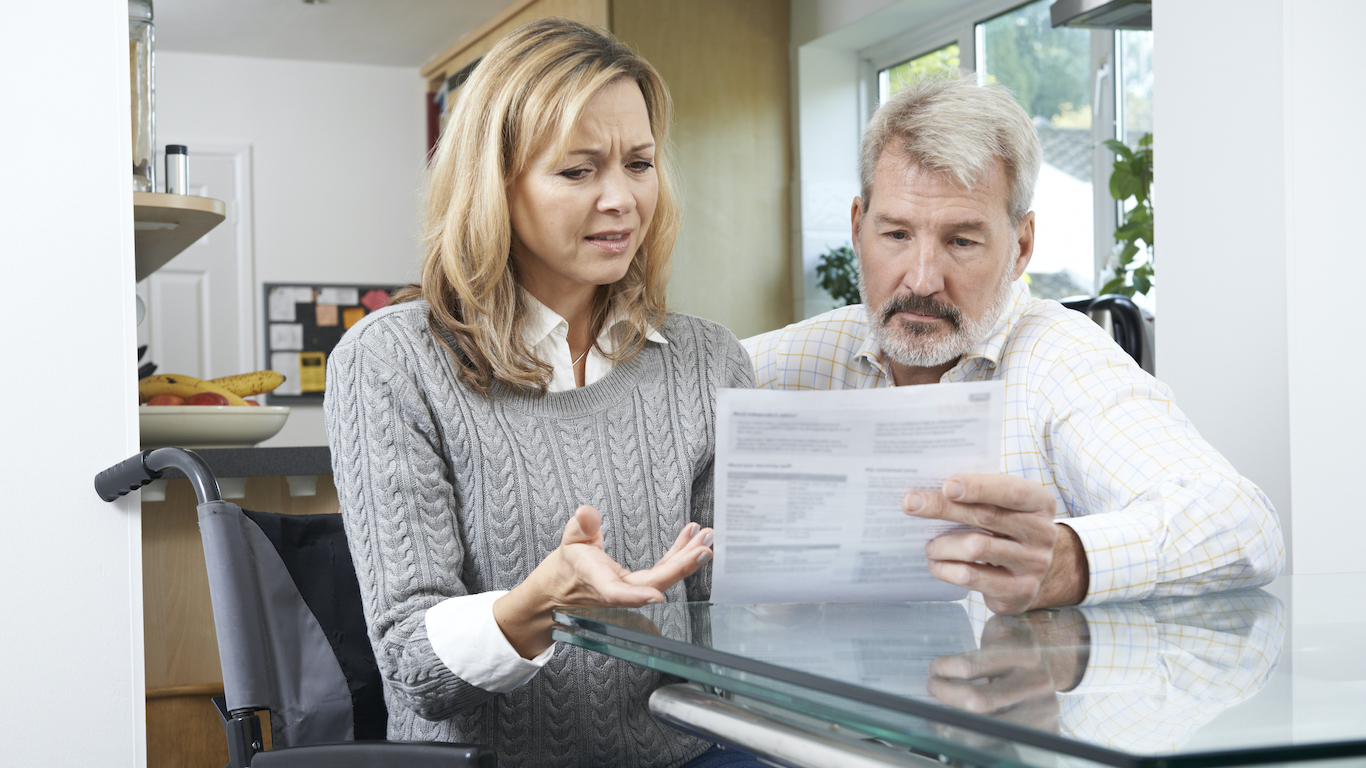
Financial advisor Suze Orman has highlighted a critical gap in estate planning that catches most married couples off guard. Despite decades of marriage, a healthy spouse has no legal authority to manage an incapacitated partner’s IRA or pension without a Durable Financial Power of Attorney (POA). This creates a financial paralysis at the worst possible moment: when one spouse suffers a stroke or develops dementia and can no longer authorize transactions, yet the other cannot legally step in to pay bills or manage investments.
What the Advice Gets Right
Orman’s warning is accurate and often overlooked. The legal reality surprises most couples: Federal law prohibits joint ownership of IRAs, and individual investment accounts remain in one person’s name regardless of marital status. When incapacity strikes through stroke or dementia, the account holder can no longer authorize transactions, yet the spouse has no legal standing to step in—creating a financial deadlock that affects everything from paying medical bills to managing investments.
The alternative to proper planning is court-ordered conservatorship, a costly legal process that can stretch for months while families hemorrhage money on attorney fees. During this limbo period, financial life grinds to a halt. Retirement portfolios sit untouched during market swings, and everyday bills pile up unpaid. The Durable Financial POA eliminates this entire ordeal by granting immediate authority when crisis strikes.
Where the Advice Needs Context
Not all Powers of Attorney are created equal. A standard POA becomes invalid the moment the person granting it loses mental capacity. Only a Durable POA remains in effect after incapacity, which is precisely when it’s needed most. Many people unknowingly hold outdated or non-durable POAs that provide no protection during a crisis.
Additionally, the POA must be accepted by financial institutions. Some banks and brokerages require their own forms or refuse POAs older than a certain number of years. Couples should confirm their POA meets institutional requirements and update it periodically.
How Retirees Should Think About This
Establishing a Durable Financial Power of Attorney is inexpensive compared to the alternative. Many estate planning attorneys include it as part of a basic package costing a few hundred dollars. Some states offer statutory forms that can be completed without an attorney, though legal review is advisable.
Before acting, ask: Does my spouse have legal access to my IRA, pension or individual accounts if I’m suddenly incapacitated? If the answer is unclear, this document deserves immediate attention. Even strong marriages benefit from clear legal authority when health crises strike without warning.
Contact [email protected] for any questions or corrections.
Joel South covers large-cap stocks, dividend investing, and major market trends, with a focus on earnings analysis, valuation, and turning complex data into actionable insights for investors.
He brings more than 15 years of experience as an investor and financial journalist, including 12 years at The Motley Fool, where he served as an investment analyst, Bureau Chief, and later led the Fool.com investing news desk. He has also co-hosted an investing podcast and appeared across TV and radio discussing market trends.