Who’s Really Paying for the AI Boom? The Bond Market Is Starting to Ask
Bond investors are quietly repricing the debt that funds AI's massive buildout, and some of the numbers coming out of quarterly filings suggest the easy money phase may already be over.

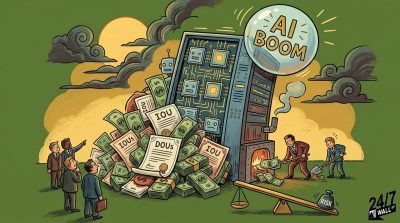
Borrowed money is paying for a growing share of the AI expansion, and credit investors have started to reprice the risk. On the Charles Schwab On Investing episode “Who’s Financing the AI Boom?,” Bryan Whalen described how large the shift has become.
“Last year in 2025, net issuance in the investment grade corporate bond market was about half a trillion dollars. This year it’s expected to double. And almost the entirety of that doubling has been in the AI data center required capital spend,” Whalen said. The portfolio manager also said that the cash buffer is gone: “Three years ago, these hyperscalers had over $250 billion of free cash flow collectively. This year they’re negative.”
Cash Flow Gaps Now Show Up in the Filings
Company results support his point. Meta Platforms (NASDAQ:META | META Price Prediction) generated $784 million of second-quarter free cash flow, down from $8.55 billion a year earlier. Over the same quarter, capex reached $30.12 billion and long-term debt rose to $83.66 billion. Amazon (NASDAQ:AMZN) reported trailing free cash flow of negative $7.6 billion. Oracle (NYSE:ORCL) posted free cash flow of negative $5.4 billion on $28.5 billion of capex and completed a $20 billion at-the-market equity program.
Whalen argued that the biggest spenders care less about the price of borrowing. He said Mark Zuckerberg “does not seem concerned whether he borrows at 6%, 7%, or 8%. It’s not the cost of capital. It’s just getting the capital.”
Nvidia’s Customer Financing Draws Bubble Comparisons
Whalen also turned to chip supplier Nvidia (NASDAQ:NVDA). He said, “Nvidia is financing over 200 different companies that effectively buy their products. That might remind some of us of the technology bubble in the late 90s going into 2000 and 2001.” Nvidia has partnered with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs, and KKR to mobilize over $500 billion in third-party capital, and its supply obligations reached $279 billion. The company responded to the criticism on its August earnings call: “We recognize the scale of this support, and we know some will call this circular financing. We see it differently.”
CoreWeave Has Become the Market’s Stress Case
Bloomberg Businessweek reported that CoreWeave (NASDAQ:CRWV) carries $52 billion of debt and that interest owed in its latest quarter topped its operating income. The report also cited expectations that the company will need another $20 billion to $40 billion of financing over the next two years. And it said CoreWeave’s 2032 notes were trading 80 cents or below on the dollar with yields at 15%.
CoreWeave’s second-quarter release shows interest expense of $640 million, up from $267 million a year earlier. The company posted an operating loss of $49 million, even with a backlog of about $104 billion. Management guided third-quarter interest expense to $860 million to $940 million. The stock fell 15.9% over the past week.

Supply Contracts and Concentration Add Another Layer of Risk
A discussion on Fast Money questioned how firm long-term chip supply agreements are. It remembered that during COVID, “people wanted to get out of those long term agreements” and added that “those long term agreements are not very solid.” On Mad Money, Jim Cramer tied the giant sell-off in semiconductor stocks to concentration and a lack of diversification.
What Retirement Investors Should Track Next
Three markers matter most:
- How much new financing the most leveraged names need, starting with whether CoreWeave’s third-quarter interest bill lands inside its guidance.
- How bond investors price that debt. The 10-year Treasury yield was at 5.1% on October 15, and that rate is the benchmark new corporate debt prices against.
- How concentrated your own portfolio is, since broad index funds often hold the same AI-linked stocks.
Whalen said he remains cautious on corporate bonds until a better entry point emerges.
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.