Applied Materials Cratered 20% Since July: Multiple Wall Street Firms Predict It’s Going to More Than Double From Here
Applied Materials just suffered one of its steepest drops in years, yet analysts keep raising their earnings estimates and some price targets sit nearly double the current share price. Here is what the disconnect reveals about where semiconductor equipment spending…

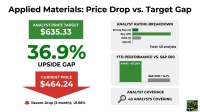
Applied Materials (NASDAQ:AMAT | AMAT Price Prediction) is now priced at $409.29. The average analyst price target stands at $627.83, meaning 53.4% upside.
Applied makes the deposition, etch and inspection tools used to build virtually every new chip. AI infrastructure demand drove fiscal third-quarter revenue to $9.12 billion, up 24.8% year over year. Management guided the current quarter to about $10.25 billion.
The most bullish firms, including H.C. Wainwright and Susquehanna, have $900 targets. Those sit about 119.9% above the current price. Consensus upside stands above 40%.
Investor Day Silence Turned a Pullback Into a 37% Rout
The biggest hit came at Applied’s investor day, when the company declined to provide an industry spending forecast. Shares fell as much as 9% intraday, and the stock lost 19.28% over the past week. Since the start of July, Applied has dropped 37.05%. That leaves it 44.6% below its 52-week high of $738.88.
The first signs showed after the August earnings report. Shares fell about 4% even though guidance beat consensus. Morgan Stanley summed it up: “AMAT’s earnings were good, but not great.” Peers fell about 4% on investor day, so sector weakness made a company-specific hit worse.
33 of 40 Analysts Rate It a Buy as Estimates Climb
Of the 40 analysts who cover Applied, 4 rate it Strong Buy, 29 rate it Buy and 7 rate it Hold. None rate it Sell. Estimates rose while the stock fell. The fiscal 2027 EPS consensus is $18.4672, up from $16.7456 90 days ago. Over the past 30 days, analysts made three upward revisions and no cuts. The stock trades at about 22 times that figure.
Management guided fourth-quarter EPS to about $4.02. DRAM revenue, including HBM packaging, grew 52% year over year. Packaging revenue should grow more than 70% in calendar 2026. Leading-edge logic, DRAM and advanced packaging should account for about 80% of equipment growth.
The $900 camp argues that Applied is well placed in tools for Gate-All-Around transistors, backside power and HBM packaging. CEO Gary Dickerson set the timeline on the earnings call: “Based on the unprecedented visibility we’re receiving from our customers, we expect another strong record year in 2027.”
Lam, KLA and Teradyne Sold Off Too, but Applied Fell Hardest
The whole group fell over the past week, but Applied fell the most.
Lam Research (NASDAQ:LRCX) lost 14.74% to $263.94. Its average target is $375.81, meaning 42.4% upside. Twenty-nine of 35 analysts rate it Buy or Strong Buy.
KLA (NASDAQ:KLAC) dropped 12.82% to $165.74. Its target of $232.77 meaning 40.4% upside. Analysts are more cautious here, with 10 of 29 at Hold.
Teradyne (NASDAQ:TER) slid 15.33% to $325. Its target of $446.47 meaning 37.4% upside, and 12 of 17 analysts are bullish.
Applied has the largest consensus upside in the group. All of these targets are estimates, and they could fall if spending expectations drop.
A 59.83% Gain This Year Survives the Drawdown
Applied trades at $409.29. The average target from 40 analysts is $627.83, meaning 53.4% upside. Targets often lag sharp price moves, so treat that number as one input among several.
Even after the drop, the stock is up 59.83% year to date. The S&P 500 is up 11.93%. Over one year, Applied shares are up 80.75%.
Applied Materials Looks Like an Overcorrection Worth Researching
Applied Materials’ upside case strengthens if DRAM and leading-edge logic deliver the second-half surge management promised and fiscal 2027 earnings land near the $18.4672 consensus. At a forward P/E of about 23, that growth looks undervalued.
The upside story weakens if the investor day silence means equipment spending is peaking. Management claims multi-year visibility yet held back an industry forecast. China fell to 28% of revenue from 35%, and the Other segment’s loss widened to $118 million. A slowdown in AI capex would pull targets down toward the share price.
The data leans positive. Estimates are rising while the share price falls. Applied’s upside is also the largest of any peer. The next earnings report and its 2027 outlook will test that view. (We reverse-engineered what the biggest semiconductor winners looked like early on in a free guide you can download here.)
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.