Johnson & Johnson Stock Could Be a Defensive Play for the Years Ahead
Johnson & Johnson just posted a quarter that sent shares sliding despite a headline beat, yet analysts keep piling into the bull camp with price targets well above current levels. Here is what the numbers actually say about whether this…

Our 24/7 Wall St. price target for Johnson & Johnson (NYSE:JNJ | JNJ Price Prediction) is $291.60 over the next 12 months. That means 15.57% upside from the model’s reference price of $252.32. Our rating is a buy, and our confidence is high.
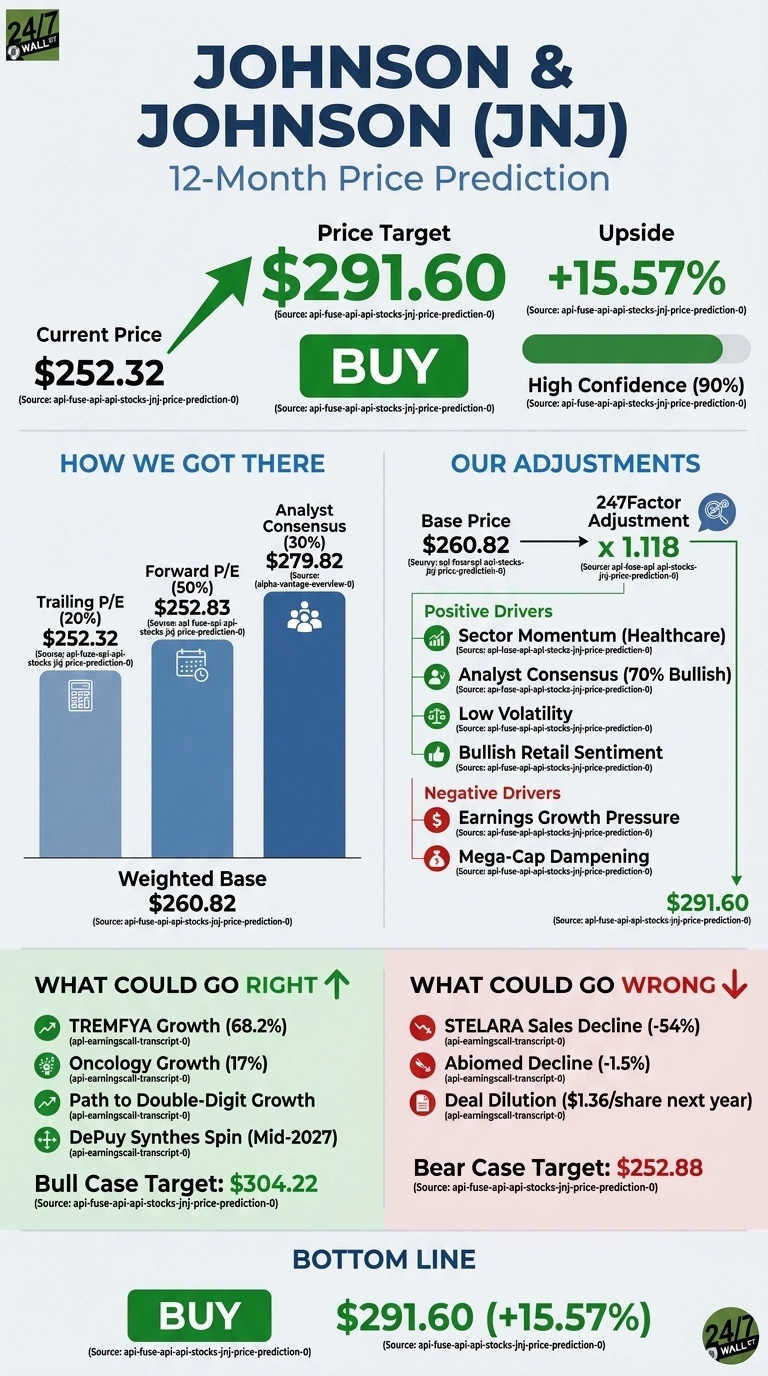
| Metric | Value |
|---|---|
| Current Price | $252.32 |
| Price Target from 24/7 Wall St. | $291.60 |
| Upside/Downside | 15.57% |
| Recommendation | BUY |
| Confidence Level | 90% |

J&J has a beta of 0.206, a dividend yield of 1.99%, and 64 consecutive years of dividend increases (the kind of multi-decade run we screened for in our free Dividend Kings guide, which you can grab here).
Its oncology business is also growing at a double-digit pace. Shares traded at $257.62 noon Thursday, up 1.46% on the session.
MedTech Miss Cools a Strong 2026 Run
The stock is up 26.49% year to date and 38.02% over the past year. It has slipped 3.27% over the past month and now sits between a 52-week low of $180.59 and a 52-week high of $281.07.
J&J reported third-quarter results on October 13. Sales rose 6% to $25.4 billion, and adjusted EPS came in at $2.59. Innovative Medicine grew 7.9%. MedTech grew only 2.5%, and shares fell after the device miss.
Management also reset adjusted EPS guidance to $11.05 to $11.15 to account for the Firefly Bio and SAIL Biomedicines deals. It announced a $5.5 billion resolution of the ovarian talc litigation as well.
Why Bulls See $304 and Beyond
The bull case is $304.22. TREMFYA grew 68.2%, and management believes it can become a “$10 billion plus franchise.” Oncology grew about 17%, and J&J wants to be the top oncology company by 2030 with sales above $50 billion.
Management sees “a clear path to double digit growth by the end of the decade” without any further acquisitions. More catalysts are on the calendar: the OTTAVA robot, a DePuy Synthes spin targeted for mid-2027 and a December 8 Enterprise Business Review.
On the ratings side, 16 analysts rate the stock a Buy or Strong Buy.

What Could Go Wrong for J&J
The bear case sits at $252.88, essentially flat. STELARA sales fell 54%, and Abiomed declined 1.5%. The deal dilution is $1.36 per share next year, which puts our forward EPS input at risk.
As a counterpoint, management said EPS growth would approach 9% without those transactions, and the talc agreement could remove a long-running drag.

How J&J Compares to Merck and AbbVie
Merck (NYSE:MRK) is a direct oncology rival. It trades at 15x forward earnings, but KEYTRUDA’s patent expiration explains part of that discount.
AbbVie (NYSE:ABBV) competes with TREMFYA in immunology. It trades at 16x forward earnings while growing revenue 10.2%.
| Company | Forward P/E | Dividend Yield | Revenue Growth (YoY) |
|---|---|---|---|
| J&J | 21 | 1.99% | 6.6% |
| Merck | 15 | 2.34% | 5.1% |
| AbbVie | 16 | 2.43% | 10.2% |
J&J accounts for a premium multiple, so our target looks somewhat aggressive next to these peers. That premium gets diversification and a lower risk of losing exclusivity on a single key drug.
Why J&J’s Defensive Profile Supports Our Target
A 24/7 Wall St. price target of $291.60 supports a buy with 90% confidence. Durable pharma growth is the deciding factor.
The thesis strengthens if TREMFYA and oncology keep growing faster than STELARA declines. It weakens if MedTech weakness spreads beyond Abiomed and international markets.
Our model projects these values if current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $255.36 |
| 2027 | $291.60 |
| 2028 | $323.87 |
| 2029 | $351.98 |
| 2030 | $380.13 |
J&J would need to keep executing on its current strategy for these projections to hold. The DePuy Synthes spin or new pipeline results could move the path significantly in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.