Johnson & Johnson’s Next Growth Engine Is Taking Shape
Johnson & Johnson's oncology and immunology pipeline is firing on multiple cylinders, but a collapsing blockbuster drug and mounting litigation costs threaten to cancel out every gain. Here is whether the bull case or the headwinds win.

Johnson & Johnson (NYSE:JNJ | JNJ Price Prediction) trades at $270.26. The 24/7 Wall St. price target points to $311.49 over the next 12 months, which means 15.3% upside. Our model rates the stock a buy with 90% confidence, which is a high-conviction reading.
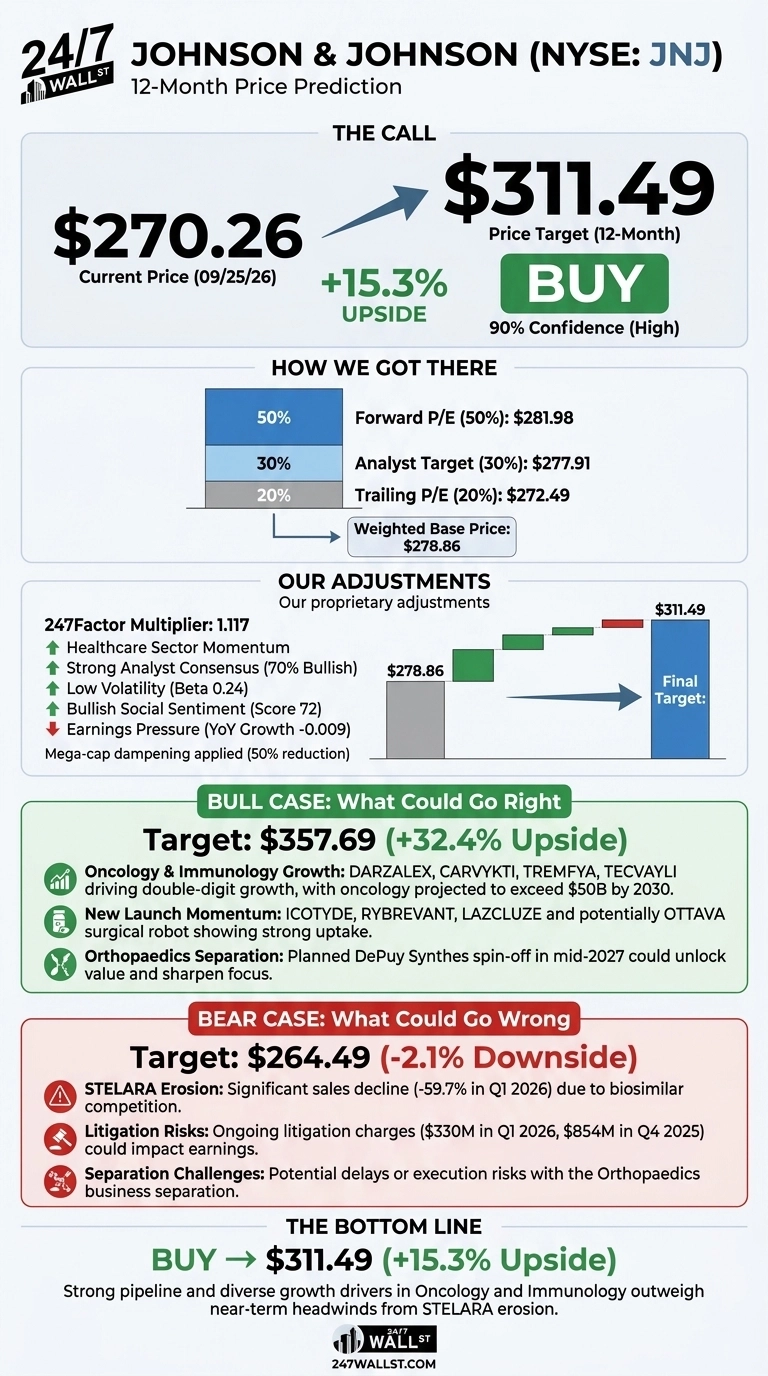
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $270.26 |
| Price Target from 24/7 Wall St. | $311.49 |
| Upside/Downside | 15.3% |
| Recommendation | BUY |
| Confidence Level | 90% |

On September 25, J&J reported CARVYKTI infusion led to five-year treatment-free remissions in 50% of patients with early line multiple myeloma.
The same day, TREMFYA became the first and only IL-23 inhibitor to significantly improve spinal pain in axial psoriatic arthritis. Management says it has “line of sight to double-digit growth by the end of the decade.”
A 56% Rally Has J&J Knocking on Its Record High
Shares gained 56.4% over the past year and 32.69% year to date. The stock sits 3.8% below its 52-week high of $281.07.
July’s second-quarter report supported the run: sales reached $25.3 billion, up 5.6% operationally, and adjusted EPS of $2.90 rose 4.7%. Excluding STELARA, J&J grew at double-digit rates. Management raised adjusted operational EPS guidance to $11.50 to $11.65.
Oncology and Immunology Could Carry J&J to $357
Management expects J&J to become the No. 1 oncology company by 2030, with oncology sales above $50 billion. Last quarter, DARZALEX topped $4 billion, CARVYKTI grew 47.7% and TECVAYLI grew 56.1%. TREMFYA rose 71% to $2 billion, and more than 11,000 patients started oral psoriasis drug ICOTYDE.
Catalysts include a milvexian results, possible FDA clearance for the OTTAVA surgical robot and the DePuy Synthes separation targeted for mid-2027. Analysts lean positive with 5 Strong Buy and 11 Buy ratings against 1 Sell and consensus target of $277.91. Bulls see $357.69, a 32.4% gain.

Stelara Erosion and Litigation Could Stall the Rally
JNJ’s STELARA sales fell 59.7% to $656 million in Q1. Biosimilar competition cut second-quarter growth by about 460 basis points. Litigation charges were $330 million in Q1 2026, following $854 million in Q4 2025. Analysts lowered consensus fiscal 2026 EPS to $11.0733 from $11.5743 90 days ago.
Q1 free cash flow fell 55.42%, but management expects full-year free cash flow approaching $21 billion, above the $19.7 billion generated in 2025. A bear case of $264.49 means a fall of just 2.1%.

J&J Trades at a Premium to Merck and AbbVie for Good Reason
Merck (NYSE:MRK) is J&J’s most direct oncology rival, trading at 15 times forward earnings. KEYTRUDA sales rose 12% to $8.03 billion in Q1. The discount reflects concentration risk: KEYTRUDA makes up nearly half of pharmaceutical revenue as its patent expiration approaches.
AbbVie (NYSE:ABBV) competes through Skyrizi, which grew 24.4% to $5.505 billion last quarter. AbbVie trades at 16 times forward earnings with revenue up 10.2%. It offers a cheaper growth profile, though Humira’s fall mirrors J&J’s STELARA problem.
| Company | Forward P/E | Consensus Target |
|---|---|---|
| Johnson & Johnson | 21 | $277.91 |
| Merck | 15 | $153.65 |
| AbbVie | 16 | $278.61 |
J&J trades at a premium multiple, so further gains must come from earnings growth. Compared with these peers, the 24/7 Wall St. price target looks reasonable.
Pipeline Breadth Tips the Scale Toward J&J
The 24/7 Wall St. price target of $311.49 carries a buy rating and 90% confidence. Breadth tips the scale: 28 products and platforms each generate more than $1 billion annually.
The case strengthens if TREMFYA, ICOTYDE and myeloma drugs grow faster than STELARA declines heading into the December 8 Enterprise Business Review. The case weakens if litigation costs rise or the orthopaedics separation is delayed. J&J’s growth engine is working.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $281.04 |
| 2027 | $311.78 |
| 2028 | $345.98 |
| 2029 | $372.01 |
| 2030 | $398.71 |
The projections depend on J&J continuing to execute on its current strategy. Milvexian trial results or a faster STELARA fall could drove the numbers well above or below these levels.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.