Marvell Technology Will Heat Up Very Soon and I’m Buying in Advance
Marvell Technology shed 17% in a single week after one of the strongest runs in the AI trade, and that gap between the selloff and the business fundamentals is exactly what makes the timing interesting right now.


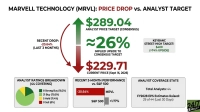
AI investors have reason to track Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction), and last week brought a sharp decline. Shares fell 17.24% in the week ended October 16 to $227.83, after a 168.54% year-to-date run. The next earnings report will show how fast the business is moving.
Why Marvell Sits at the Center of AI Networking
Marvell builds parts that let AI chips talk. These include optical DSPs, Ethernet switches, and custom silicon designed alongside hyperscalers. Clusters keep getting bigger, and every bigger cluster needs more bandwidth. Management addressed bandwidth needs for these multi-site networks.
The needs are projected to be more than 10 times greater than current front-end networks. Marvell sells that connectivity. It is one of several suppliers we profiled in a free report on the companies powering the AI buildout outside the chipmakers.
Three Data Points Driving Marvell’s Growth Case
First, growth is speeding up. Data Center revenue grew 21% in Q4 FY2026, then 27%, then 46% last quarter. Management guided Q3 Data Center growth to roughly 75% year-over-year on total revenue of $3.150 billion. Fiscal 2027 revenue should reach roughly $12 billion.
Second, the deal with Alphabet (NASDAQ:GOOGL) unit Google changes how big the custom business can get. Marvell granted a warrant letting Google acquire up to 7% of its shares, tied to revenue targets. Custom revenue should more than double year over year in fiscal 2028. When an analyst cited a $120 billion cumulative revenue opportunity over six years, management replied, “your math is not wrong.”
Third, margins are expanding. Non-GAAP operating margin rose to 36.6% from 34.8%, and management expects to enter its 38% to 40% target range in Q4. Q3 non-GAAP EPS guidance of $1.10 compares with $0.94 last quarter.
How Marvell Stacks Up Against NVIDIA and AMD
While NVIDIA (NASDAQ:NVDA) dominates AI, its financing exposure keeps growing. Supply commitments reached $279 billion, guarantees for AI cloud partners are limited at $108.5 billion, and days sales outstanding rose to 60 days from 45 days on extended payment terms. If credit tightens for AI builders, Marvell’s biggest partner is Google, a company that designs and pays for its own chips.
Advanced Micro Devices (NASDAQ:AMD) trades at a P/E of about 199, and its non-GAAP operating margin of 27% trails Marvell’s. Data Center makes up only 58% of AMD’s revenue, so AMD offers less focused exposure to the AI expansion.
Risks That Could Derail Marvell’s Run
Concentration concerns me. Data Center now makes up 79% of revenue, a few customers drive much of it, and any hyperscaler could bring more chip design in-house. Chinese trade restrictions and $4.963B of debt due in future years add risk. The stock also swings hard: it fell 10.28% on the day it reported a beat in August.
A strong balance sheet protects against those risks. Net debt runs just 0.27 times EBITDA. The Google warrant gives Marvell’s largest partner a stake in keeping the relationship going. Over the last seven quarters, Marvell reported six beats and no misses.
What to Watch as Marvell’s AI Business Scales
The quarterly dividend is only $0.06, so Marvell offers little for income-focused investors and stands primarily as a growth story. Buybacks of $2.0401B in fiscal 2026 returned capital to shareholders. With Data Center growth expected to top 60% in fiscal 2028, investors will watch whether bookings and margins keep pace with that outlook.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.