35 Analysts Bullish, 15 on the Fence: What Netflix Needs to Show This Quarter
Netflix reports Q3 earnings on October 20 with shares sitting near a 52-week low and analysts split between conviction and caution. Whether the quarter calms those nerves or deepens them depends on a few specific numbers management has already put…

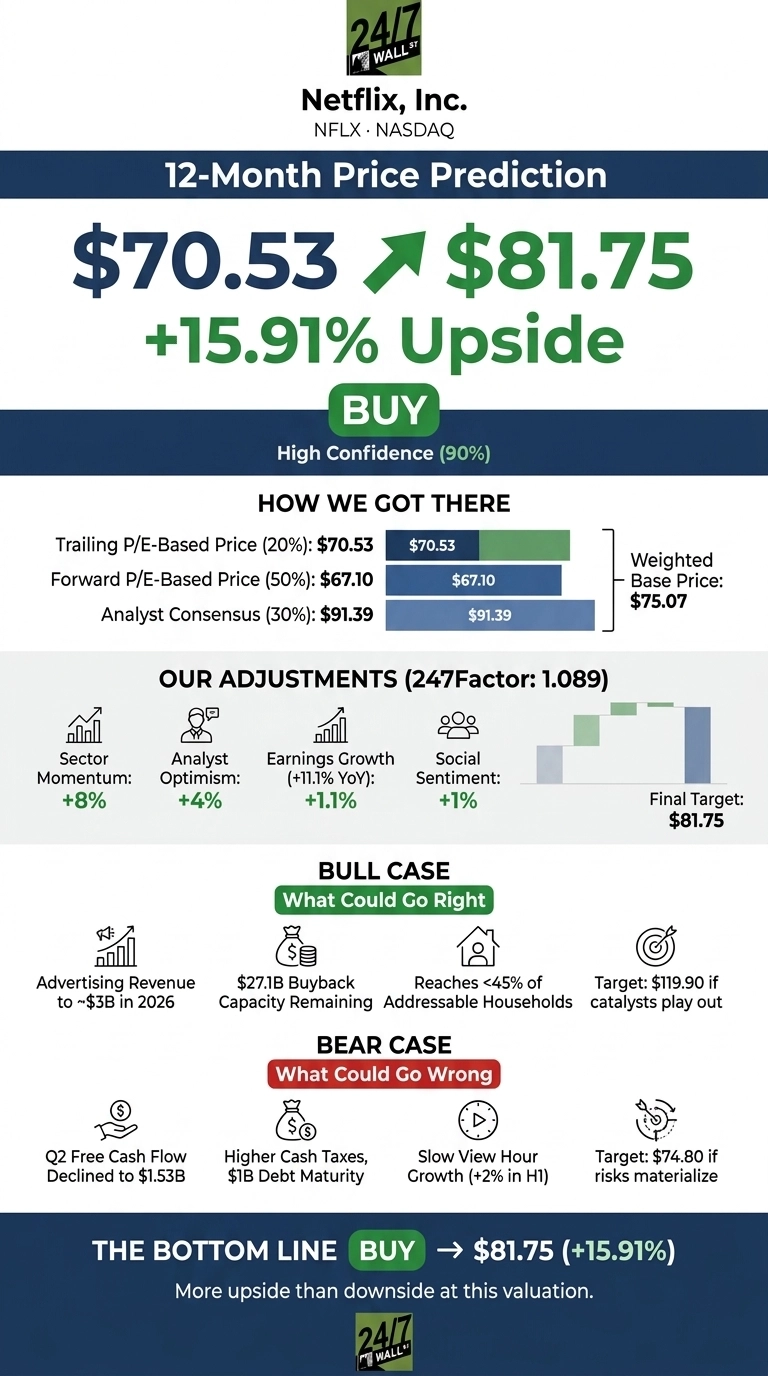
Third-quarter results from Netflix (NASDAQ:NFLX | NFLX Price Prediction) are due on October 20 after the close. Shares head in at $70.53. The 24/7 Wall St. price target for Netflix is $81.75, which means 15.91% upside. The stock earns a buy rating with high confidence from the model.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $70.53 |
| Price Target from 24/7 Wall St. | $81.75 |
| Upside/Downside | 15.91% |
| Recommendation | BUY |
| Confidence Level | 90% |
Wall Street leans the same way. Netflix has 7 Strong Buy, 28 Buy, 15 Hold and 1 Sell ratings, and the consensus target is $91.39.
Management guided Q3 to revenue of $12.86B and EPS of $0.82. Consensus stands at $0.8229 and $12.88 billion, so Netflix needs a clean beat on both lines.

A 40% Slide Sets a Low Bar Heading Into Earnings
Over the past year the stock has lost 40.41%, including a 24.78% drop year to date and a 7.7% decline over the past month. It is up 0.33% for the week. That leaves shares much closer to the $65.08 52-week low than to the $124.86 high. On Friday the stock fell 2.86% after Netflix, a Walt Disney (NYSE:DIS) rival, replaced its content chief with a former Disney executive.
In Q2, revenue grew 13.4% to $12.56B, slightly missing expectations. EPS of $0.80 came in ahead of the $0.79 consensus. Even so, shares fell 7.26% on the day. This stock has been punished hard for misses, with an average response of -9.89%.

Why Bulls See $119.90 Within Reach
Our one-year bull case is $119.90. Advertising is expected to roughly double to about $3B in 2026. Management says the revenue gap between the ad tier and the ad-free plan “is narrowing.”
Netflix also has $27.1B left on its buyback authorizations, and it reaches less than 45% of an estimated 800 million addressable households. Full-year guidance still calls for operating margin of 31.5%.

Risks Worth Watching on October 20
Our bear case is $74.80. Q2 free cash flow fell to $1.53B from $2.27B. Higher cash taxes explain part of that drop, and full-year guidance still points to about $12.5B.
View hours grew only 2% in the first half. A change in content leadership adds execution risk, and $1B of debt needs refinancing this year.
Netflix Earns a Premium Over Its Streaming Rivals
Disney is the most direct competitor in streaming, and Disney+ and Hulu SVOD operating income more than doubled to $712 million last quarter. Disney trades at a lower multiple, though its operating margin is roughly half of Netflix’s.
Spotify Technology (NYSE:SPOT) runs a similar subscription-plus-ads model and grew revenue 13.93%, about the same rate as Netflix, yet it trades at nearly twice Netflix’s multiple.
| Company | P/E | Operating Margin |
|---|---|---|
| Netflix | 27 | 29.49% |
| Disney | 15 | 14.65% |
| Spotify | 49 | 12.79% |
Netflix pairs the best margins in this group with a mid-range multiple, so the comparison makes the 24/7 Wall St. price target look reasonable, arguably conservative.
What Could Move Netflix After This Report
The 24/7 Wall St. price target remains $81.75, with a buy rating and 90% confidence. The bear case still stands above today’s price.
The case strengthens if Q3 meets the 33.2% margin guide and advertising stays on rate. The case weakens if Netflix cuts full-year revenue guidance. At this valuation, the model finds more upside than downside.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $71.93 |
| 2027 | $85.86 |
| 2028 | $94.58 |
| 2029 | $99.38 |
| 2030 | $110.00 |
These projections assume Netflix keeps executing on pricing, ads and live events. If advertising scales faster than expected, the five-year bull case reaches $238.33.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.