The AI Trade Is Changing. These Stocks Could Be Next.
GPU stocks dominated the first wave of AI spending, but the money is quietly shifting toward a different set of chipmakers. Three names are positioned right in that path, and their 2027 price targets require a closer look.


For the first period of the AI build-out, investors poured into GPU makers. Now spending is moving toward custom silicon, optical connectivity, inference CPUs and edge devices, and three chipmakers sit right in that path.
Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) is up 168.54% year to date. Intel (NASDAQ:INTC) is up 143.5%, and Qualcomm (NASDAQ:QCOM) has gained 2.21%. Last week Marvell fell 17.24% and Intel dropped 14.18%, so all three start 2027 from a lower base. Here’s how each could reach a bold target next year.
The spending shift reaches well beyond silicon, into the power, cooling, and networking that feed every new data center (our free report profiles seven of those non-chipmaker suppliers: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers)).
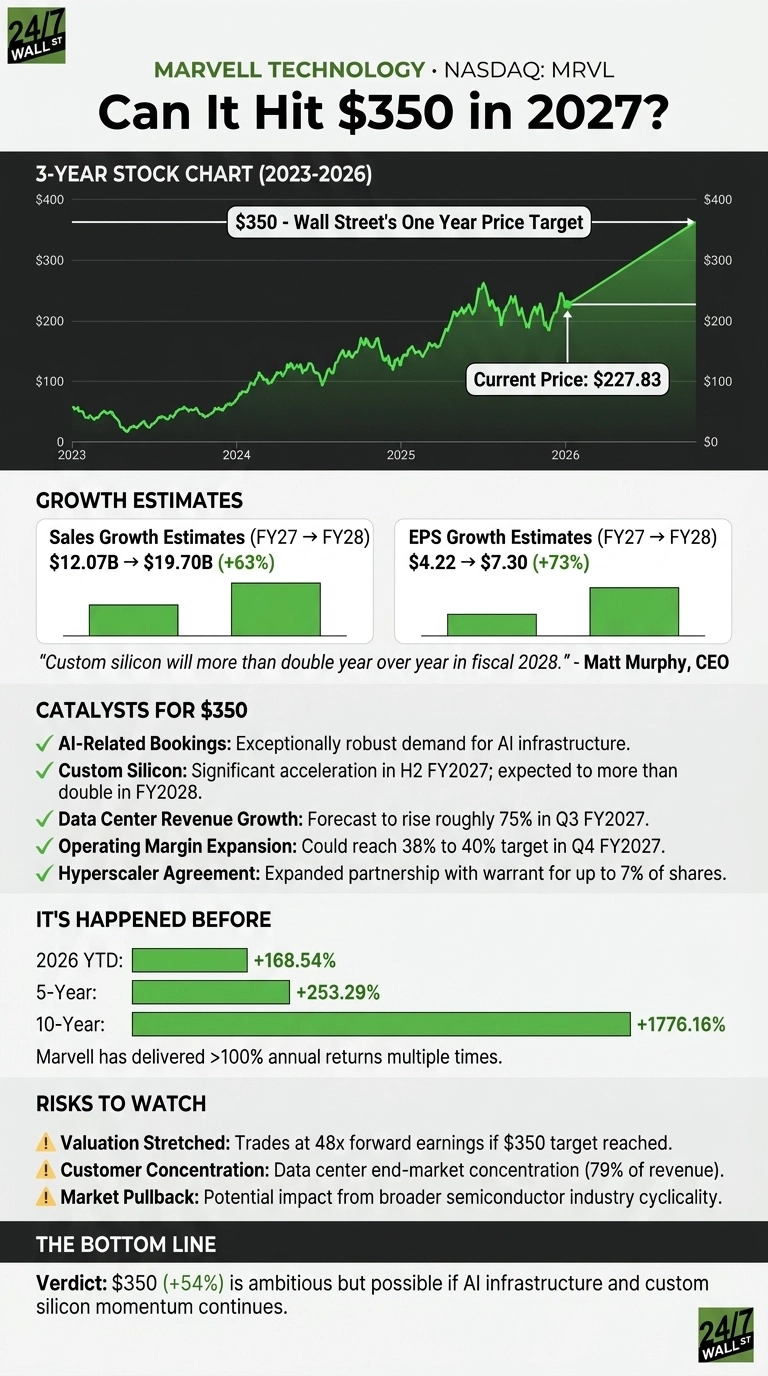
Marvell Can Hit $350 in 2027 if Custom Silicon Delivers
Data center now makes up 79% of Marvell’s revenue, and that business grew 46% last quarter. CEO Matt Murphy said custom silicon “will more than double year over year in fiscal 2028.” An expanded hyperscaler agreement includes a warrant for up to 7% of Marvell’s shares, linked to revenue milestones.
At $227.83, MRVL trades at 31x the fiscal 2028 EPS estimate of $7.2963. Reaching $350 would be a 54% gain and put the stock at 48x earnings. That’s a premium, but analysts expect 73% EPS growth, and 90 days ago the estimate was only $6.1994. What might drive Marvell to $350?
- Data center revenue is forecast to rise roughly 75% in the third quarter.
- Operating margin could reach the 38% to 40% long-term target range in the fourth quarter of fiscal 2027.
- Marvell beat both EPS and revenue estimates in each of its last two reports.

A 1,776.16% 10-year return shows MRVL has produced big gains before.
Qualcomm’s Route to $225 Runs Through Cars and Data Centers
Handset revenue fell 20% last quarter. Automotive revenue rose 61% to a record $1.588 billion, its 23rd straight quarter of double-digit growth. CEO Cristiano Amon expects non-handset growth to accelerate “to greater than 60% in fiscal 2027.” Qualcomm’s two hyperscaler custom chip wins begin generating revenue in the December quarter.
At $172.11, QCOM trades at 17x the fiscal 2027 estimate of $10.1967. A 31% gain to $225 would lift that multiple to 22x. Estimates have slipped from $11.0081 90 days ago, and last quarter’s EPS of $2.21 missed consensus by a penny, ending a six-quarter beat streak.
Qualcomm needs execution to change that picture. Three things could help: double-digit price increases that restore margins, a $5 billion fiscal 2027 data center revenue target, and a 2.07% dividend yield. The stock’s 240.7% 10-year return points to steady gains, which matches a moderate target.

Intel’s Turnaround Points Toward $125
Intel’s revenue grew 25.42% last quarter, its strongest growth in more than 15 years. Non-GAAP EPS of $0.42 beat the $0.22 consensus, and Data Center and AI revenue rose 59%. CEO Lip-Bu Tan said agentic AI “is significantly increasing the need for Intel’s CPUs and wafer and advanced packaging offerings.”
At $89.85, INTC trades at 43x the 2027 estimate of $2.1049. At $125, a 39% gain, the multiple would be 59x. To justify that, Intel has to keep beating the 38% EPS growth already forecast.
Its record helps here. Management referenced the company’s seventh consecutive quarter of topping its own financial expectations, and the 2027 estimate has rose from $1.5847 90 days ago. The biggest risk is Intel Foundry, which is still losing $2.1 billion a quarter.

Bottom Line on All Three Targets for 2027
Marvell needs a 54% gain to reach $350. Qualcomm needs 31% to reach $225, and Intel needs 39% to reach $125. EPS estimates for Marvell and Intel keep rising, and Qualcomm’s growth businesses are getting bigger.
A weaker market or tighter chip supply would make these targets harder to reach. Such gains won’t happen every year, but here is the plan for how these three stocks could post outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.