AST SpaceMobile Lost 40% In 2026: A Wall Street Pro Says It’s Going to Double By 2027
AST SpaceMobile has shed nearly half its value while satellite peers soared, yet one Wall Street analyst still sees it doubling from here. The next few launches will either validate that conviction or trigger another round of painful dilution.

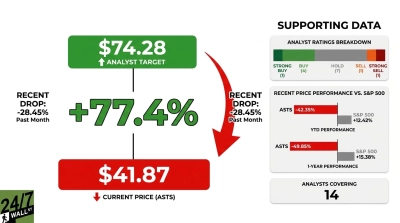
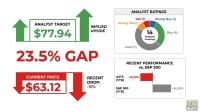
AST SpaceMobile (NASDAQ:ASTS) currently trades at $41.87, while analysts’ consensus price target sits at $74.28. The difference points to 77.4% upside.
AST is building a space-based cellular broadband network that links ordinary smartphones directly to its BlueBird satellites. It counts 60+ mobile network operators covering 3+ billion subscribers as partners.
AST is valued near $12.55B, and Barron’s recently called it the new battleground stock. The biggest bull, Roth MKM’s Scott Searle, carries a $108.00 target, meaning 157.9% upside.
A Launch Loss, Two Misses and Fresh Dilution Cut Shares by 42%
Back-to-back revenue misses did the most damage. Q1 revenue of $14.73M missed by 59.72%, and Q2 revenue of $31.52M missed the $34.40M consensus. Q2 GAAP EPS landed at -$0.77 against a -$0.29 estimate. That figure included a $125.9M loss tied to the BB7 launch incident and an $88.7M induced conversion expense on convertible notes. The operating loss reached $297.6M.
The stock is down 42.35% this year. The slide picked up speed recently, with shares falling 28.45% over the past month. A securities class action now says that management minimized how often capital needs would add debt and dilution, and overstated AST’s competitive position against Starlink’s direct-to-cell service (per the Robbins Geller case summary). A $1.15B convertible notes offering in July heightened the dilution worries.
Roth’s $108 Call Depends on 45 Satellites and a $1 Billion Revenue Year
Searle rates the stock Buy, citing a first-mover moat in direct-to-device broadband, tier-1 carrier partnerships and capital he believes covers the full constellation launch. Management is targeting approximately 45 BlueBird satellites in orbit by early 2027. It still expects revenue approaching $1 billion in the first full year of commercial service, and says government work “could contribute to probably as much as half” of that total.
The balance sheet supports the story. AST holds a ~$1.30B contracted backlog and more than $3.70B in pro forma liquidity, and it confirmed FY2026 revenue guidance of $150M to $200M. The consensus FY2027 revenue estimate is roughly $581.7 million, but individual forecasts run from $345.1 million to $834.1 million.
Conviction is thin, though. Of 14 analysts, 1 rates it Strong Buy, 4 Buy, 7 Hold, 1 Sell and 1 Strong Sell. Estimates are moving the wrong way. The FY2027 EPS consensus has fallen from -$0.6476 to -$1.2782 over 90 days, with no upward revisions in the past month. Scotiabank also cut its rating to Sector Underperform.
Satellite Peers Rallied While AST SpaceMobile Fell Alone
AST’s decline is specific to AST. Its closest US-listed peers are up sharply this year.
Iridium Communications (NASDAQ:IRDM | IRDM Price Prediction) trades at $44.18, up 157.39% this year and down only 5.54% over the past month. Its price now tracks Rocket Lab (NASDAQ:RKLB) under a pending all-stock acquisition by Rocket Lab, expected to close in mid-2027, so deal terms outweigh any analyst target. No reliable consensus target was available.
Viasat (NASDAQ:VSAT) trades at $60.29, up 74.96% this year despite a 21.07% drop over the past month. No dependable consensus target or ratings split was available. Its record $1.40 billion defense backlog gives it a firmer base than AST.
On the targets that could be checked, AST carries the group’s largest analyst-implied upside. It is also the only name in the group with deep losses and large capital needs still ahead.
Down 42% While the S&P 500 Gained 12%
At $41.87, AST has 77.4% implied upside to the $74.28 consensus target set by 14 analysts. Shares are down 42.35% year to date, while the S&P 500 has gained 12.42%. Over one year, AST has lost 49.85% against the index’s 15.38% gain.
The stock sits near its 52-week low of $39.87, far from its high of $133.86. Its beta of 2.706 signals oversized swings, the kind that belong in the slice of a portfolio reserved for speculation (we wrote a free guide on sizing that slice and setting exit rules, here). Analyst targets are one data point and guarantee nothing, especially for a pre-commercial company.
Commercial Launch Decides Whether This Gap Closes
AST SpaceMobile’s case improves if it reaches the 45-satellite mark on schedule and turns on commercial service early enough for 2027 revenue to move toward the top of the estimate range. Launch delays that push service into late 2027 would raise the risk, because that would mean more convertible raises, more dilution and more falling estimates.
On the bull side, AST has production running at approximately six satellites per month, 10 launches booked and funded government contracts. The downside is just as concrete: two straight misses, an active lawsuit and Starlink competing for the same customers.
I lean cautious. The 77.4% gap is real, but the next few launches matter more than any price target.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.