CoreWeave’s Financing and Interest Rate Concerns Will Show Up In One Place
CoreWeave borrowed tens of billions to build AI infrastructure while interest rates climbed, and the next earnings report will reveal whether its operating leverage can actually outrun the financing costs threatening to swallow it whole.

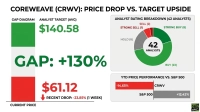
CoreWeave (NASDAQ:CRWV) trades at $61.12. Its stock and bonds sold off last week on rate-hike fears, and the next earnings report will show what those fears actually cost.
CoreWeave leases GPU cloud capacity to enterprises and AI labs, competing as a pure-play rival to the hyperscaler clouds. It is one of the picks-and-shovels names driving the AI expansion (we covered seven other AI infrastructure suppliers, from power to cooling, in a free report here). It is building that capacity with borrowed money. Shares fell 23.85% over the past week as the 10-year Treasury yield touched 5.31% before falling to 5.09%.
A $104 Billion Backlog Is Turning Into Operating Leverage
Second-quarter revenue rose 112.3% to $2.575 billion, beating estimates, while GAAP EPS of -$1.14 beat the -$1.447 consensus. Adjusted EBITDA reached $1.510 billion at a 59% margin. Backlog hit $104 billion, before more than $25 billion in early third-quarter commitments.
Pricing is improving too. In July, prices rose roughly 25% across SKUs, and the company expects adjusted operating margins to reach the low teens in the fourth quarter. The weighted average cost of debt was cut by almost 300 basis points, management says. Goldman Sachs (NYSE:GS | GS Price Prediction) just upgraded the stock to Buy from Neutral after the drawdown.
Interest Costs Already Dwarf Operating Profit
Interest expense hit $640 million last quarter, up from $267 million a year earlier, against an operating loss of $49 million. Management guided third-quarter interest to $860 million to $940 million. Total debt reached $51.6 billion, up from $29.8 billion at year-end, and debt-to-equity stands at 8.94.
The expansion keeps eating capital. Full-year capex guidance is $35 billion to $39 billion, and second-quarter free cash flow was -$5.743 billion. With the 10-year yield in the 93.2 percentile of its past year, each new loan prices off a higher base. A securities class action over construction delays is also pending.
One Earnings Report Can Settle This Debate
CoreWeave has more than $6.9 billion in liquidity, and management says asset-level debt gets repaid over each roughly five-year customer contract. Whether margins grow faster than interest costs remains uncertain. The third-quarter report provides the first clean test.
Analysts Target $140 While the Stock Trails the Market
The average analyst target of $140.58 implies 130% upside, but targets are estimates. Some may date from when the stock traded near its $141.79 52-week high. Of 42 analysts:
- Strong Buy: 8
- Buy: 23
- Hold: 8
- Sell: 2
- Strong Sell: 1
CoreWeave is down 14.65% year to date, while the S&P 500 is up 12.42%. Over the past year, the stock is down 55.34% against the index’s 15.38% gain. It trades at about 24x EV/EBITDA, near its $59.51 52-week low.
Interest Expense Will Decide CoreWeave’s Next Move
At $61.12, CoreWeave’s outlook depends on financing costs.
The financing and rate concerns will show up in one place: the interest expense line. The figure to compare it against is the $860 million to $940 million guidance, and then against adjusted operating income guidance of $200 million to $260 million.
A bullish case needs interest at or below the low end, adjusted margins tracking toward the low teens, and new debt priced at tighter spreads. A bearish case builds if interest breaks above the range, if refinancing costs climb with Treasury yields, or if delivery delays push revenue out while debt keeps accruing.
If the third quarter confirms operating leverage, investors may reconsider a stock trading near its 52-week low. But before that report, the bullish case depends on cheaper money just as the 10-year sits near 5.09%.
Until margin growth exceeds interest expense, financing risk remains the central question for the stock.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.