NVIDIA Keeps Falling and Wall Street Won’t Move Its Target. Is It Time To Buy?
NVIDIA just doubled its revenue yet the stock keeps sliding, and Wall Street still refuses to budge its price target. Something in that gap between the business and the share price tells a story worth understanding before the next earnings…


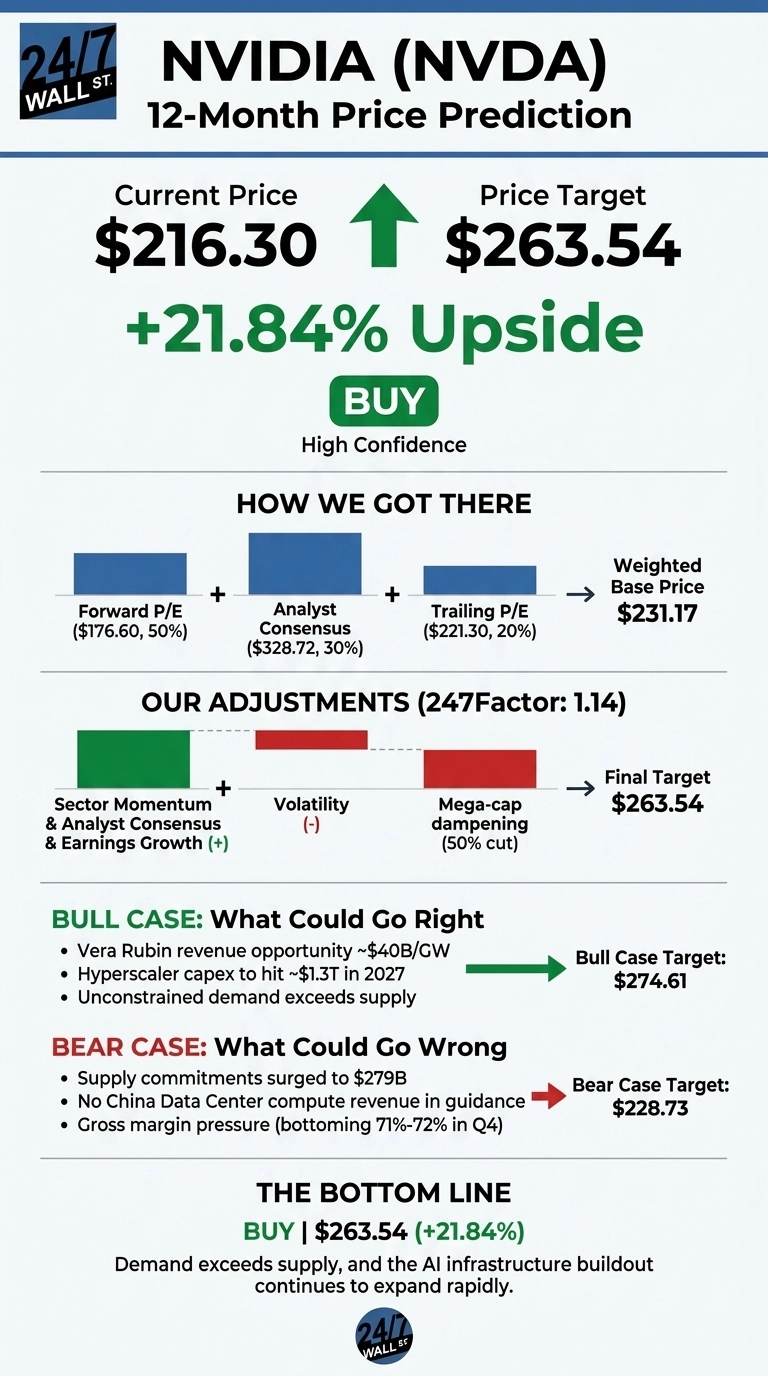
The 24/7 Wall St. price target for NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) is $263.54, and our model rates the stock a buy. Shares traded at $216.30 midday Thursday. That puts our target 21.84% above the current price. It is 19.09% above Wednesday’s $221.30 close, which was the price our model used. Confidence is high.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $216.30 |
| Price Target from 24/7 Wall St. | $263.54 |
| Upside | 21.84% |
| Recommendation | BUY |
| Confidence Level | 90% |

The stock and the business are moving in opposite directions. NVIDIA just doubled its revenue, yet the shares fell 8.91% in a week. The consensus analyst target remains at $328.72. That gap frames the debate over where the stock goes next.
AI Fears Hit Chip Stocks While NVIDIA’s Revenue Doubled
NVIDIA, Advanced Micro Devices (NASDAQ:AMD) and Micron Technology (NASDAQ:MU) fell as the AI stock sell-off deepened, and pressure on chip stocks carried into Thursday. Shares are still up 16.25% year to date and 2.53% over the past month.
They trade 11.12% below the $243.37 52-week high. Of CoreWeave (NASDAQ:CRWV), NVIDIA CEO Jensen Huang said Thursday CoreWeave doesn’t need a backstop, showing concerns about how customers are financed.
Second-quarter fiscal 2027 revenue came in at $96.22 billion, up 105.85% and beating the $92.07 billion estimate. EPS of $2.22 also exceeded the $2.0887 consensus. Data Center revenue rose 117% to $89.023 billion.
Why Bulls See $274 and Beyond
Management guided third-quarter revenue to $108 billion. It expects growth of about 70% in fiscal 2028 and says supply is the limiting factor. Each gigawatt of Vera Rubin brings NVIDIA about $40 billion in revenue, compared with $25 billion for Blackwell.
The five largest hyperscalers are expected to spend about 1.3 trillion in 2027. “Now, compute is revenue,” Huang said. Wall Street largely agrees: 49 analysts rate the stock Buy and 10 rate it Strong Buy. The bull case is $274.61.

What Could Drag NVIDIA Toward $228
Supply commitments have grown to $279 billion, and guarantees to partners are capped at $108.5 billion. Customers are taking longer to pay: days sales outstanding rose to 60 days from 45. Guidance includes no China Data Center compute revenue. Gross margin should bottom at 71% to 72% in the fourth quarter.
The bulls have answers for some of this. Memory costs are behind the margin pressure, and price increases taking effect next year should lift margins back to 72% to 73%. The longer payment terms went to investment-grade buyers. Even the bear case of $228.73 remains above Wednesday’s close.
Is NVIDIA Cheaper Than AMD and Broadcom?
AMD competes directly with NVIDIA in GPUs. It trades at 215x trailing earnings, compared with NVIDIA’s 45x. AMD’s latest quarterly revenue rose 50.1%, and its gross margin is 49.5%. NVIDIA’s gross margin is 71.07%.
Broadcom (NASDAQ:AVGO) designs custom AI chips that hyperscalers use as options to NVIDIA’s GPUs. Its AI semiconductor revenue rose 221% to $16.7 billion. Broadcom’s total growth still trailed NVIDIA’s.
| Company | Latest Quarter Revenue Growth | Market Cap |
|---|---|---|
| NVIDIA | 105.85% | $5.23 trillion |
| AMD | 50.1% | $894.06 billion |
| Broadcom | 85.5% | $1.61 trillion |
NVIDIA is growing faster than both peers at a lower multiple than AMD. Next to these two, our 24/7 Wall St. price target looks conservative.
Why I Side With the Bulls at $216
The 24/7 Wall St. price target is $263.54, and our model rates NVIDIA a buy with 90% confidence. For me, the deciding factor is that demand still exceeds supply, and the expansion runs well beyond the GPU maker itself (we highlighted seven power, cooling, and networking names riding the same wave in a free AI infrastructure report).
Keep an eye on whether the November 17 earnings report confirms Vera Rubin is ramping on schedule. A cut to hyperscaler capex plans would weaken the case. On the numbers available today, the pullback has extended the gap to our price target.
This is the level our model projects NVIDIA could trade at if current growth and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $236.40 |
| 2027 | $263.54 |
| 2028 | $288.76 |
| 2029 | $316.39 |
| 2030 | $346.67 |
The projections rest on NVIDIA continuing to execute its current strategy. The results could land well above or below them depending on how long AI spending lasts and on export policy toward China.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.