This Billionaire Investor Called the Stock Market a ‘Hollow Tree’ — Here Are the Disturbing Numbers That Say He’s Right
A billionaire bond investor is sounding alarms about what he calls a hollow tree at the center of the stock market, and the numbers hiding beneath the S&P 500's record highs suggest his warning deserves a closer look.

Wall Street’s major indexes can tell a comforting story even when the stocks beneath them are struggling. A handful of trillion-dollar technology companies can push the S&P 500 toward record highs while hundreds of other businesses quietly slide into correction territory. It’s a peculiar feature of a market increasingly dominated by its biggest companies, and one that can leave investors with a misleading picture of Wall Street’s health.
With artificial intelligence spending reaching historic levels, bond yields climbing, and borrowing costs squeezing corporate balance sheets, the divide between the market’s winners and losers is becoming harder to ignore.
Billionaire bond investor Jeffrey Gundlach believes the stock market is concealing serious structural weakness. And the numbers suggest he has a point.
A Healthy-Looking Market With a Rotten Core
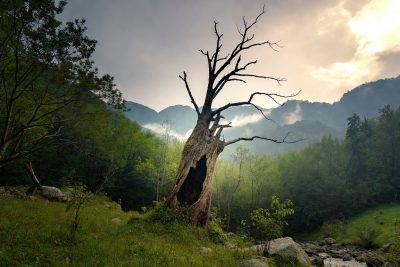
During an October 9 interview with economist David Rosenberg, the DoubleLine Capital founder compared the stock market to a century-old silver maple tree at his Buffalo home.
The tree appeared healthy, with abundant leaves and sprawling branches. But after an enormous limb broke off, Gundlach discovered the trunk was completely hollow. The tree had to come down.
He sees a similar problem developing in stocks. The headline indexes look healthy, but the individual companies supporting them tell another story.
On October 16, MarketWatch reported that 191 S&P 500 stocks, or approximately 38% of the index, were trading at least 20% below their 52-week highs. That’s the traditional definition of a bear market.
| Market Breadth Measure | Reading |
| S&P 500 stocks in bear markets | 191 |
| Share of index in bear markets | 38.2% |
| Decline required for a bear market | 20% |
| S&P 1500 stocks in correction territory or worse, cited by Rosenberg | 75% |
The last figure is especially troubling. Rosenberg said three-quarters of the broader S&P 1500 were already down at least 10% from their highs.
Let’s put the risk Gundlach is discussing into perspective. Investors buying an S&P 500 index fund might believe they’re participating in a broad market rally. Yet the index is weighted by market capitalization, meaning companies with the largest valuations exert the greatest influence.
When Nvidia (NASDAQ:NVDA | NVDA Price Prediction), Microsoft (NASDAQ:MSFT), and other technology giants perform well, their gains can conceal weakness across dozens of smaller constituents. Between July 13 and late August, Microsoft and Nvidia added $1.42 trillion in market capitalization, while the other 71 technology stocks collectively lost $22 billion.
The market’s apparent strength may depend on a remarkably narrow foundation.
The AI Credit Market Is Flashing Another Warning
Gundlach’s concerns extend beyond stock prices. He’s also watching the debt markets, where artificial intelligence companies are encountering increasingly expensive financing.
During the interview, he identified a divergence in corporate credit spreads — the additional interest investors demand for lending to companies instead of the federal government.
His figures showed:
- AI-related investment-grade debt: Spreads widened approximately 75 basis points over the preceding year.
- AI-related high-yield debt: Spreads widened more than 150 basis points.
- Non-AI corporate debt: Spreads remained comparatively stable.
In other words, lenders are demanding higher compensation specifically for financing AI-related businesses.
This is occurring as hyperscalers commit hundreds of billions of dollars to data centers, chips, and electricity infrastructure. Goldman Sachs previously warned that AI’s debt-fueled expansion was putting pressure on corporate credit markets, with hyperscaler leverage ratios doubling to 1.8 times in just six months.
The consequences are already visible. CoreWeave (NASDAQ:CRWV), whose debt-heavy financing model has unsettled neocloud investors, saw its bonds fall to approximately 81 cents on the dollar during October’s technology sell-off, according to MarketWatch.
The danger isn’t necessarily that AI spending stops tomorrow. It’s that companies counting on cheap financing could face higher borrowing costs precisely when their projects require more capital.
Higher Interest Rates Make the Cracks Worse
Gundlach also highlighted a deteriorating backdrop for government borrowing. He estimated annual federal interest expenses at $1 trillion to $1.5 trillion, alongside deficits exceeding $2 trillion. Meanwhile, the 30-year Treasury yield had reached approximately 5.62%, its highest level in nearly 25 years.
The Congressional Budget Office’s projections illustrate how quickly borrowing costs can compound. Interest rates running 1.5 percentage points above its baseline could add $6 trillion to federal deficits through 2036, potentially pushing publicly held debt to 133% of GDP.
Higher Treasury yields compete directly with stocks for investor capital. They also raise the cost of financing corporate expansion, particularly for businesses whose profits remain years away. That makes AI infrastructure companies particularly vulnerable when investors begin questioning future returns.
Gundlach’s preferred defense is maintaining at least 20% of a portfolio in liquid, short-duration, high-quality fixed-income investments, where he said yields around 6% were available.
Key Takeaway
In short, Gundlach isn’t arguing that every stock is about to collapse. He’s warning that a rising index can disguise growing financial stress.
With nearly four in 10 S&P 500 companies already in bear markets, his hollow-tree analogy has numerical support.
Investors should consider trimming outsized positions in richly valued technology stocks, scrutinizing corporate debt, and maintaining enough liquidity to capitalize on future declines. A diversified portfolio with quality companies, manageable debt, and dependable cash flow offers a better defense than simply assuming the biggest stocks will keep carrying the market.
The tree may still be standing, but investors would be wise to inspect its roots.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.