Tesla is expected to report third-quarter earnings at about 4:15 PM ET tonight, and expectations are unusually low for one of Wall Street’s most closely watched stocks.
Analysts expect earnings of just $0.45 per share, following a disastrous second quarter in which Tesla missed EPS estimates by 38.51%.
Meanwhile, Tesla’s aggressive AI investments are putting pressure on cash flow. Free cash flow turned negative last quarter, and capital expenditures are expected to exceed $25 billion in 2026.
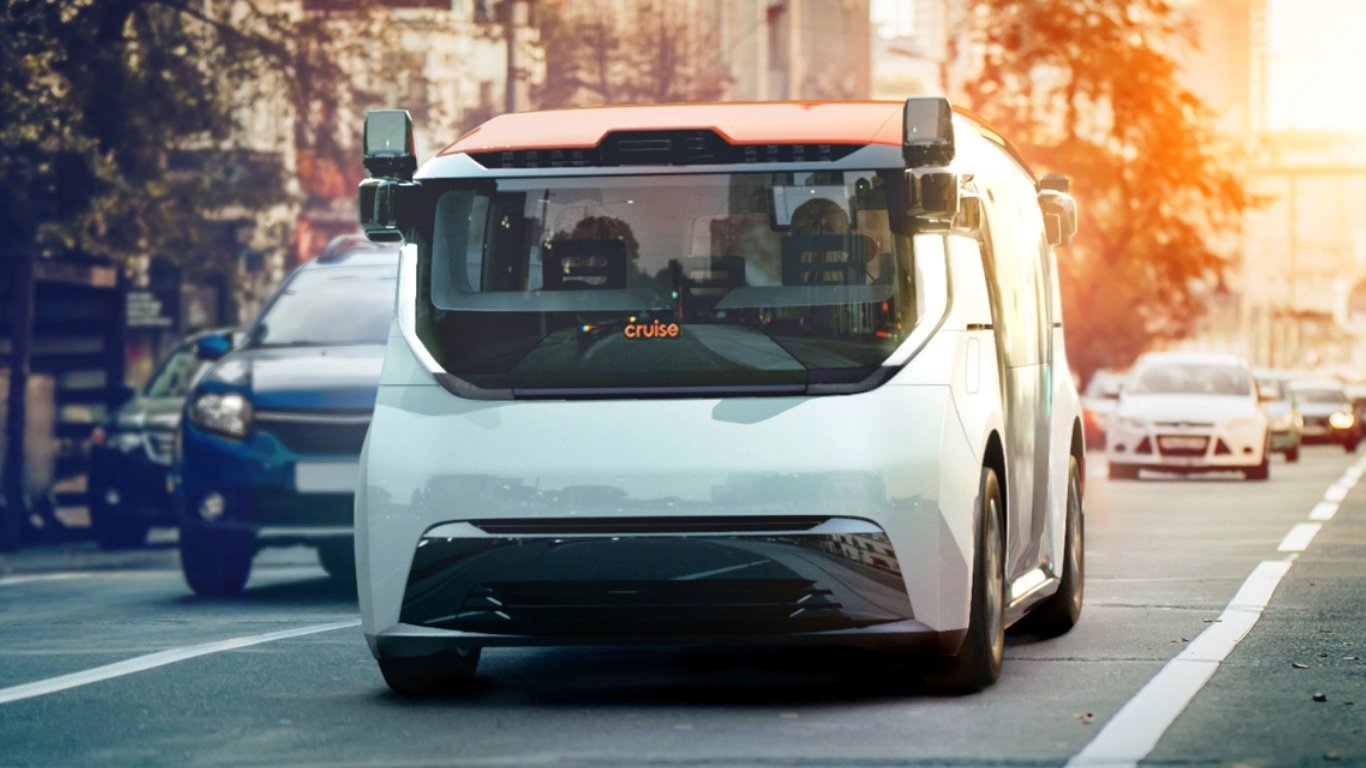
Investors will be watching for updates on robotaxi expansion,Cybercab production, and the Optimus humanoid robot. These initiatives are increasingly central to Tesla’s long-term valuation as margin pressure hits its automotive and energy businesses.
With Tesla trading at a staggering 389 times earningsand prediction markets assigning just a 34.5% probability of an EPS beat, the stakes are enormous. Strong progress toward commercializing autonomous driving and robotics could help justify the premium valuation.
Another earnings disappointment and accelerating cash burn could raise difficult questions about how much future growth is already priced into the stock.
Tesla’s Q3 earnings report included two major developments that could be even more important to its long-term valuation than the company’s earnings beat.
First, Tesla confirmed that it began providing Robotaxi rides using Cybercabs in Austin on September 3, marking a significant milestone in its autonomous driving ambitions.
Meanwhile, active Full Self-Driving (FSD) subscriptions surged 67% year over year to 1.74 million, highlighting growing adoption of Tesla’s autonomous driving technology.
The company also announced that production of its Optimus humanoid robot has begun on high-volume production lines in Fremont.
These developments come as Tesla’s traditional automotive business faces pressure, with automotive revenue declining 3% year over year to $20.56 billion.
The big takeaway: Tesla’s robotaxi and robotics initiatives are beginning to reach tangible production and commercialization milestones. Whether those businesses can eventually generate meaningful profits remains a key question for investors.
Tesla just reported third-quarter earnings, beating Wall Street’s expectations on both revenue and adjusted earnings per share. Here are the key numbers:
Revenue: $28.05 billion vs. $27.88 billion expected (Beat)
Adjusted EPS: $0.48 vs. $0.43 expected (Beat)
Adjusted EBITDA: $3.90 billion vs. $3.71 billion expected (Beat)
Gross Margin: 19.6%, up 160 basis points year over year
Quick Read:
Double beat: Tesla topped revenue and adjusted EPS estimates, although revenue was flat year over year and adjusted earnings declined 4%.
Profitability remains under pressure: Operating income plunged 56% to $718 million, while free cash flow fell 62% to $1.53 billion.
Tesla also reported 486,532 vehicle deliveries, down 2% year over year, as investors look toward robotaxis, autonomous driving, and robotics for future growth.
At $385.52 into tonight's earnings report, Tesla trades at 346 times trailing earnings and 180 times forward, a price that demands the quarter deliver on 25.5% revenue growth. The stock sits well below its $498.83 52-week high, and the $397.83 consensus target leaves barely 3% of room from here.
Traders on Polymarket put a modest majority on Tesla clearing the $0.45 consensus tonight, and that confidence has eased in recent days. Volume is thin, making this a sentiment read: the crowd sees a beat as likely, with meaningful uncertainty after the Q2 miss.
A 0.71 put/call ratio into tonight's earnings report says call buyers own the setup, with the heaviest open interest stacked at the $380 strike just above the $375 at-the-money line. Traders are leaning bullish, and crowded call positioning leaves the least cushion if the numbers disappoint. At-the-money implied volatility of 89.3% on Friday-expiring contracts shows how wide the market expects the reaction to be.
In Q2, Tesla's revenue beat estimates while margins did not carry through to the bottom line. For Q3, the key question is whether AI and robotaxi spending is finally showing up in profit.
A 3.64% jump at $387.31 adds roughly $50 billion of market value to a $1.5 trillion company in a single session. Keep an eye on whether it holds the level into the close.
Optimus has come up on all four of the last four calls, but robotaxi scaling and its regulatory hurdles is the thread most likely to decide tonight's reaction, with FSD adoption and CapEx questions feeding the same cash-flow worry we flagged this afternoon. Analysts have also pressed on battery and semiconductor supply constraints in each of the last three calls, so any commentary on timing there lands straight on the after-hours move.
Tesla already beat delivery expectations, but tonight's Q2 report forces a harder question: can margins hold up once tariff tailwinds and regulatory credits stop doing the heavy lifting?
Investors keep debating Tesla's car margins while a completely different business quietly rewrites the company's growth story. The real question is whether the market is pricing the wrong Tesla entirely.
Tesla (NASDAQ:TSLA | TSLA Price Prediction) looks expensive on every traditional metric and cheap on every forward one. That tension has helped define the stock’s bull case in 2026, which has seen shares of…
Tesla's FSD subscriptions are surging, Robotaxi is hitting the streets, and Optimus robots are coming off production lines, yet the stock sits 22% in the red for the year. Here is what bulls and…
Tesla posted record deliveries and 25% revenue growth in the same quarter it missed earnings by nearly 40% and burned over a billion in free cash flow. Wall Street cannot agree on which number…
ARK Investment Management just published a Tesla price target so far above Wall Street consensus that it practically requires two entirely new industries to exist at massive scale by 2031, and one of them…
Tesla (NASDAQ: TSLA | TSLA Price Prediction) and Google (NASDAQ: GOOGL) both reported Q1 FY2026 earnings that sharpened the autonomy debate in opposite directions. Tesla leaned on a global fleet streaming video into its…
Tesla is burning through cash, missing earnings estimates, and trading at a valuation that stretches belief, yet one wild card in its portfolio could rewrite the entire story for 2027.
Tesla (NASDAQ:TSLA | TSLA Price Prediction) and Ford (NYSE:F) closed 2025 with results that crystallize their diverging futures. Tesla reported fourth quarter earnings leaning into autonomy and AI while Ford showed a massive EV…