Prediction: Tesla’s Next Act Could Be Its Most Important Yet
Tesla is trading near its highest valuation in years while earnings are under serious pressure, and the gap between what the stock promises and what it delivers right now has never been wider. Whether Robotaxi and Optimus close that gap…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
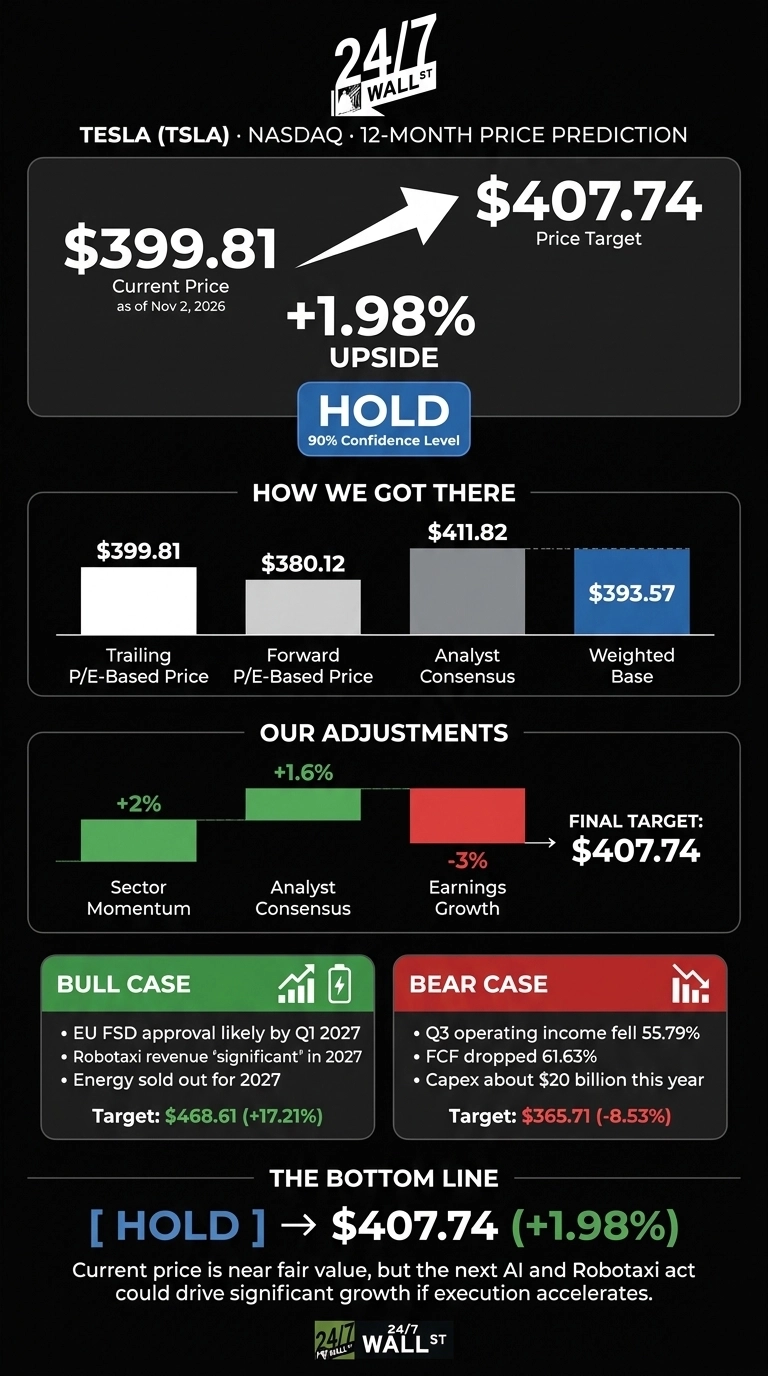
The price target from 24/7 Wall St. for Tesla (NASDAQ:TSLA | TSLA Price Prediction) is $407.74 over the next 12 months. Against a model reference price of $399.81, that works out to 1.98% upside and a hold rating.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $399.81 |
| 24/7 Wall St. Price Target | $407.74 |
| Upside/Downside | 1.98% |
| Recommendation | HOLD |
| Confidence Level | 90% |

Our model has high confidence in a simple read: Tesla trades close to fair value. Its next act (Robotaxi, Optimus, energy storage and in-house chips) is real and moving faster, but current earnings don’t yet pay for a $1.617T market cap.
Monday’s intraday move to $409.23 puts shares slightly above our target, so the remaining upside depends on Tesla performing.

Why We Could Be Wrong
Tesla is one of the most divisive stocks in the market. Two catalysts could make our model look too conservative: EU-wide FSD approval, which Elon Musk said he “would be surprised if it takes longer than Q1,” and Robotaxi revenue becoming “a significant part of our revenue and profitability in ’27.”
Treat our target as one datapoint among many. The bull case below lays out the upside in full.
A 15% Rally Since Q3 Puts Tesla Back in the Spotlight
Shares rose 9.94% over the past week and 15.34% since September 30, but they are still down 9% year to date. The stock trades between a 52-week low of $297.38 and a high of $498.83.
Morningstar (NASDAQ:MORN) just raised its fair value estimates for Tesla and SpaceX, and Reuters reported that Musk will get no salary unless Tesla hits milestones (November 2026 headlines).
Q3 revenue of $28.05B came in slightly above estimates. Non-GAAP EPS of $0.48 beat the $0.4511 consensus. Paid FSD subscriptions reached 1.74M, up from 1.04M a year ago, and management said it ended the quarter with its “highest backlog in four years.”
Why Bulls See $468 and Beyond
Tesla reaches $468.61 in the bull scenario, a 17.21% gain. Cumulative unsupervised Robotaxi miles grew 8x quarter over quarter, and the CFO said Robotaxi revenue is likely to be “a big deal by Q3 or Q4 of next year.”
Energy is “almost sold out of all Megapacks for 2027,” and Optimus customer deliveries are targeted for late next year. Among analysts, 19 rate the stock Buy or Strong Buy, while 4 rate it Sell or Strong Sell.

Spending Pressure Is the Risk to Watch
Our bear scenario points to $365.71. Q3 operating income fell 55.79% and free cash flow dropped 61.63%. In Q2, EPS missed estimates by 38.51%. Capex guidance is about $20 billion this year, and Terafab will need “tens of billions” more.
Much of the margin pressure came from R&D, which rose to $2.76B from $1.63B. That is spending on future growth, and the $45.45B cash balance can cover it.
How Tesla Compares to Ford and NVIDIA
Ford Motor Company (NYSE:F) is the U.S. legacy-auto comparison. Ford trades at roughly 4x free cash flow, compared with Tesla’s 254x. Ford’s EV unit still expects losses of about $4 billion this year, which makes Tesla’s profitable EV business look far stronger.
NVIDIA (NASDAQ:NVDA) competes with Tesla on autonomy and humanoid platforms through DRIVE Hyperion and GR00T. It earns AI-level margins at a trailing P/E of about 41.
| Company | Trailing P/E | Gross Margin | Operating Margin |
|---|---|---|---|
| Tesla | 417 | 18.03% | 4.59% |
| Ford | Negative | 12.2% | 1.4% |
| NVIDIA | 41 | 71.1% | 60.4% |
Next to these peers, Tesla’s multiple already assumes it succeeds in AI. That makes our target look reasonable.
What Could Move Our Hold Rating as the AI Payoff Builds
The 24/7 Wall St. price target of $407.74 comes with a hold rating and 90% confidence. What tips the balance is falling earnings set against a business that is speeding up.
The case gets stronger if Robotaxi revenue shows up by Q2 2027 and FSD approval in Europe lands on schedule. It gets weaker if opex keeps outpacing revenue with no new markets opening up.
Tesla Price Prediction 2026-2030
| Year | 24/7 Wall St. Price Target | Bull | Bear |
|---|---|---|---|
| 2026 (12-month) | $407.74 | $468.61 | $365.71 |
| 2027 | $416.50 | $468.15 | $372.84 |
| 2028 | $405.91 | $502.81 | $367.99 |
| 2029 | $452.08 | $543.78 | $369.70 |
| 2030 | $468.19 | $577.33 | $372.13 |
Tesla would need to keep performing its current strategy for these projections to hold. Big moves could come from how quickly Robotaxi scales and what the Terafab capital bill turns out to be.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.