Tesla’s Biggest Opportunity May Have Little to Do With Electric Cars
Investors keep debating Tesla's car margins while a completely different business quietly rewrites the company's growth story. The real question is whether the market is pricing the wrong Tesla entirely.

Our 24/7 Wall St. price target for Tesla (NASDAQ:TSLA | TSLA Price Prediction) is $405.69. That implies 8.12% upside from Tuesday’s close of $375.23, and our model rates the stock a buy.
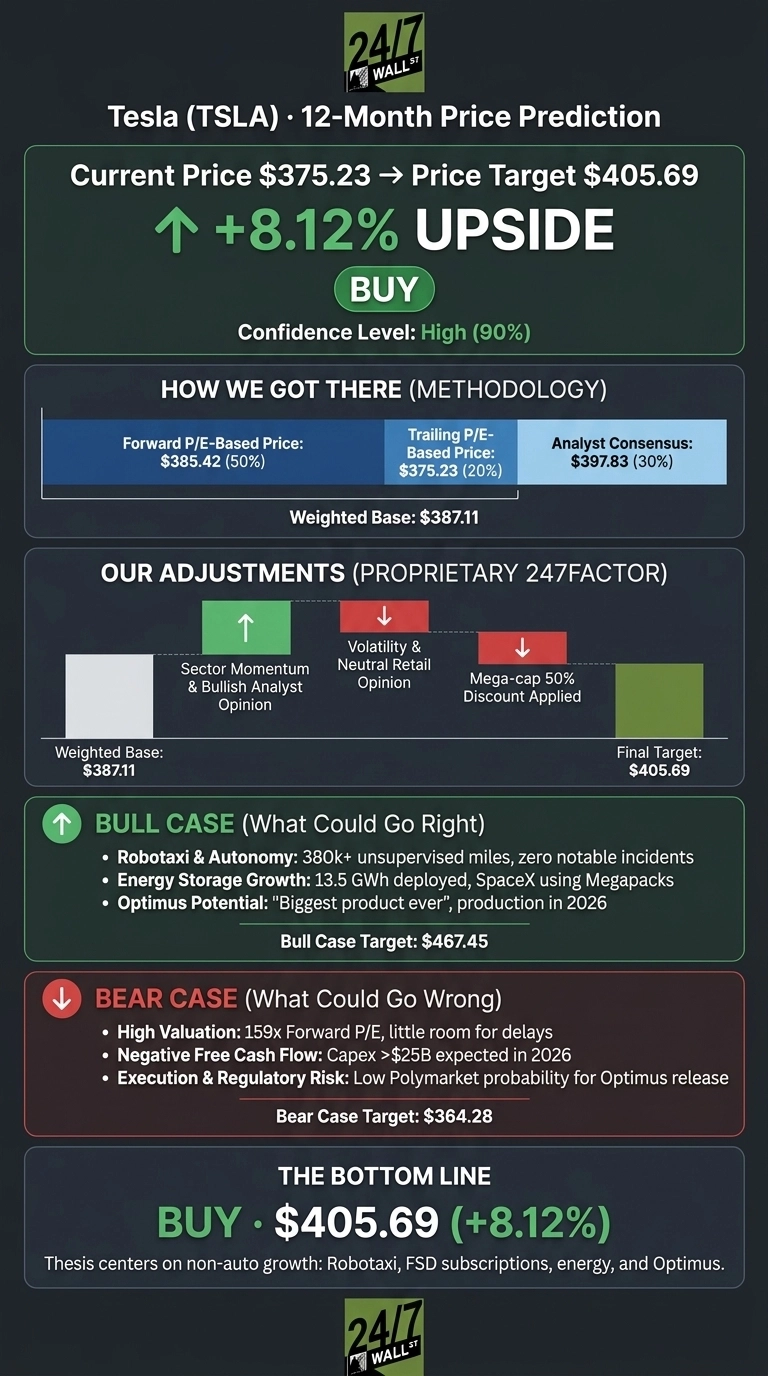
| Metric | Value |
|---|---|
| Current Price | $375.23 |
| Price Target from 24/7 Wall St. | $405.69 |
| Upside/Downside | 8.12% |
| Recommendation | BUY |
| Confidence Level | 90% |

We rate our confidence as high. This morning shares traded at $367.79, down 1.98%, as investors position ahead of third-quarter earnings.
My thesis centers on the businesses outside vehicle sales: Robotaxi, Full Self-Driving (FSD) subscriptions, energy storage and the Optimus humanoid robot. The market still prices Tesla largely on automotive margins, and that gap is the opportunity.
Record Revenue Meets a Massive Spending Surge
Tesla is down 3.39% over the past week, up 0.64% over the past month and down 18.22% year to date. Over the past year it has traded between a low of $297.38 and a high of $498.83.
Second-quarter revenue rose 25.52% to $28.24 billion, beating estimates. Non-GAAP EPS of $0.33 missed the $0.5367 estimate as operating margin narrowed to 1.4%. Capex of $5.789 billion pushed free cash flow to -$1.092 billion.
The non-auto numbers looked much stronger. Active FSD subscriptions rose 56% to 1.48 million, Services and Other revenue grew 50%, and storage installations reached 13.5 GWh.
Why Bulls See a Path to $467
The bull case reaches $467.45. Autonomy drives it. Tesla has logged “more than 380,000 miles of unsupervised Robotaxi” with “zero notable incidents.” Elon Musk said some customers are “buying Tesla full self-driving with a car attached.”
Energy adds a second leg: SpaceX buys Megapacks to smooth data center power swings. Musk also called Optimus “the biggest product ever.”
Analysts hold 19 Buy ratings against 4 Sells, with a consensus target of $397.83. Simon Erickson of 7investing built a model valuing Tesla at $700/share if Robotaxi works out.

What Could Go Wrong With the AI Pivot
Our bear case is $364.28. Management expects 2026 capex of “more than $25 billion”, so negative free cash flow could remain. At 159 times forward earnings, the stock has little room for delays. Polymarket traders price only a 0.073 probability that Optimus is released by December 31, 2026.
Some of the pressure has reasons. A warranty true-up of about $240 million weighed on energy margins. Operating expenses rose 47% on AI, R&D and pre-production costs, which is spending aimed at future revenue. Net income, however, included a $1 billion SpaceX mark-to-market gain.

How Tesla Compares to NVIDIA and Uber
The clearest public example of monetized AI compute is NVIDIA (NASDAQ:NVDA), the business Tesla is building with its AI chips and Austin fab. NVIDIA’s latest quarterly revenue rose 105.85%, yet it carries a much lower earnings multiple than Tesla. Tesla’s AI premium is already in the price (we studied what the early signals of a monster tech winner looked like in a free Next Nvidia playbook).
Uber (NYSE:UBER) is building “the world’s largest platform for autonomous vehicles” on top of 3.9 billion quarterly trips. That makes it Tesla’s most direct competition for Robotaxi riders, a comparison Barron’s noted today.
| Company | Trailing P/E | Price/FCF |
|---|---|---|
| Tesla | 347 | 238.26 |
| NVIDIA | 46 | 57.08 |
| Uber | 14 | 14.92 |
Compared with these peers, Tesla trades at a steep premium. Against that background, a target with single-digit upside looks reasonable.
Autonomy Tips the Scale Toward a Buy
My 24/7 Wall St. price target of $405.69 carries a buy rating with 90% confidence. FSD subscription growth tips the scale because it turns the fleet into recurring software revenue.
The thesis improves if Robotaxi keeps expanding and third-quarter results show capex turning into Services and energy growth. The case loses ground if free cash flow stays negative while autonomy revenue fails to speed up. For now, the non-auto story supports our bullish target.
Tesla Price Prediction 2026-2030
Looking further ahead, here is where our model projects Tesla could trade, assuming current growth trends remain.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $405.69 |
| 2027 | $427.93 |
| 2028 | $444.16 |
| 2029 | $468.94 |
| 2030 | $504.95 |
These projections assume Tesla keeps executing on its present plan. A statewide Robotaxi launch could push results well above these figures, while a long capex cycle with weak returns is the biggest downside risk.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.