Meta Heads Into Earnings With 29% Upside on Our Model
Meta walks into earnings with its ad engine still accelerating and a capex bill that rattles even the bulls. Our model lands on a price target Wall Street has not caught up to yet, and the confidence level behind it…

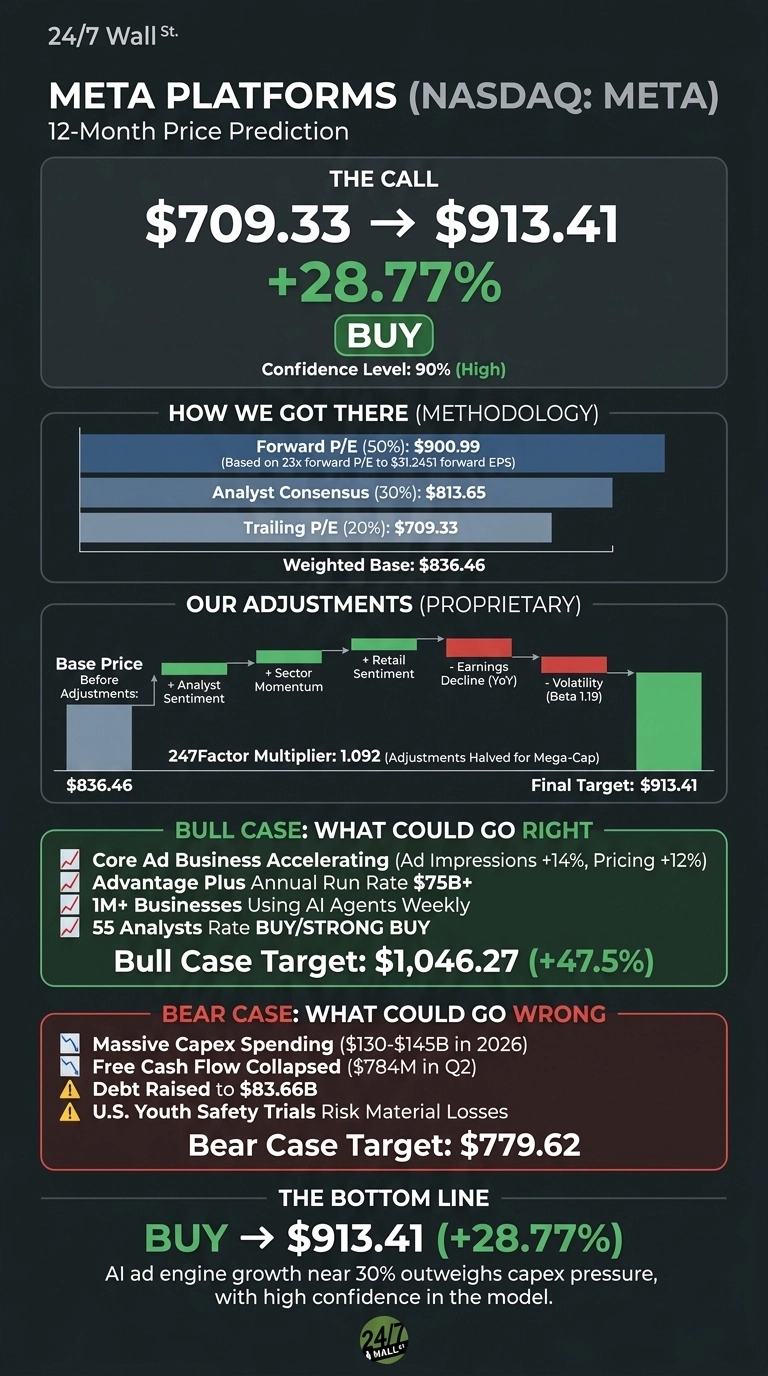
Meta Platforms (NASDAQ:META | META Price Prediction) is scheduled to report third-quarter results on October 21 after the close. Shares closed at $709.33. The 24/7 Wall St. price target for Meta is $913.41 over the next 12 months.
| Metric | Value |
|---|---|
| Current Price | $709.33 |
| Price Target from 24/7 Wall St. | $913.41 |
| Upside/Downside | 28.77% |
| Model Rating | BUY |
| Confidence Level | 90% |

Our model has high confidence in this call. Meta’s ad engine is still growing at close to 30% a year, and that growth matters more to the model than the margin hit from AI spending. The upside is about twice what Wall Street’s consensus target implies.
Meta Shares Recover After a Second-Quarter EPS Miss
Over the past week Meta slipped 1.3%, including a 3.72% drop on Friday. Shares are up 5.42% over the past month, roughly 6.7% over three months and 7.72% year to date. That leaves the stock about 9% below its 52-week high of $779.82.
Second-quarter revenue rose 27.96% to $60.80 billion, ahead of the $60.29 billion estimate. EPS came in at $6.18, short of the $7.22 consensus. That miss ended a six-quarter run of EPS beats. For the third quarter, management guided revenue to $61 to $64 billion.

Why Bulls See $1,046 Within Reach
Meta’s core ad business is still speeding up. In Q2, ad impressions rose 14% and the average price per ad climbed 12%. Advantage Plus, Meta’s automated ad product, has passed a $75 billion annual revenue run rate. More than 1 million businesses now use Meta’s AI business agents every week.
Zuckerberg told analysts, “The opportunity in front of us is massive.” Of the analysts covering the stock, 55 rate it a buy or strong buy, with their consensus target at $813.65. Our bull case reaches $1,046.27, a gain of 47.5%.

Capex and Courtrooms Could Cap the Upside
Meta plans to spend $130 to $145 billion on capital projects in 2026. Q2 free cash flow fell to $784 million from $8.55 billion, and long-term debt rose to $83.66 billion. That expansion has to be powered, cooled, and networked by someone, and we highlighted seven suppliers riding exactly that wave in a free AI infrastructure report.
Management has also warned that U.S. trials over youth safety could lead to material losses. One offsetting point: $2.40 billion in legal charges and $1.18 billion in severance hit the quarter, and both are one-time costs. Our bear case is $779.62, which is still above today’s price.

Meta Costs More Than Alphabet but Earns Higher Margins
The main rival to Meta for digital ad budgets is Alphabet (NASDAQ:GOOGL). Those earnings trade at 15x, but they include $99 billion in unrealized gains on equity holdings. On free cash flow, Alphabet costs 57x versus 34x for Meta.
Snap (NYSE:SNAP) competes with Meta for younger users and faces similar youth-safety lawsuits. Its revenue grew 18.9%, but its operating margin is negative. Taken together, the peer comparison makes our target look reasonable.
| Company | P/FCF | Operating Margin |
|---|---|---|
| Meta | 34x | 41.44% |
| Alphabet | 57x | 32.1% |
| Snap | 20x | -9.0% |
Meta’s AI Ad Engine Is Strong Enough to Justify Our Target
The 24/7 Wall St. price target is $913.41, with a buy rating at 90% confidence. Ad revenue growth near 30% is what tips the balance, more than offsetting the pressure from capex.
My view gets stronger if Q3 revenue comes in near the top of guidance and costs steady. I would turn more cautious if capex plans for 2027 rise again or the youth-safety trials go badly. On balance, the model sees more upside than risk.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $913.41 |
| 2027 | $1,064.13 |
| 2028 | $1,260.38 |
| 2029 | $1,393.68 |
| 2030 | $1,472.51 |
These projections assume Meta keeps executing on its current AI strategy. Turning business agents into a real revenue line would drive results higher, while sustained legal losses would pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.