Why Meta Could Keep Surprising Wall Street
Meta has clawed back nearly 20% in a single month, but the real question is whether the AI event on the horizon justifies pushing the stock even higher against a capex bill that crushed free cash flow by 90%.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
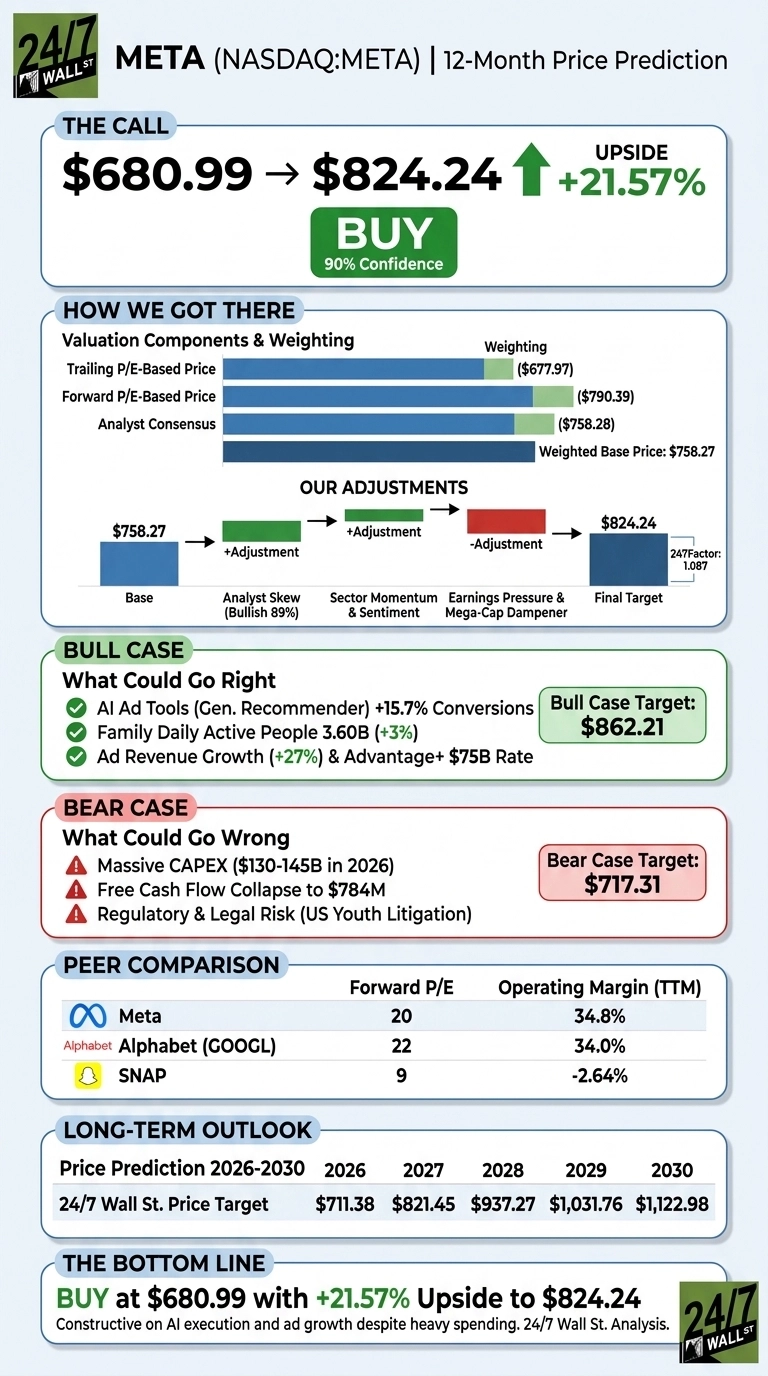
Meta (NASDAQ:META | META Price Prediction) has spent 2026 climbing back from a spring swoon, and our model thinks the recovery still has room to run. The 24/7 Wall St. price target for Meta is $824.24, implying 21.57% upside from the current price of $680.99. That translates to a buy rating with a 90% confidence reading, one of the higher conviction scores in our mega-cap coverage.
| Metric | Value |
|---|---|
| Current Price | $680.99 |
| 24/7 Wall St. Price Target | $824.24 |
| Upside | 21.57% |
| Recommendation | BUY |
| Confidence Level | 90% |

A Sharp Snapback Into Meta’s Connect Event
Meta shares have rallied 19.69% over the past month and 4.18% in the past week, clawing back losses that had the stock down as low as $568.97 in August. Year to date the stock is up 3.34%, still 4% off its 52-week high of $788.22.
The rebound is being fueled by AI enthusiasm ahead of Meta’s Connect event and what Barron’s has called potentially the biggest AI launch since ChatGPT with Meta Muse. That optimism is layered on top of a Q2 2026 report where revenue of $60.8 billion grew 28%, even as diluted EPS of $6.18 missed the $7.2214 consensus.

Why Bulls See a Breakout Ahead
The bull case starts with the ad engine. Family of Apps ad revenue hit $59.4 billion in Q2, with ad impressions up 14% and price per ad up 12%. Meta’s Advantage Plus solutions now run at a $75 billion annual revenue run rate, and generative recommenders delivered a 15.7% uplift in conversions on Facebook in early tests.
Add over 1 million businesses using Meta business agents weekly and a 60% increase in daily Meta AI users, and the enterprise flywheel is starting to spin. In the bull scenario our model reaches $862.21, and the Street’s top analyst view sits at $758.28 before Connect updates hit.

What Could Go Wrong
The bear case is the capex bill. Meta guided 2026 capital expenditures to $130 to $145 billion and total expenses to $165 to $169 billion. Q2 free cash flow collapsed to $784 million from $8.55 billion a year earlier, and long-term debt now sits at $83.7 billion. Regulatory risk from US youth litigation is real.
The counterfactual: Q2’s operating margin compression to 31% was largely driven by $2.4 billion in legal charges and $1.2 billion in severance. Excluding those, operating income would have grown 9% year over year. Our bear scenario still lands at $717.31, above today’s price.
How Meta Compares to Alphabet and Snap
Alphabet (NASDAQ:GOOGL) is the direct AI-plus-ads peer. Alphabet trades at a trailing P/E of 17 and a forward P/E of 22, versus Meta’s trailing 25 and forward 20. Meta looks cheaper on forward earnings despite similar ad exposure, which supports our target.
Snap (NYSE:SNAP) offers a scale contrast. Snap’s $6.35 billion in TTM revenue is a rounding error against Meta’s $228.25 billion, and Snap’s -2.64% operating margin underscores how much operating leverage Meta enjoys at 34.8%. The peer set makes our 24/7 Wall St. price target look reasonable.
| Company | Forward P/E | Operating Margin TTM |
|---|---|---|
| Meta | 20 | 34.8% |
| Alphabet | 22 | 34.0% |
| Snap | 9 | -2.64% |
Bottom Line on Meta’s Setup
Our model maintains its buy rating. Our 24/7 Wall St. price target of $824.24 and 90% confidence rest on an ad business growing 27% while trading at a forward multiple below Alphabet’s.
The setup looks constructive if Connect delivers a credible Meta AI monetization roadmap. The thesis weakens if 2027 capex guidance blows past the current $130 to $145 billion range without a corresponding revenue signal.
Looking further ahead, here is where our model projects Meta could trade, assuming current growth trajectories and margin recovery hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $711.38 |
| 2027 | $821.45 |
| 2028 | $937.27 |
| 2029 | $1,031.76 |
| 2030 | $1,122.98 |
These projections assume Meta continues executing on its AI infrastructure buildout and stabilizes free cash flow. All that spending has to be powered, cooled, and networked by somebody, and we profiled seven of those suppliers in a free report on the picks-and-shovels side of the AI boom. Significant upside or downside could result from Meta AI monetization surprises or a step-change in youth-safety regulation.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.