GE Aerospace Slipped After Strong Earnings: Is It Still a Great Stock?
GE Aerospace beat estimates for the eighth straight quarter, raised its guidance, and watched its stock fall anyway. Whether that drop is an opportunity or a warning depends on a valuation trap that bulls and bears are both watching closely.

GE Aerospace (NYSE:GE | GE Price Prediction) reported a beat-and-raise third quarter on Tuesday, October 20, and the stock has fallen since. Shares traded at $294.73 in premarket trading on October 22, 2026. They are down 4.0% over the past week and 7.5% over the past month. The stock has also gained 366.1% over the past half-decade, and that run may already reflect a lot of the optimism about the business.
A Quarter That Left Bears Little to Work With
Adjusted EPS came in at $2.25, up 36% from a year earlier. Revenue reached $14.118 billion, up 18%. GE beat analyst estimates for the eighth quarter in a row. Total orders rose 49%, and commercial services orders climbed 23%. The backlog now tops $170 billion. CFO Rahul Ghai said GE raised its 2026 EPS guidance to $8.00 to $8.10. Ghai also lifted free cash flow guidance to $9.1 billion to $9.4 billion.

Chair and CEO Larry Culp described the demand picture on the earnings call:
Given airframer order books are full through the end of the decade, along with strong growth in aftermarket and defense, we are continuing to invest to ensure timely delivery for our customers.

Boeing’s MAX 10 Approval Grows GE’s Fleet
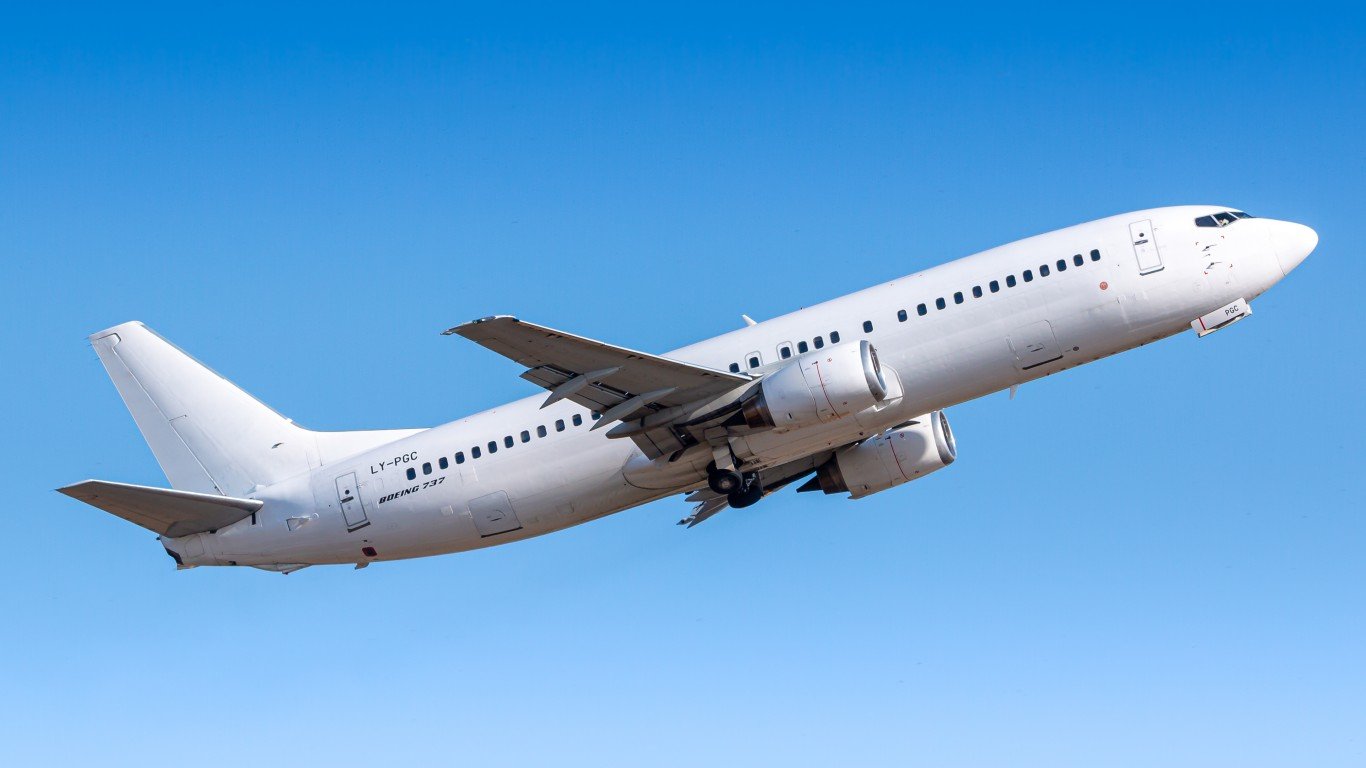
On October 20, the FAA certified the 737-10, the largest jet in the MAX family of Boeing (NYSE:BA). The hosts of The Investor’s Podcast point out that the LEAP is the only engine on the MAX family. That means every MAX delivery adds to GE’s installed base and to its future service revenue. Transportation Secretary Sean Duffy said, “This has been almost a ten-year process getting to this day of certification, which by the way, is huge.” Henry Epp of Marketplace Morning Report said, “major airlines have ordered more than 1,400 of them.” GE has also agreed to supply more than 300 LEAP-1B engines for Turkish Airlines’ MAX fleet.
However, GE also said on the call that it now assumes fewer GE9X engines for Boeing this year. The company is working toward FAA certification of an upgraded mid-seal by the end of 2026.
A Rival Sees the Same Aftermarket Demand
RTX (NYSE:RTX) has Pratt & Whitney, which competes with GE’s LEAP to power Airbus’s main narrow-body jet family. RTX CEO Chris Calio said on October 20, “There’s the concern around jet fuel and airline health and pricing, but the demand is still there. We’ve seen that in our parts and repairs orders.”
Ghai made a similar point on GE’s call: “Even with strong revenue growth, spare parts delinquency (backlog of unfilled parts orders) increased sequentially, reflecting strong underlying demand.”
Bulls and Bears Both Have Ammunition
On an episode of The Investor’s Podcast, the hosts made the bull case around a razor-and-blade model: each engine earns back about 3.5 times its original revenue in services, services account for more than 70% of revenue, and the services segment earns a 27% margin while new engines sell at roughly breakeven. The hosts added, “On the planes that matter most, GE has roughly three quarters of the market.”
The bear case rests on strength and operating leverage. The podcast hosts said some LEAP engines needed their first overhaul after a year and a half instead of the expected five years. They also noted that in 2020, GE Aviation revenue fell 33% and profit fell 82%.
GE’s CEO spoke to the strength question on the call: “That’s why we were so pleased to see the LEAP AOG number down to near zero since the summertime.” AOG means aircraft on ground, or grounded planes.
The Investor’s Podcast hosts ended on valuation: “Only if you stay in the 35 to 40 times earnings range will you still be able to get a good return on GE Aerospace. The exit multiple is basically everything here.”
A Pullback Rule for Strong Stocks
Jim Cramer described a framework on Mad Money on October 21: “The New High List is not a shopping list. It’s an inspiration list.” He said the ideal pullback is 5% to 8%, while a drop of more than 8% suggests something may be going wrong. GE’s one-month fall totals 7.5%, right at the edge of that range. (We put ten rules for buying strong stocks on pullbacks in a free guide here: The Breakout Buyer’s Rulebook.) Upcoming milestones include the GE9X mid-seal certification and GE’s full 2027 guidance, due in January.


Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.