Oklo Could Have a Huge Opportunity as Demand for Advanced Nuclear Energy Grows
Oklo has shed more than 60% of its value this year and sits near a 52-week low, yet its customer pipeline spans gigawatts and its regulatory path just cleared a major hurdle. Whether that combination makes it a bargain or…


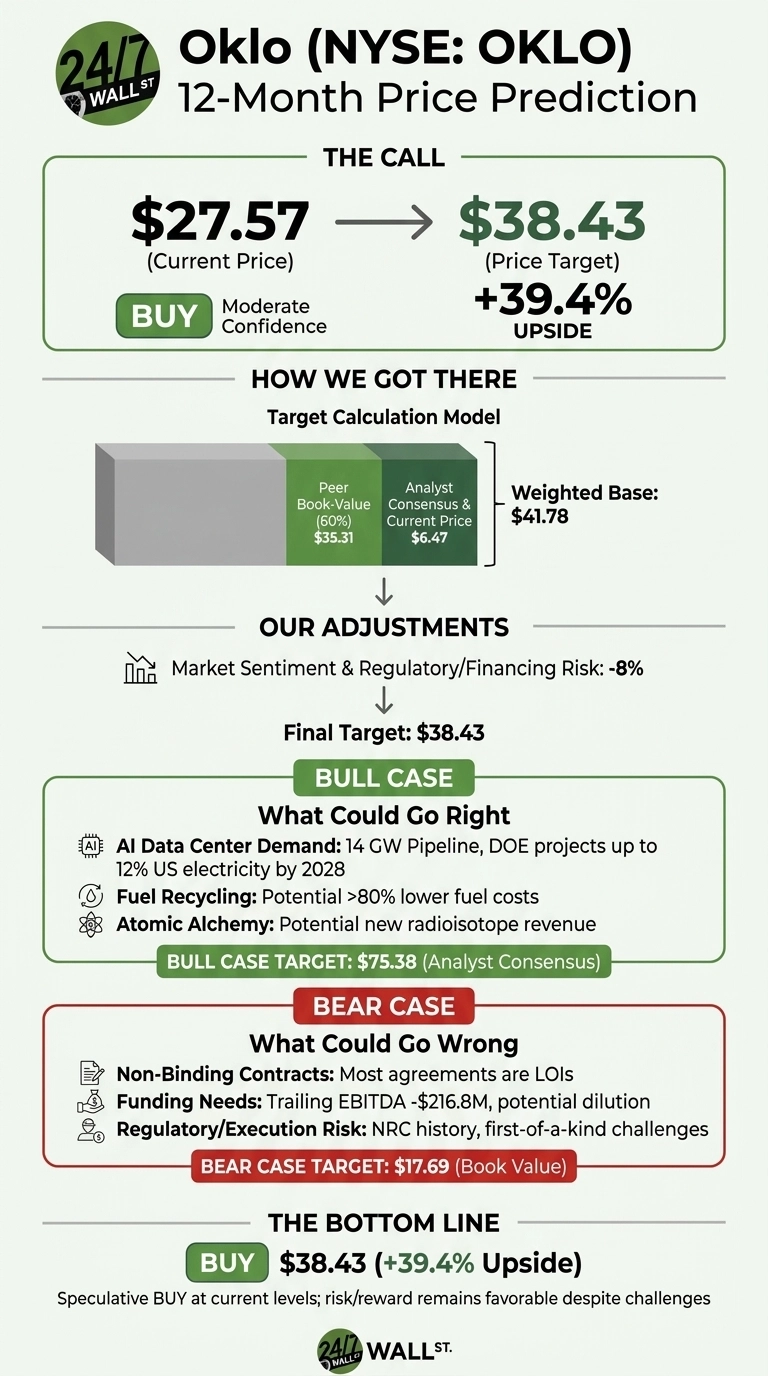
The 24/7 Wall St. price target for Oklo (NYSE:OKLO | OKLO Price Prediction) is $38.43. That means 39.4% upside from the current price of $27.57. Our model rates the stock a buy with moderate confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $27.57 |
| 24/7 Wall St. Price Target | $38.43 |
| Upside/Downside | 39.4% |
| Recommendation | BUY |
| Confidence Level | 55% |
Oklo has given up its AI-power premium, but the core thesis still holds. It has a 75 MW Aurora powerhouse design, a customer pipeline of about 14 GW, and a licensing path that picked up speed in 2026.
Shares trade just 2.8% above the 52-week low. We put confidence at 55% because Oklo still has no commercial revenue, so its value depends on reaching first power in late 2027 to early 2028.
A 61% Slide in 2026 Has Reset Expectations
Oklo fell 14.41% over the past week and 27.45% over the past month. Year to date, it is down 61.58%, and it sits 82.1% below its 52-week high of $154.45.
Barclays and Piper Sandler both cut their price targets this week (per CNN Markets). Over the trailing 12 months, revenue was $1.21 million and diluted EPS was -$0.94. Regulators did give Oklo one clear win this year.
In May 2026, the NRC approved the Principal Design Criteria topical report for Aurora, completing its review in less than half the traditional timeline.
Why Bulls See a Path Back to $75
Demand is the main driver. The Department of Energy projects that data centers could account for up to 12% of U.S. electricity demand by 2028 (we mapped five ways to play the nuclear restart, utilities and fuel included, in a free report).
Oklo’s pipeline includes a 12 GW master agreement with Switch running through 2044 and a 500 MW letter of intent with Equinix (NASDAQ:EQIX), which comes with a $25 million prepayment. On the March 2025 call, management said fuel recycling could lower fuel costs by over 80%. Atomic Alchemy also gives Oklo a possible second revenue stream from radioisotopes.
Analyst ratings stand at 6 Strong Buys, 9 Buys, 9 Holds and 1 Strong Sell. The bull case uses the consensus target of $75.38, which would mean 173.4% upside.

What Could Keep Oklo Pinned Near Its Lows
Management has said the Switch deal is not a firm power purchase agreement, and most of the other agreements are non-binding letters of intent. The NRC denied Oklo’s original Aurora application. Trailing EBITDA was -$216.8 million, so Oklo will likely need to raise more money, which could dilute shareholders.
Book value of $17.69, or 35.8% downside, anchors the bear case. In fairness, much of that spending pays for procurement, licensing and fuel recycling ahead of the first INL plant. Bulls would argue that investment is what makes future revenue possible.
How Oklo Compares to NuScale Power and Centrus Energy
NuScale Power is Oklo’s closest direct SMR competitor and holds the industry’s only NRC design certification. NuScale trades near 2.0x book value, compared with 2.2x for Oklo. Oklo’s premium is modest, which supports our book-value anchor.
Centrus Energy (NYSE:LEU) supplies Oklo’s HALEU fuel and has explored a deconversion joint venture with Oklo. Centrus is already profitable. Its Q2 2026 revenue was $176.10 million, and adjusted EPS of $1.77 came in above the $0.92 estimate.
Even so, Centrus is worth less than Oklo, which suggests our target is reasonable and the consensus target is aggressive.
| Company | Market Cap | Recent EPS |
|---|---|---|
| Oklo | $5.13 billion | -$0.94 (TTM) |
| NuScale Power | $2.30 billion | -$0.13 (Q2 2026) |
| Centrus Energy | $2.19 billion | $1.77 (Q2 2026, adjusted) |
Our Verdict: A Speculative Buy Near the 52-Week Low
The 24/7 Wall St. price target of $38.43 supports a buy rating at 55% confidence. The stock has already priced in a lot of disappointment while the regulatory picture has improved.
The case strengthens if Oklo turns its letters of intent into binding contracts and keeps its combined license review on schedule. The thesis weakens if the first-power date slips or a large dilutive raise comes. At these levels, our model finds the potential reward as outweighing the risk.

Looking further out, here is where the 24/7 Wall St. price target model projects Oklo could trade, assuming current growth trends and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $30.33 |
| 2027 | $38.43 |
| 2028 | $51.88 |
| 2029 | $64.85 |
| 2030 | $77.82 |
Oklo’s results depend on the company continuing its current strategy. A licensing delay, fuel shortage or dilutive financing could push results well below these figures, while the Switch installations could drive meaningful upside.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.