Rambus Could Be an Overlooked Winner in the AI Memory Boom
Rambus sits 46% below its 52-week high despite posting record product revenue, and a major AI hyperscaler just handed it a design win that most investors have not noticed yet.

Rambus (NASDAQ:RMBS | RMBS Price Prediction) trades at $93.74 in midday trading. A 24/7 Wall St. price target of $120.50 over the next 12 months implies 28.5% upside. The stock earns a buy rating from the model with high confidence.
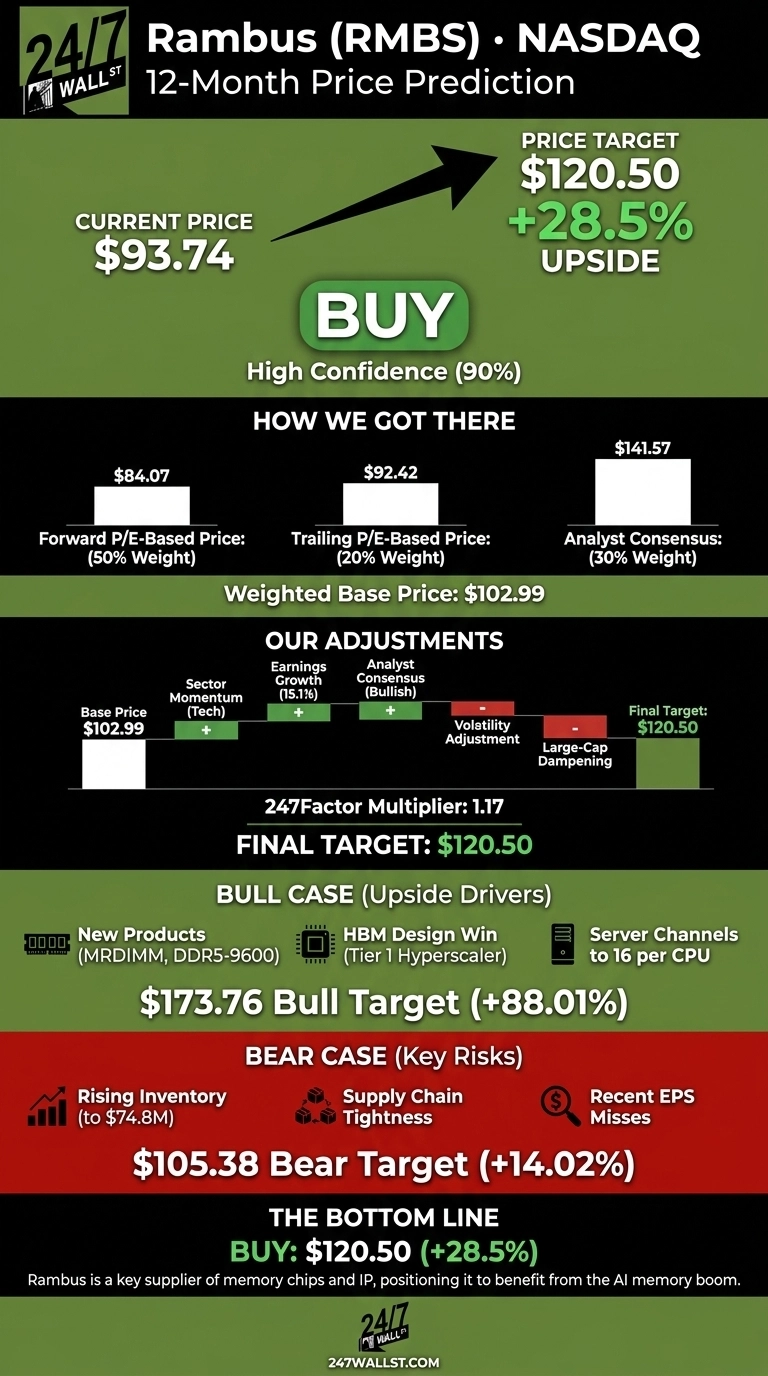
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $93.74 |
| Price Target from 24/7 Wall St. | $120.50 |
| Upside | 28.5% |
| Recommendation | BUY |
| Confidence Level | 90% |

Rambus supplies the DDR5 registered clock drivers that sit between processors and memory on server modules, and it licenses HBM4E controller and PCIe 7 switch IP to AI chip designers.
As inference and agentic workloads push more memory channels per CPU, Rambus collects on each one. Investors get that exposure at 26x forward earnings, ahead of third-quarter results due October 26.
Record Revenue, Yet Shares Sit 46% Below the High
The stock fell 4.51% over the past week but gained 7.01% over the past month. It is up 2.01% year to date. Shares traded at $132.48 in mid-June before falling to $81.41 in mid-September, leaving them 46.2% below the 52-week high of $174.10 and 20.3% above the low of $77.89.
The pullback came despite strong results. Second-quarter revenue reached $207.38 million (+20.4% YoY), beating the $198.30 million consensus. Non-GAAP EPS came in at $0.77 against a $0.715 estimate. Product revenue set a record at $99.15 million, and third-quarter guidance calls for revenue of $210 million to $216 million.

Why Bulls See $173 Ahead
Management expects new products to make up a mid-double-digit share of product revenue by the fourth quarter, up from low-double-digits in Q1. It expects MRDIMM to make a more material contribution in 2027 and the server market to move to 16 channels per CPU.
Rambus also secured an HBM design win with a Tier 1 U.S. hyperscaler and expects silicon IP to grow 10% to 15% a year. CEO Luc Seraphin said “the seeds we’ve planted in the last two years should manifest in 2027.”
Six analysts rate the stock a buy and two a hold, with a consensus target of $141.57. Shares could reach $173.76 in the bull case.

Supply Tightness and Inventory Are the Risks Worth Watching
Operating cash flow fell to $61.2 million (-35.1% YoY) as inventory rose to $74.8 million from $44.1 million at the end of 2025. Management describes this as strategic inventory built for coming product ramps while lead times lengthen, and it says it sees no customer stocking.
Supply tightness also caused a downgrade after Q1, and EPS has missed estimates in two of the last five quarters. Traders using the leveraged Corgi RMBS 2x Daily ETF (CBOE:RMBC) should know it resets daily, which amplifies these swings. Even so, our bear case of $105.38 stands above today’s price.

How Rambus Compares to Micron and Credo
Micron Technology (NASDAQ:MU) is both a DRAM customer and a pure-play comparison on the memory cycle. The stock changes hands at just 7x forward earnings with a beta of 2.23, a cyclical discount that Rambus’s royalty base helps it avoid.
Credo Technology (NASDAQ:CRDO) competes for the same connectivity spending in data centers built for AI and trades at 31x forward earnings with a beta of 3.25.
| Company | Forward P/E | Beta |
|---|---|---|
| Rambus | 26x | 1.85 |
| Micron | 7x | 2.23 |
| Credo | 31x | 3.25 |
Rambus’s multiple stands between the two peers, and its volatility is the lowest of the three. Against that background, the 24/7 Wall St. price target looks reasonable.
Rambus Earns a BUY Rating Ahead of Earnings
The 24/7 Wall St. price target of $120.50 carries a buy rating with 90% confidence. Record product revenue tips the scale, showing Rambus’s growth has held up while its share price has not.
I’d turn more constructive if third-quarter product revenue secured within the $110 million to $116 million guide. Caution would set in if inventory keeps rising without matching sales. For now, the risk-reward points higher.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $94.45 |
| 2027 | $120.50 |
| 2028 | $144.67 |
| 2029 | $169.59 |
| 2030 | $181.12 |
The projections depend on Rambus keeping pace with its DDR5 and IP roadmap. MRDIMM adoption or extended supply constraints could move results well above or below them.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.