Prediction: Rambus Could Benefit Every Time AI Gets Faster
Every time AI systems demand faster memory and tighter chip interconnects, one under-the-radar semiconductor company collects a toll. The question is whether the market has already priced in the opportunity or is still sleeping on it.

The 24/7 Wall St. price target for Rambus (NASDAQ:RMBS | RMBS Price Prediction) is $132.03 over the next 12 months. From today’s intraday price of $102.33, that works out to about 29% upside. The stock receives a buy rating with high conviction.
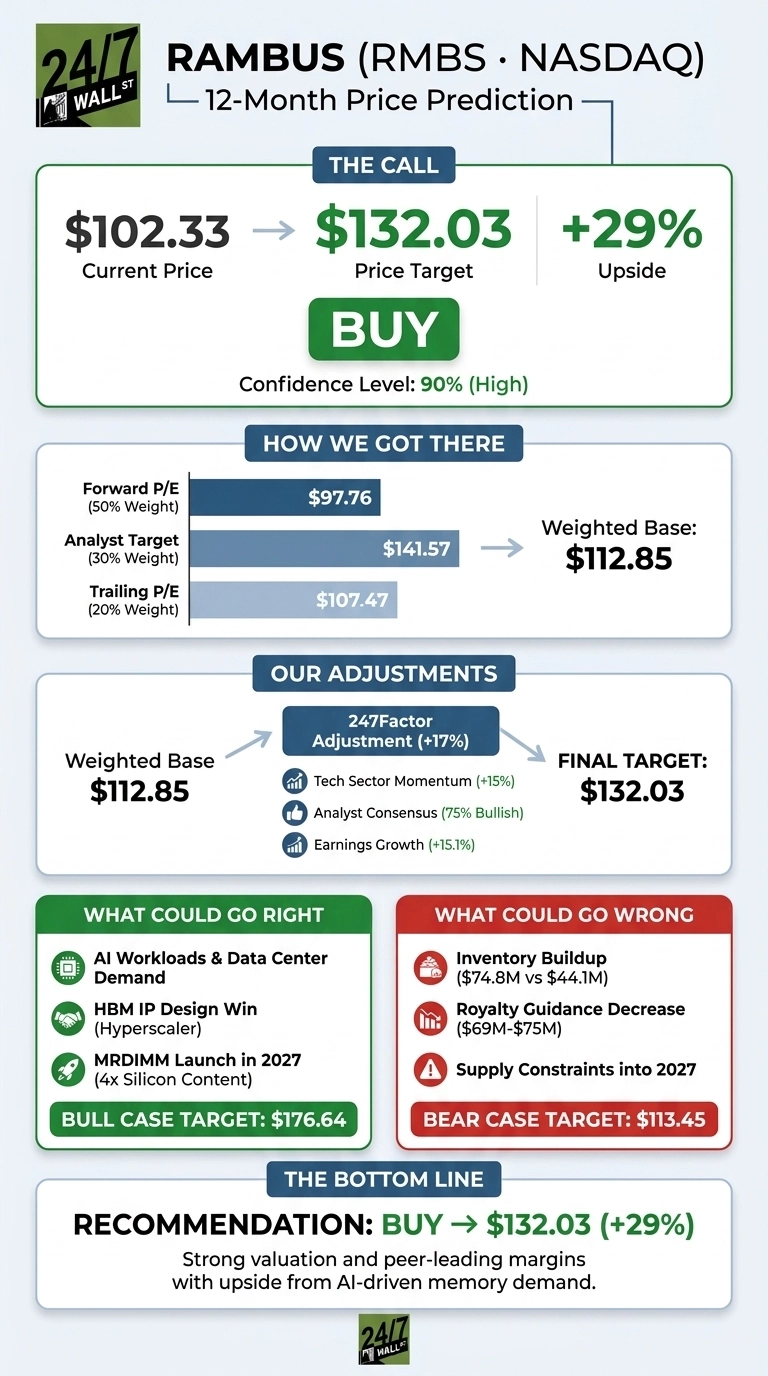

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $102.33 |
| Price Target from 24/7 Wall St. | $132.03 |
| Upside/Downside | 29.0% |
| Recommendation | BUY |
| Confidence Level | 90% |
Rambus makes the chips and licenses the IP that move data between processors and memory. Its lineup includes DDR5 clock drivers, HBM4E controller IP and PCIe 7 switch IP, so faster AI systems need more of what Rambus sells.
In June, our model rated the stock a sell with a $117.57 target after a big run. The pullback since then, along with better earnings, has reversed that call.
Down 4.78% Today, Up 16.75% in a Month
Shares are off 4.78% today and 8.61% over the past week. Even so, they are up 16.75% over the past month and 11.36% year to date. The stock sits about 41% below its 52-week high of $174.10 and about 31% above its low of $77.89.

Second-quarter revenue rose 20.43% to $207.38 million, ahead of the $198.30 million consensus. Non-GAAP EPS of $0.77 beat the $0.715 estimate, and product revenue hit a record $99.15 million. For the third quarter, Rambus guided to revenue of $210 million to $216 million.
Why Bulls See $176 Ahead
CEO Luc Seraphin said AI workloads are becoming “more diverse, more persistent, and more memory intensive.” Rambus also announced an HBM IP design win with a “Tier 1 US hyperscaler”.
Management expects MRDIMM, which has about four times the silicon content of a standard module, to contribute more significantly in 2027. The consensus target is $141.57, with 6 Buy ratings, 2 Holds and no Sells. Our bull case reaches $176.64.

Inventory and Royalty Swings Are the Risks to Watch
Inventory rose to $74.8 million from $44.1 million at the end of 2025. Operating cash flow fell 35.14%, and royalty guidance of $69 million to $75 million sits below the second quarter’s $84.26 million. Management also expects supply constraints to remain a factor into 2027.
Still, bulls would point out that the inventory is being built on purpose for product launches. As management put it, “We build strategic inventory for the products that we believe are going to contribute to our growth.”
Even the bear case comes in at $113.45. (If you want to see what the early signs of past monster chip winners looked like, we cataloged them in a free playbook here: The Next Nvidia Playbook.)
How Rambus Compares to Marvell and Synopsys
Marvell Technology (NASDAQ:MRVL) competes for the same AI data center connectivity spending. It trades at a forward P/E of 62x, with an operating margin of 16.7%.
Synopsys (NASDAQ:SNPS) is the closest match on silicon IP licensing and trades at 23x forward earnings.
| Company | Forward P/E | Operating Margin (TTM) |
|---|---|---|
| Rambus | 24x | 36.7% |
| Marvell | 62x | 16.7% |
| Synopsys | 23x | 14.5% |
Rambus trades at about the same multiple as Synopsys while receives more than twice its margin. That comparison makes the 24/7 Wall St. price target look reasonable, and arguably conservative.
Rambus Price Prediction 2026-2030
My 24/7 Wall St. price target is $132.03, with a buy rating and 90% confidence. What tips the scale for me is valuation: Rambus receives peer-leading margins at a forward multiple in the mid-20s.
Things look better if product revenue keeps growing by double digits and MRDIMM launches in 2027. Downside risks grow if royalties keep shrinking and inventory keeps piling up. For now, I think the setup favors the bulls.
Here is where our model projects Rambus to trade if growth trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $112.33 |
| 2027 | $134.19 |
| 2028 | $154.02 |
| 2029 | $167.00 |
| 2030 | $183.14 |
The estimates assume Rambus keeps executing on DDR5, MRDIMM and HBM IP. A faster hyperscaler launches could push results toward our 2030 bull case of $294.12, while a memory downturn would pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.