CoreWeave Jumped 16% After Earnings but Is Still Down 47% in a Year. Can the Rebound Last?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Shares of CoreWeave (NASDAQ:CRWV) were indicated at $56.30 in premarket trading, up 15.53% after a third-quarter report that eased fears about AI infrastructure spending. CoreWeave has a 24/7 Wall St. price target of $80.90. That implies 43.69% upside over a 12-month horizon.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $56.30 |
| Price Target from 24/7 Wall St. | $80.90 |
| Upside/Downside | 43.69% |
| Confidence Level | 60% |
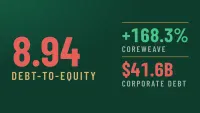
Our model gives the target moderate confidence. Revenue grew 168.27% in the quarter, and adjusted operating margin reached 10% a quarter ahead of plan. The balance sheet holds confidence back. Debt-to-equity is at 8.94, and GAAP losses keep getting bigger.
A Breakout Quarter Follows a Brutal Year
Before the jump, the stock had lost 31.41% over the past month. It is still down 46.69% over one year and 21.38% year to date. At the current price, shares sit about 59% below the 52-week high of $138.25.
Q3 revenue came in at $3.661 billion, beating the $3.541 billion consensus. GAAP EPS of -$1.27 also beat the -$1.5522 estimate. Full-year revenue guidance was raised to $13 billion to $13.3 billion, and backlog reached roughly $132.5 billion. MarketWatch reported that the results lifted AI stocks across the board as CoreWeave calmed Wall Street’s worst fears.

Rising Prices and GPU Renewals Point Bulls to $120
On the earnings call, the CEO said CoreWeave raised prices across its products by approximately 25% in July and by another 10% later in the quarter. Contracts on more than 130,000 GPUs expire in 2027. Management says renewing them at current prices could add approaching $4 billion of annual revenue with no new capital spending.
Qualified demand runs 10 times available capacity through 2027, and management expects adjusted net income to turn positive in the first half of 2028. If revenue reaches the high 2027 estimate of $31.46 billion and the stock gets a 1.75x sales multiple, the upside case reaches $119.98.
Debt Remains the Risk That Matters Most
The Q3 net loss came to $709 million, weighed down by $846 million of net interest expense. Capital spending of $37 billion to $39 billion this year means more debt. Over the past 30 days, analysts made 6 downward revisions to 2027 EPS and only 2 upward ones.
Bulls would point out that adjusted EBITDA hit $2.256 billion at a 62% margin. They would also note that the weighted average cost of debt fell to 7.9%. In our bear case, revenue lands at the low 2027 estimate of $21.1 billion and the stock trades at 0.6x sales, which implies $27.59.
CoreWeave Trades Below Nebius and Oracle on Sales
Nebius Group (NASDAQ:NBIS | NBIS Price Prediction) is the closest pure-play neocloud, meaning a company that rents out GPU computing power the way CoreWeave does. It is worth $29.53 billion while guiding to $3.0B to $3.4B in 2026 revenue.
Oracle (NYSE:ORCL) competes for the same AI training customers. Its cloud infrastructure revenue grew 121%, and it has $664 billion in contracted future revenue.
| Company | Forward P/E | Market Cap / Guided Revenue |
|---|---|---|
| CoreWeave | Negative earnings | 2.0x |
| Nebius | 29 | 9.2x |
| Oracle | 15 | 4.1x |
Both peers trade at a premium to CoreWeave’s revenue, which makes our 1.25x multiple look conservative. Part of that gap is gets. Oracle is profitable, and CoreWeave’s leverage is far higher than either rival’s.
CoreWeave’s $80.90 Target Hinges on Pricing Power
The 24/7 Wall St. price target of $80.90 has 60% confidence. The deciding factor is pricing power.
CoreWeave is charging more for the GPUs it already owns. The case gets stronger if 2027 renewals land as management expects. It gets weaker if financing costs rise or heavy use of the ATM program dilutes shareholders. At about 2.0x guided revenue, CoreWeave trades at a discount to both peers on sales.
Looking further ahead, these targets assume revenue growth slows over time and the sales multiple expands as profits come in.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $60.31 |
| 2027 | $80.90 |
| 2028 | $100.86 |
| 2029 | $141.20 |
| 2030 | $181.54 |
These projections assume the current share count, so dilution would lower them. A capacity glut or tighter credit markets could also push results far short of these levels.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.