Apple Just Passed Nvidia as the World’s Most Valuable Company on iPhone Duo Day
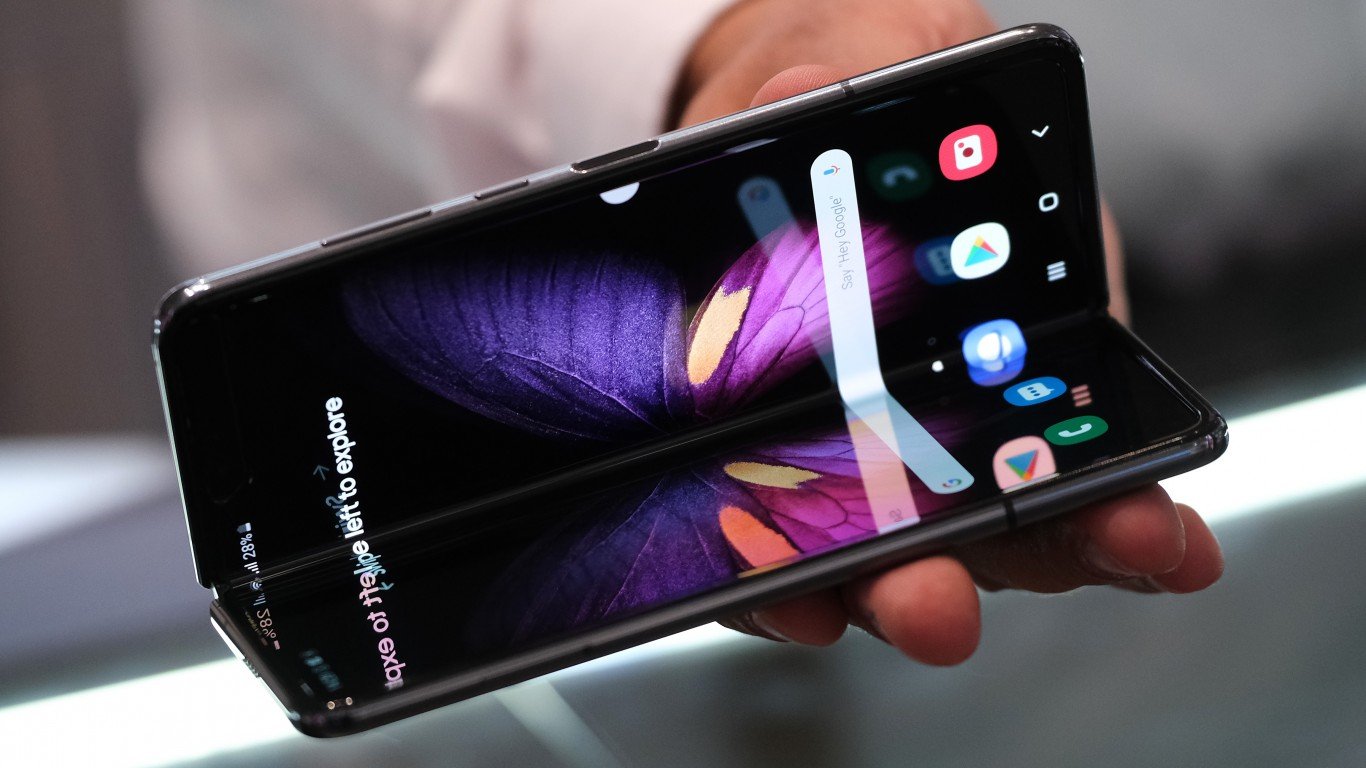
Apple's foldable iPhone Duo sold out in minutes and sent the stock to a record that briefly toppled Nvidia from the top of the global market cap rankings. Whether a supply-starved device cycle can justify that valuation is the question…

For a few hours on Friday, a phone maker was worth more than the company behind the AI boom. Shares of Apple (NASDAQ:AAPL | AAPL Price Prediction) touched a record intraday high of $351.73. That raised its value to about $5.1 trillion and briefly put it ahead of NVIDIA (NASDAQ:NVDA) on the day its foldable iPhone Duo reached stores.
Nvidia took the lead back by the close. Apple slid 0.14% to $347.73 ($5.074 trillion), and Nvidia fell 0.59% to $210.96 ($5.094 trillion), ending up about $20 billion ahead.
On Thursday, the gap was about $42 billion. What remains uncertain is whether a foldable cycle held back by limited supply justifies the same valuation as the AI chip leader, ahead of Apple’s report on November 2.

Two Opposite Businesses Now Carry the Same Price Tag
Apple sells devices plus the services built on them. Nvidia sells the data center systems behind AI.
| Lens | Apple | Nvidia |
|---|---|---|
| Latest quarterly revenue | $109.42 billion | $96.22 billion |
| Revenue growth | 16.4% | 105.8% |
| P/E | 45 | 42 |
| One-month move | +3.18% | -6.45% |
Nvidia is growing far faster at a lower multiple. The opposite one-month moves suggest some money is rotating from AI chips toward Apple, although one month is a short window.
Sold-Out Duos Prove Demand but Cap the Holiday Quarter
The Duo starts at $1,999 and tops out at $3,199. Preorders sold out almost immediately, and deliveries slid into late January. On eBay, sellers asked more than $4,000 for the base model.
Demand clearly tops supply. That shortage limits what Apple can book in the December quarter and drives some revenue into 2027. Even so, the higher entry price should raise the average iPhone selling price, which helps margins.

Beijing Scalpers Point to Real China Demand
In China, the Duo starts at nearly 16,000 yuan. Apple blocked walk-in purchases there on launch day and limited online orders to two per buyer. Scalpers in Beijing offered up to 3,000 yuan (about $448) above what buyers paid.
That premium matters in a market where Apple has faced tough local competition. It also gives John Ternus, CEO since September 1, a strong first major launch.
Apple’s July guidance for the September quarter called for 9%-11% revenue growth and a 47%-48% gross margin. That margin included about one percentage point from tariff refunds. Tim Cook, then CEO, described “a 100-year flood on the memory pricing,” and Apple has reluctantly raised prices.
You’d want to hear holiday guidance, Duo supply timing, and China commentary. Nvidia follows on November 18, after guiding to $108 billion in revenue for the quarter.


Apple’s Record Valuation Faces a Critical Test
Apple’s valuation looks extended at this record high. At 45 times earnings, the stock already prices in a Duo cycle that limited supply will spread across several quarters, while memory costs squeeze margins.
Nvidia offers faster growth at a lower multiple. Its data center revenue rose 117%, and management expects about 70% revenue growth in fiscal 2028 even with supply limits.
Nvidia has real risks, including no China data center compute revenue in its guidance and financing ties to AI labs. Still, Nvidia’s lower multiple looks more reasonable for that growth. If Apple shows easing Duo supply and steady margins on November 2, I would change my view.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.