The Hidden $496 Billion Catalyst Waiting to Ignite Amazon Stock on Oct. 29
Amazon (NASDAQ:AMZN | AMZN Price Prediction) reports third-quarter results Thursday, Oct. 29, after the bell. AWS has a $496 billion backlog, and I’ll be watching how fast that backlog turns into revenue. AWS Acceleration Meets a $220 Billion Spending Bill…

Amazon (NASDAQ:AMZN | AMZN Price Prediction) reports third-quarter results Thursday, Oct. 29, after the bell. AWS has a $496 billion backlog, and I’ll be watching how fast that backlog turns into revenue.

AWS Acceleration Meets a $220 Billion Spending Bill
Last quarter, revenue reached $200.61B, up 19.6% year over year, and operating income rose 43% to $27.46B. AWS grew 37% to $42.23B, its fastest pace in 18 quarters. GAAP EPS of $5.75 got a lift from a $53.4B pre-tax gain on Anthropic.
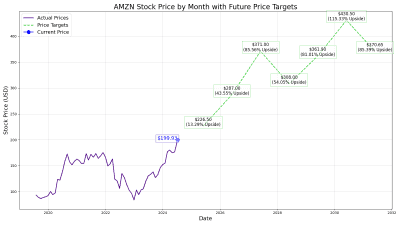
Management raised 2026 cash capex to roughly $220 billion, up from about $200 billion, citing higher memory costs. Q3 guidance calls for net sales of $197.0B to $202.0B and operating income of $22.5B to $26.5B. Prime Day moved into Q2, and FX is a roughly 80 bps drag. Shares sit at $248, up 7.44% year to date.
Consensus Points to Double-Digit Sales Growth
| Metric | Consensus | Prior Year | YoY Growth |
|---|---|---|---|
| Q3 EPS | $1.9579 | $1.95 | 0.4% |
| Q3 Revenue | $202.20B | $180.17B | 12.2% |
| FY2026 EPS | $12.9043 | $7.17 | 80.0% |
| FY2026 Revenue | $828.74B | $716.92B | 15.6% |

Last year’s Q3 EPS included $9.5 billion in pre-tax Anthropic gains, so the EPS comparison has noise.
Backlog Conversion and Margins Will Set the Tone
AWS reached a $169 billion annualized run rate after speeding up for a fifth straight quarter. Capacity is the constraint. CEO Andy Jassy said that even with the higher spending, “we will still not have enough capacity to meet all the demand we have in 2026.” Keep an eye on whether new data centers coming online keep growth climbing.
Margins come next. AWS margins expanded 650 basis points year over year, though CFO Brian Olsavsky warned they will vary with AI mix. Lower-cost models on Bedrock could pressure cloud pricing, so I want to hear how management talks about pricing.

Advertising grew 26% to $19.81B, and Thursday Night Football and NBA inventory sold out. On the retail side, Amazon expects to more than double its robotic arm fleet in 2026, which should help offset fuel inflation and higher line-haul rates.
Finally, I’ll focus on operating income over GAAP EPS. Anthropic gains have moved recent results, and core earnings growth is the cleaner signal.
Free Cash Flow Is Where Trust Gets Rebuilt
Trailing free cash flow turned negative at -$7.6B after Q2. Jassy insists “we have clear line of sight to strong financial returns.” Amazon has beaten EPS estimates in 11 of its last 12 reports. This time, the key test is whether the backlog shows up in revenue fast enough to justify the spending.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.