Alphabet Failed Wall Street’s New AI Test. Amazon Takes It Tonight.
Alphabet just handed Wall Street a blueprint for punishing AI spending without proof of returns, and Amazon steps into the same spotlight tonight. One ratio separating AWS growth from capex will determine whether Amazon earns the Oracle treatment or repeats…

Wall Street’s new AI test just tripped up Alphabet (NASDAQ:GOOGL | GOOGL Price Prediction). The same test comes tonight after the close for Amazon (NASDAQ:AMZN). This week’s rule is simple: spend big on AI, but show it pays off. Tonight, I’m watching one ratio, AWS growth against capex.
Oracle Passed, Alphabet Failed
Alphabet grew Google Cloud revenue 103% to $30.71 billion. Even so, GAAP EPS of $2.12 missed the $2.97 estimate, and management signaled a significant increase in 2027 spending. The stock fell 13% today. CNBC says that puts it on course for its biggest ever post-earnings drop.
My Alphabet position dates to April 2012, and this reaction tells me investors now want to see the return before they pay back the spending.
Going the other way was Oracle (NYSE:ORCL). It rose 11% on October 28 after its investor day, where Oracle targeted more than $30 billion in annual free cash flow by fiscal 2029. For its part, Microsoft (NASDAQ:MSFT) reported 48% Azure growth, and its stock barely moved.
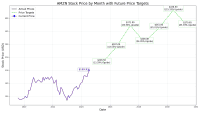
Amazon brings strong growth and a big bill into tonight. AWS grew 37% last quarter to $42.23 billion, its fastest pace in 18 quarters. Capex hit $54.21 billion, and trailing free cash flow turned negative at -$7.6 billion. Shares trade near $244.77. That’s down 4% today and 7% over the past week.

Consensus Sets a Modest Bar
The year-ago and full-year EPS figures are GAAP and include gains on Amazon’s Anthropic investment, so the EPS growth rates are noisy.
| Metric | Consensus | Year-Ago | Growth |
|---|---|---|---|
| Q3 EPS | $1.9579 | $1.95 | 0.4% |
| Q3 Revenue | $202.2B | $180.17B | 12.2% |
| FY2026 EPS | $12.9069 | $7.17 | 80% |
| FY2026 Revenue | $828.74B | $716.92B | 15.6% |

AWS Growth Against Capex Decides Everything
AWS growth comes first. Last quarter’s 37% is the bar, and Microsoft’s Azure number makes the comparison harder.
Margin is next. On the July call, CFO Brian Olsavsky said AWS margins will vary with investment levels, product mix, and AI versus non-AI mix. The question is whether the 39.4% margin holds up as new capacity comes online.
Then capex. Spending rose 68% year over year last quarter, and Amazon raised its 2026 plan in July because memory costs went up. All of that spending goes to the power, cooling, and networking suppliers behind the data centers (we covered seven of them in a free report on the AI buildout). That’s exactly what sank Alphabet: a 2027 step-up with no matching revenue.
Finally, the return timeline. CEO Andy Jassy said servers break even in a little less than three years and last at least five to six years. He also said AWS has a "clear line of sight to strong financial returns." The AWS backlog was at $496 billion, and most 2027 capacity is already reserved. Oracle got pay back for putting a date on free cash flow. The question is whether Jassy does the same.
Which Result Breaks the Trade
If AWS speeds up past 37%, margins stay near 39%, and management gives a date for free cash flow, I think Amazon gets the Oracle treatment. If AWS stalls while capex rises again with no timeline, Alphabet’s selloff is the template. Amazon fits your portfolio if you believe that backlog turns into cash. If you doubt it, this week showed how fast the market punishes spending it can’t yet see paying off. Tonight shows whether Amazon passes the test Alphabet just failed.
Contact [email protected] for any questions or corrections.
I've been writing about stocks and personal finance for 20+ years. I believe all great companies are tech companies in the long run, and I invest accordingly.