AbbVie Options Price In a Sudden 5% Swing—What Investors Must Know Before Oct. 30
AbbVie heads into its October 30 earnings report riding a 28% rally and fresh FDA approvals, but options traders are bracing for a 5% swing in either direction and the stock has a recent habit of selling off even on…

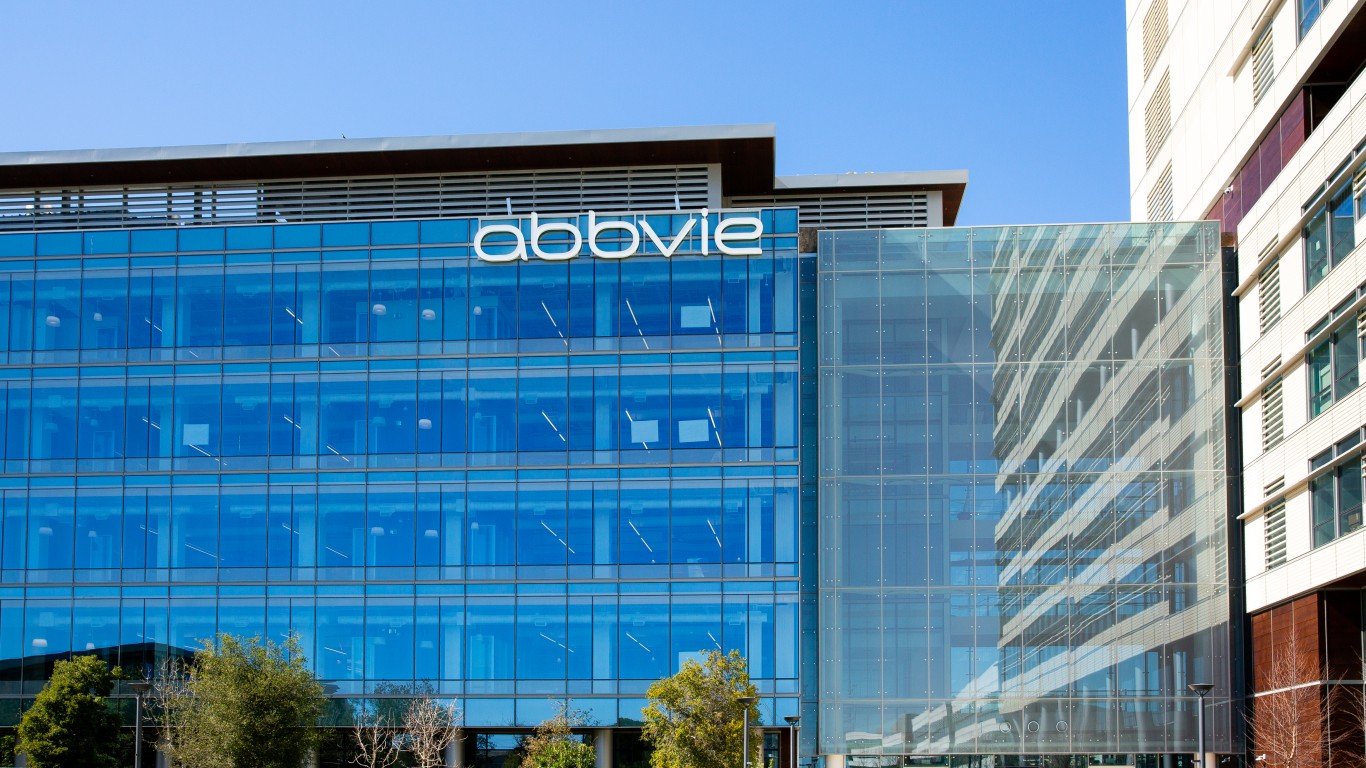
AbbVie (NYSE:ABBV | ABBV Price Prediction) reports third-quarter results before the open on October 30. Shares are up 28.55% year to date, and options pricing implies a roughly 5% move on the release. That leaves little room for a stumble.
Big Momentum Meets a Guidance Trim
Last quarter, AbbVie posted adjusted EPS of $3.65 on revenue of $16.99 billion, up 10.2% year over year. Skyrizi grew 24.4% to $5.51 billion and Rinvoq rose 24.5% to $2.53 billion, which more than made up for a 35.9% slide in Humira.
Management still trimmed full-year adjusted EPS guidance to $13.87 to $14.07. The cut included $0.14 of dilution from the roughly $10.9 billion Apogee Therapeutics deal, partly offset by $0.10 of operational overperformance. Revenue guidance rose $300 million to about $67.6 billion.

Several catalysts have arrived since then. The FDA approved Juvmo (tavapadon) for Parkinson’s disease on September 28 and Skyrizi’s subcutaneous induction regimen for Crohn’s disease on October 23. Lutikizumab also posted positive Phase 3 results in hidradenitis suppurativa, and the stock gained 8.24% over the past month to $285.19.
Consensus Points to a Sharp Profit Rebound
Analysts expect EPS to roughly double. The year-ago quarter included a $1.50 per-share acquired IPR&D charge, which inflates the comparison.
| Metric | Q3 2026 Consensus | YoY Growth | FY2026 Consensus | YoY Growth |
|---|---|---|---|---|
| Normalized EPS | $3.7788 | 103.2% | $13.9562 | 39.6% |
| Revenue | $17.35 billion | 10.0% | $67.63 billion | 10.6% |
Immunology Pace and Apogee Math Will Set the Tone
Skyrizi and Rinvoq now generate nearly half of revenue, and analysts expect Rinvoq to clear roughly $2.73 billion. In July, management raised Skyrizi’s full-year outlook to $21.7 billion and reported “absolutely no degradation” in new starts after a rival launch. Both trends should show up in the quarterly numbers.
Guidance is the second test. Consensus EPS of $3.7788 sits below management’s $3.84 to $3.88 target after eight downward revisions over 30 days.
That target excludes acquired IPR&D, which cost $0.58 per share through June, and includes partial-quarter Apogee dilution. The focus will be on confirmation that the deal closed and whether operational strength again offsets the drag on the full-year range.
Neuroscience grew 20.3% to $3.23 billion last quarter, and management expects Vyalev to reach blockbuster sales this year. Chief Commercial Officer Jeffrey Ryan Stewart said on the July call that the tavapadon ramp “will be modest at first.” Management expects Skyrizi’s new Crohn’s regimen to drive acceleration starting early in 2027.
Finally, track the drags. Imbruvica fell 29.4% and Juvederm slipped 6.0% in the second quarter, and the pace of Humira erosion still determines how much of the immunology gain reaches the top line.
A Premium Rally Needs Clean Execution
AbbVie trades near 20x full-year consensus EPS, and recent history shows beats can still trigger selling. Shares fell 4.45% on earnings day after the Q3 2025 beat and 2.51% after the Q2 2026 beat. Positioning leans bullish, with a 0.59 put/call ratio on contracts expiring October 30. A raised outlook and a clean Apogee update would give this rally steadier ground.

Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.