Prediction: AbbVie’s Next Billion-Dollar Opportunity Is Taking Shape
Skyrizi and Rinvoq are growing fast, a blockbuster acquisition just closed, and the FDA handed AbbVie a fresh approval, yet the stock sits just shy of a price target that has Wall Street divided between a $297 bull case and…

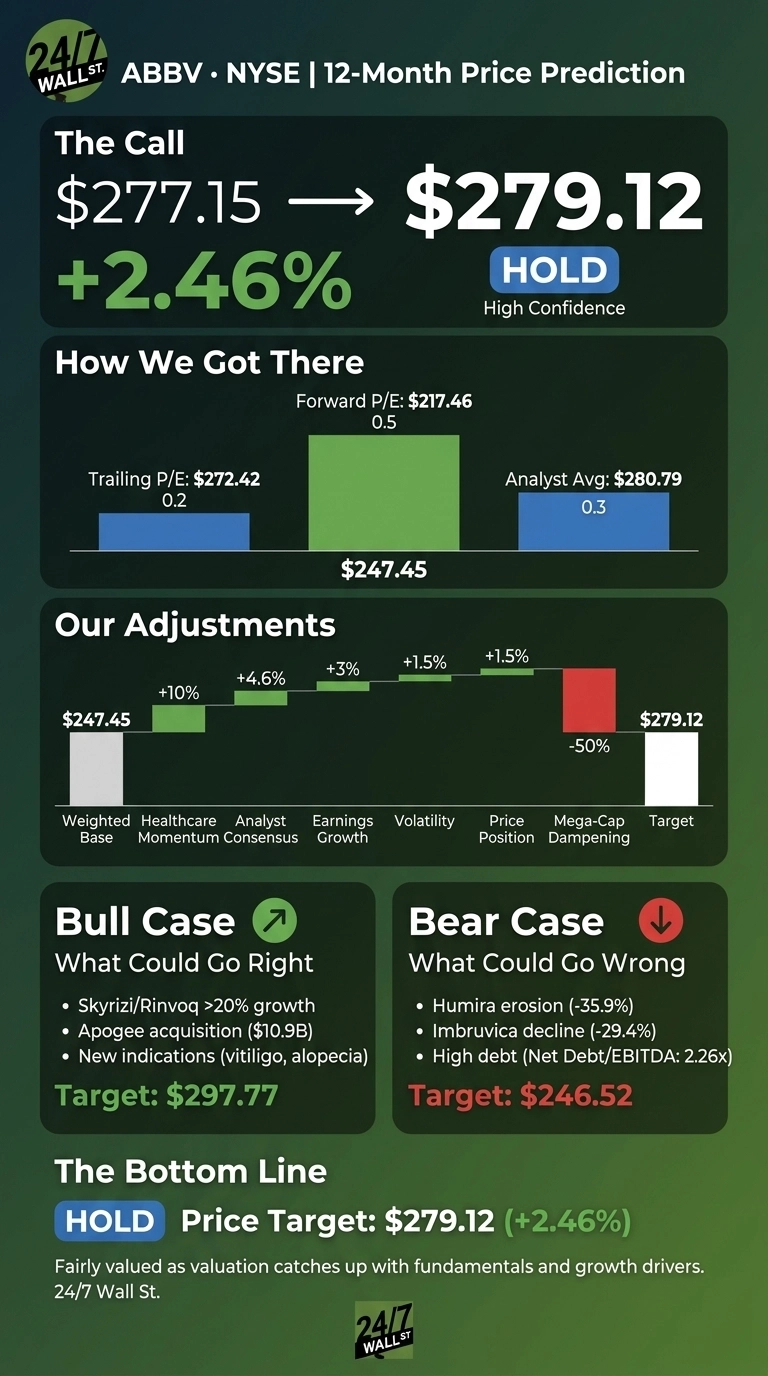
AbbVie (NYSE:ABBV | ABBV Price Prediction) trades at $277.15 midday Friday. Our 24/7 Wall St. price target is $279.12 over 12 months, representing 2.46% upside from the model price.
Our high confidence reflects broad growth: Skyrizi, Rinvoq and neuroscience each delivered growth above 20% last quarter. AbbVie completed its Apogee Therapeutics acquisition on September 3, 2026. The stock sits near the $280.79 consensus target, limiting upside.

A Breakout Above the 52-Week High Shows Momentum Building
Shares rose 6.62% over the past week, 11.4% over the past month and 24.16% year to date, breaking above the prior 52-week high of $274.94.
Second-quarter revenue of $16.99 billion rose 10.2%, ahead of the $16.76 billion consensus. Adjusted EPS of $3.65 met the $3.64 estimate. Management raised revenue guidance by $300 million to about $67.6 billion. The FDA approved JUVMO (tavapadon) for Parkinson’s disease, and Temab-A received two Breakthrough Therapy Designations.
Why Bulls See $297 Within Reach
Skyrizi sales reached $5.51 billion last quarter, up 24.4%, with management expecting $21.7 billion for the full year. Rinvoq peak sales in vitiligo and alopecia areata alone could approach $2 billion. Apogee’s zumilokibart posted positive Phase 2 results in atopic dermatitis, positioning it as a credible billion-dollar candidate.
A new under-the-skin Skyrizi dose for Crohn’s disease could accelerate growth starting “really early in 27”. Wall Street gives 8 Strong Buy and 16 Buy ratings to the stock. The bull case reaches $297.77.

Humira Erosion and Debt Keep Risks on the Table
Humira sales fell 35.9% to $756 million, and Imbruvica dropped 29.4%. Net debt stands at 2.26x EBITDA. The trailing P/E of 114 reflects $5 billion in acquired R&D charges in 2025.
On forward earnings, the stock trades at 16x. Management targets two times net leverage within two to three years. Our bear case is $246.52.

How AbbVie Compares to Merck and Eli Lilly
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| AbbVie | 16x | 10.2% |
| Merck | 15x | 5.1% |
| Eli Lilly | 24x | 47.7% |
Merck (NYSE:MRK) faces a similar patent cliff. Keytruda sales of $7.904 billion declined 1%. Merck trades at a discount to AbbVie, which makes sense given AbbVie’s faster growth.
Eli Lilly (NYSE:LLY) competes in immunology through Ebglyss, whose sales rose 131%. Lilly’s premium multiple reflects much faster growth. AbbVie sits between both peers.
AbbVie Price Prediction 2026-2030
Our 24/7 Wall St. price target of $279.12 carries a hold rating and 90% confidence. After the rally, valuation has caught up with fundamentals. Approval of the Skyrizi Crohn’s dose or strong Rinvoq dermatology launches could turn positive.
Accelerating Humira declines or higher Apogee integration costs would call for caution. For now, AbbVie looks fairly valued.
The 24/7 Wall St. price target model projects where AbbVie could trade if current growth trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $274.36 |
| 2027 | $279.12 |
| 2028 | $289.22 |
| 2029 | $300.38 |
| 2030 | $314.29 |
These estimates assume AbbVie executes its immunology strategy. Key swing factors: Skyrizi’s patent defense ahead of 2033 expiration and how quickly Apogee drugs reach market.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.