AbbVie Hit a New High After Earnings. There’s More Upside Left.
AbbVie just logged a 33% gain for the year and raised its guidance again, but the real question is whether Skyrizi and a newly closed pipeline deal can push shares even further past a valuation that already looks stretched.

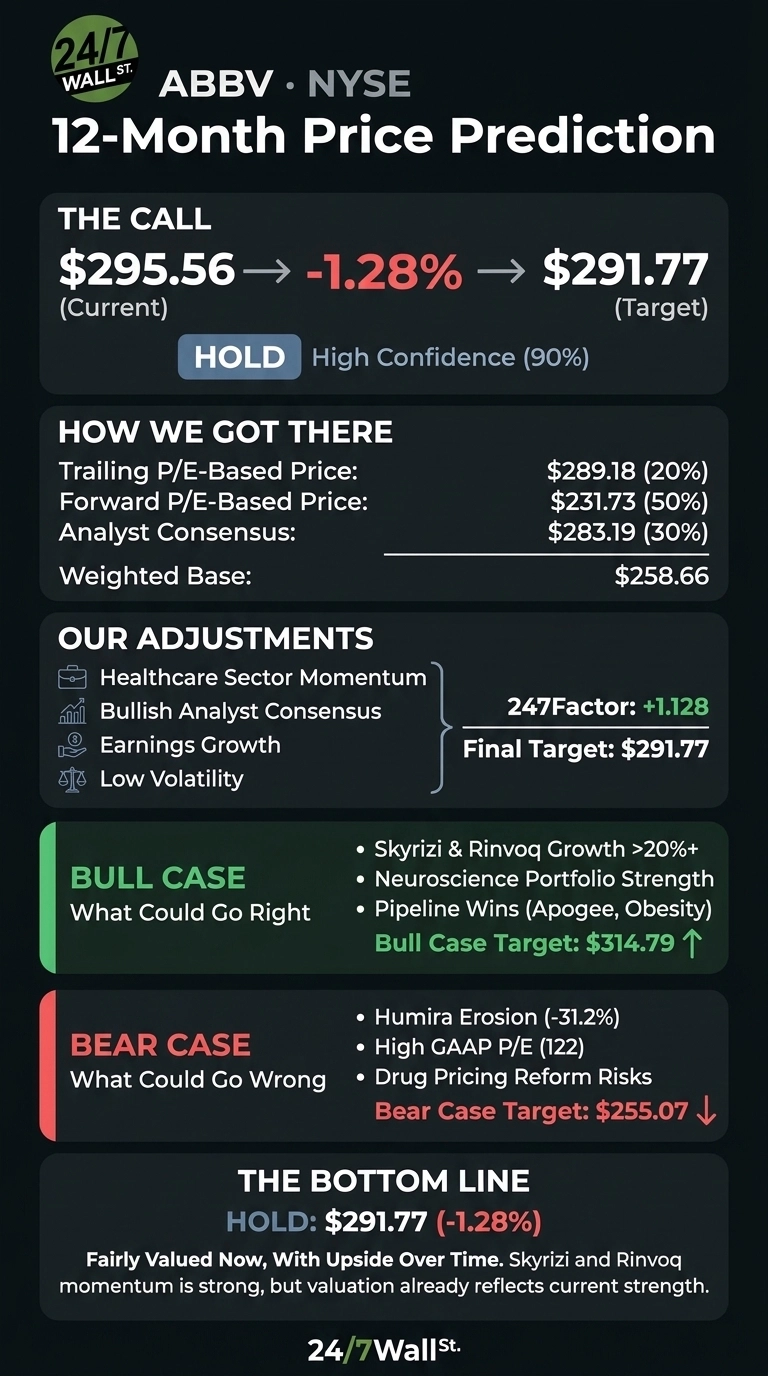
AbbVie (NYSE:ABBV | ABBV Price Prediction) moved higher after third-quarter results, trading at $295.56 Friday morning. The 24/7 Wall St. price target is $291.77, which means -1.28% from here. Our model rates the stock a hold with high confidence.
| Metric | Value |
|---|---|
| Current Price | $295.56 |
| Price Target from 24/7 Wall St. | $291.77 |
| Upside/Downside | -1.28% |
| Recommendation | HOLD |
| Confidence Level | 90% |

The rally has caught up with the fundamentals. Over the next year, our bull scenario hits $314.79, which is why the longer-term setup still looks positive.
Why We Could Be Wrong
The 24/7 Wall St. price target stands just below where AbbVie trades today. Skyrizi’s newly approved subcutaneous induction for Crohn’s disease could speed up growth.
The Apogee pipeline could also lift the long-term earnings curve faster than our model assumes. Treat our target as one datapoint among many. Below, the upside scenario lays out how AbbVie could outperform.
A 33% Run Capped by Another Guidance Raise
Shares have gained 3.64% over the past week, 12.94% over the past month and 33.22% year to date, far above the 52-week low of $188.25.
Adjusted EPS of $3.82 exceeded the $3.78 estimate. Revenue of $17.40 billion rose 10.3% on strength in immunology and neuroscience (WSJ). AbbVie lifted full-year EPS guidance to $13.95 to $13.99 and raised the quarterly dividend from $1.73 to $1.82.

Skyrizi and Rinvoq Point Toward $315
Skyrizi and Rinvoq generated $8.48 billion combined this quarter, growing 22.7% and 23.9%. Neuroscience rose 19.4%. On the pipeline side, Juvmo won approval for Parkinson’s, the Apogee deal has closed and obesity candidate ABBV-295 is moving into Phase 2.
Wall Street leans bullish, with 24 buy or strong-buy ratings against one strong sell. If the upside scenario plays out, the stock hits $314.79.

Humira Erosion and Valuation Risks Worth Watching
Humira fell 31.2%, Imbruvica dropped 26.1% and Juvederm declined 11.9%. The GAAP P/E of 122 looks high. GAAP EPS of $2.37 included $1,669 million of intangible amortization.
Negative equity mostly reflects buybacks and dividends. Skyrizi’s composition-of-matter patent runs to 2033. The downside scenario is $255.07.

AbbVie Sits Between Johnson & Johnson and Bristol-Myers on Valuation
Johnson & Johnson (NYSE:JNJ) competes directly in immunology. Tremfya grew 72.5% while Stelara fell 55.2%. At a forward P/E of about 24x, J&J trades above AbbVie despite slower growth.
Bristol-Myers Squibb (NYSE:BMY) is also replacing revenue lost to patent losses. Its Growth Portfolio rose 12%, and the stock trades near 10x forward earnings. That discount reflects a transition that is less proven than AbbVie’s.
| Company | Forward P/E (2026 Guidance Midpoint) |
|---|---|
| AbbVie | 21x |
| Johnson & Johnson | 24x |
| Bristol-Myers Squibb | 10x |
Against this group, the 24/7 Wall St. price target looks reasonable, and even conservative compared with J&J.
Fairly Valued Now, With Upside Over Time
Our 24/7 Wall St. price target of $291.77 carries a hold rating at 90% confidence. The key factor is valuation. After a 33.22% run this year, the price already reflects the quarter’s strength.
I would turn more positive if the Skyrizi Crohn’s launch speeds up growth in early 2027. I would get more conservative if Humira erosion exceeds Skyrizi and Rinvoq. For now, AbbVie looks like a high-quality compounder trading at fair value.
AbbVie Price Prediction 2026-2030
These projections extend our model’s base-case annualized return of 3.1%.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $291.77 |
| 2027 | $300.81 |
| 2028 | $310.14 |
| 2029 | $319.75 |
| 2030 | $329.67 |
The projections assume AbbVie keeps executing in immunology. Pipeline wins could moved the stock toward our five-year bull case of $386.24. Drug pricing reform would weigh on the outlook.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.