Applied Digital Keeps Cratering: This Analyst Keeps Insisting It’s Going to Jump by 390%
Applied Digital just posted the strongest quarter in its history, yet the stock cratered more than 30% immediately after. One analyst still sees nearly 400% upside from here, and the reasons behind that gap reveal a high-stakes bet on the…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Applied Digital (NASDAQ:APLD) currently trades at $18.25, while the average analyst target stands at $62.44. That gap implies 242.1% upside.
Applied Digital builds and runs purpose-built AI data center campuses in North Dakota and the southern U.S. It leases capacity to CoreWeave (NASDAQ:CRWV) and investment-grade hyperscalers and holds about $36B in contracted revenue. The highest target on the Street is more aggressive still. Lake Street Capital Markets analyst Rob Brown holds a $90.00 target, which works out to 393.2% upside. With a gap that wide, the market and the analysts disagree sharply on this stock.
A Record Quarter Failed to Stop a Steep Slide
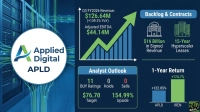
Applied Digital has fallen 32.98% in one month. That is a selloff of more than 30%, and it started right after the strongest quarter in company history. Shares stood at $25.45 when the company reported fiscal Q1 2027 revenue of $341.88M, beating the $124.57M consensus. Adjusted EPS of -$0.01 exceeded the -$0.3023 estimate, marking a 6th consecutive EPS beat.
Investors looked past those beats to the balance sheet. The company posted a GAAP net loss of $184.06M and spent $2.07B on capex in the quarter. It has $6.4 billion in total debt against about $3.7 billion in cash and restricted cash. Rising yields and a sliding Bitcoin (CRYPTO:BTC) price pressured the whole group. Rothschild & Co Redburn also initiated coverage at Neutral with a $22 target, highlighting execution, power and pipeline-conversion risks. As the stock hit a one-year low, co-founders Wes Cummins and Jason Zhang bought about $6.7 million in shares.
Why Analysts Kept Raising Targets Into the Selloff
The contracted backlog supports the bullish thesis. Applied Digital has about 1.41 GW of leased critical IT load, and the contracts reach ~$86B if all renewal options exercised. Management expects “to place over 600 megawatts into service versus the 250 megawatts over the past 12 months.”
Pricing is the next catalyst. Management expects about 250 megawatts of expansion leases by calendar year-end, with lease rates up “definitely north of 15%”. The ChronoScale compute unit is on track for $1 billion of ARR in 2027. The longer-range target is 3.5 to 4 gigawatts by the end of calendar year 2030.
Recent analyst moves have mostly been reiterations and upgrades. Wells Fargo kept its Overweight rating and lifted its target to $55. Morgan Stanley stayed at Equal-Weight but upgrades its target to $41. Jones Trading initiated at Buy with a $70 target. Needham and B. Riley hold targets in the $70–$85 range.
The consensus fiscal 2028 EPS estimate has slipped to -0.7844 from -0.2500 30 days ago, which means analysts expect losses to continue for at least two more years.
Neocloud Peers Fell Even Harder Than Applied Digital
The whole group sold off together, and Applied Digital held up better than its closest rivals.
IREN (NASDAQ:IREN) has dropped 47.07% in a month to $24.91. Its average target of $77.81 implies 212.4% upside, which is smaller than Applied Digital’s. Of its 20 analysts, two call it a Strong Buy, 13 a Buy and five a Hold. Its latest quarterly revenue of $137.20 million missed estimates.
Cipher Digital (NASDAQ:CIFR) has fallen 56.73% in a month to $7.94. Its average target of $29.36 implies 269.8% upside, which is larger than Applied Digital’s. Of its 22 analysts, five call it a Strong Buy, 15 a Buy and two a Hold, despite a Q2 EPS of -0.65 that missed estimates.
Cipher offers the biggest consensus upside among the three. Applied Digital has the most aggressive single target and is the only one of the three beating estimates. None of these targets is a guarantee.
Down 25.57% This Year While the S&P 500 Gained 11.45%
At $18.25, Applied Digital trades near its 52-week low of $17.65 and far below its high of $50.73. The 15 covering analysts average $62.44, which implies 242.1% upside. The ratings break down this way:
- Strong Buy: 2
- Buy: 11
- Hold: 2
- Sell: 0
The stock is down 25.57% so far this year, compared with an S&P 500 gain of 11.45%. Over one year, Applied Digital has lost 45.33%, against a 13.13% gain for the index. A beta of 6.0 explains why the moves in both directions are so large.
A Real Backlog Weighed Down by Real Debt
The bullish thesis improves if the 600-plus megawatts reach service on schedule and the expansion leases close at higher rates. Should both occur, base rent replaces one-time fit-out revenue and the 89% NOI margin on HPC operations starts to has the income statement. But the stock looks like a value trap if capital markets tighten before Polaris Forge 3 and the two Delta Forge campuses are financed. A free cash flow yield of -50.3% leaves little room for error.
The bullish thesis has support. The contracts are signed, insiders are buying, and Applied Digital is the only name in the group beating estimates. The $90 target needs years of flawless execution, so it reads as a ceiling, while the average target reflects a multiyear outlook. All of that AI data center expansion still has to be powered, cooled, and networked by somebody, and we rounded up seven suppliers doing exactly that in a free report on the AI boom beyond the chipmakers. Watch the stock around the next lease announcements.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.