One Catalyst Could Completely Change the Tesla Stock Story
Tesla bulls and bears have fought over the same question for two years, but one unproven catalyst is now close enough to either vindicate the optimists or expose the premium as fantasy.


Tesla investors have spent two years arguing over whether they own a carmaker or an AI platform. After the third-quarter report, one catalyst could settle the argument: the unsupervised Robotaxi fleet.
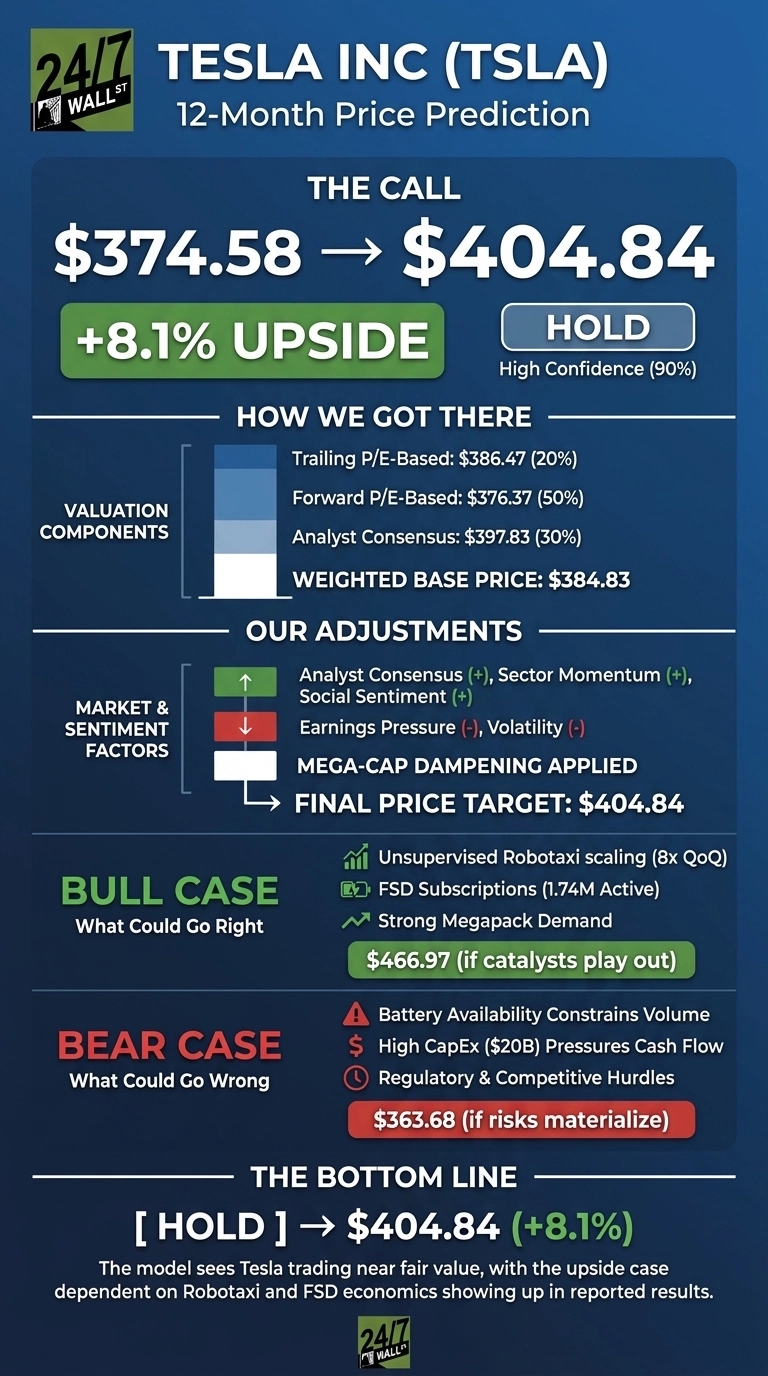
The 24/7 Wall St. price target for Tesla (NASDAQ:TSLA | TSLA Price Prediction) is $404.84. That implies 8.1% upside from the $374.58 close on October 22.
| Metric | Value |
|---|---|
| Current Price | $374.58 |
| Price Target from 24/7 Wall St. | $404.84 |
| Upside/Downside | 8.1% |
| Recommendation | HOLD |
| Confidence Level | 90% |
The model has high confidence and sees Tesla trading near fair value, so we rate it a hold. The upside case depends on Robotaxi economics showing up in reported results, and that has not happened yet.
Battery Shortages Capped a Q3 Beat as Shares Slid 16.71% This Year
Shares rose 3.35% over the past week but fell 1.14% over the past month and are down 16.71% year to date. Tesla sits 24.9% below its 52-week high of $498.83.
Q3 revenue of $28.05 billion came in just above the $28.02 billion estimate, and EPS of $0.48 beat the $0.45 consensus. Operating income still fell 55.79% as R&D rose to $2.76 billion.
Battery supply limited deliveries to 486,532, even though the order backlog is the largest in four years. On top of that, reports of merger talks with SpaceX have raised fresh questions about valuation (Morningstar).

Why Bulls See Robotaxi Rewriting the Math
Cybercab joined the unsupervised Austin fleet on September 3, and cumulative unsupervised miles rose 8x quarter over quarter to nearly 2 million. Management said Dallas is next and that some customer cars could join the fleet “somewhere around Q2 next year,” with Robotaxi becoming a meaningful source of profit in 2027.
FSD subscriptions reached 1.74 million, up from 1.04 million. Megapacks are nearly sold out for 2027, and energy gross margin rose to 33.1%. The bull case of $466.97 implies 24.7% upside.

What Could Stall the Autonomy Story
Free cash flow fell 61.63% to $1.53 billion, and management now expects about $20 billion in capex this year. Robotaxi has yet to reach its target of 30 cents per mile, and traders put the odds of a California launch this year at just 13%.
Among analysts, 21 rate the stock a hold. In fairness, cash rose to $45.45 billion, so the margin squeeze is funding autonomy and robotics rather than signaling financial stress. The bear case is $363.68.

How Tesla Compares to GM and Ford
General Motors (NYSE:GM) is the main Detroit rival in EVs and autonomy. GM trades at 25x earnings after Q3 EPS of $3.70.
Ford (NYSE:F) shows the value end of the sector, with a 6.39% dividend yield, negative GAAP earnings, and Model e losses of roughly $4 billion.
| Company | Trailing P/E | P/FCF |
|---|---|---|
| Tesla | 390 | 238 |
| GM | 25 | 6 |
| Ford | Negative | 4 |
On auto multiples, our target looks aggressive. Investors are paying for software and autonomy, so Robotaxi has to produce real revenue to back up the premium.
Tesla Price Prediction 2026-2030
The 24/7 Wall St. price target is $404.84, rated hold with 90% confidence. The steep cost of building out autonomy tips the scale.
I would turn more bullish if Robotaxi cities and customer-car integration arrive on schedule. I would stay cautious if battery shortages and capex keep eating into cash flow.
The 24/7 Wall St. price target model projects where Tesla could trade if current trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $377.71 |
| 2027 | $411.74 |
| 2028 | $411.51 |
| 2029 | $448.39 |
| 2030 | $456.84 |
The projections assume Tesla keeps executing its current strategy. A SpaceX merger, which traders give 65.5% odds of being announced by the end of 2027, or a faster Robotaxi rollout could move the outlook sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.