Meta’s Capital Raise Is Spooking Investors. What the Price Targets Say Now
Meta just handed investors a legal charge, negative free cash flow, and a brand-new share class designed for raising capital, all in one earnings report. Whether that combination signals a buying opportunity or a warning sign depends on which number…

Meta Platforms (NASDAQ:META | META Price Prediction) has dropped sharply since earnings. Investors are dealing with free cash flow that turned negative and a new non-voting share class built for capital raising, both in the same report.
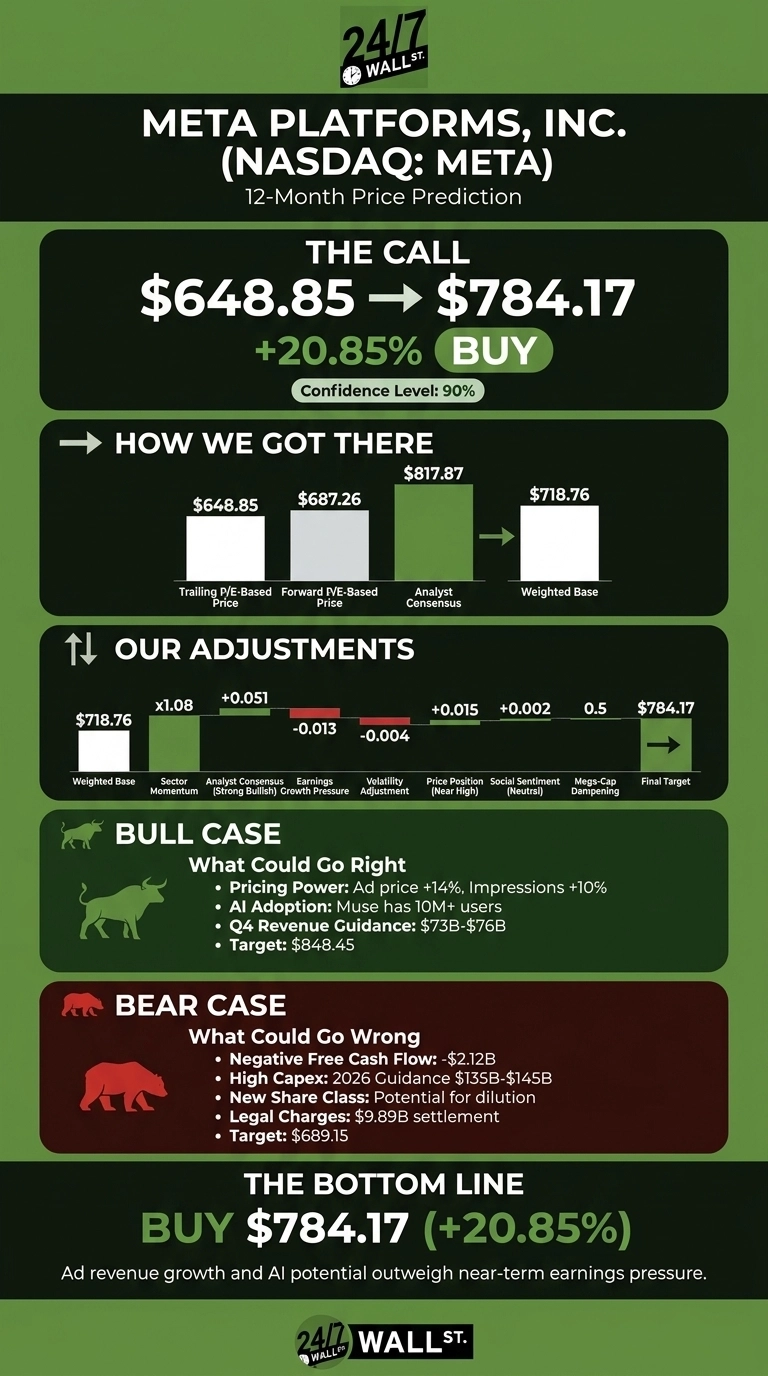
The 24/7 Wall St. price target for Meta stands at $784.17, which means 20.85% upside from the last close over the next 12 months.
| Metric | Value |
|---|---|
| Current Price | $648.85 |
| Price Target: 24/7 Wall St. | $784.17 |
| Upside/Downside | 20.85% |
| Recommendation | BUY |
| Confidence Level | 90% |
That confidence level is high. It shows strong revenue momentum and broad analyst support, which outweigh the near-term pressure on earnings.

A Legal Charge and Negative Free Cash Flow Sparked the Sell-Off
Meta shares fell 12.76% over the past week, leaving them down 2.39% year to date. The stock stands between its 52-week high of $779.82 and its low of $519.37.
Third-quarter revenue of $64.60 billion beat the $63.39 billion estimate. GAAP EPS of $3.83 missed expectations of $5.6986. The cause was a $9.89 billion charge from the settlement with state attorneys general. Excluding that charge, EPS was $7.40.
Capex hit $34.91 billion, and free cash flow came in at negative $2.12 billion. That free cash flow figure caused much of the selling after the report. On the call, the CFO said of the new share class: “We don’t have any specific financing plans to announce at this time.”

Why Bulls See $848 and Beyond
Pricing power is the core of the bull case. Average price per ad rose 14% and impressions grew 10%, across 3.64 billion daily active people. Meta’s AI assistant, Muse, signed up more than 10 million users in the U.S. and Canada within six weeks. Management expects to improve its compute efficiency by more than 10x in the next year.
Q4 revenue guidance is $73 billion to $76 billion, and Reality Labs losses are expected to narrow to about $15 billion in 2027. Piper Sandler raised its target to $875 from $785. The bull case hits $848.45.

Dilution, Debt and Courtrooms Are the Real Risks
Capex guidance for 2026 is $135 billion to $145 billion, and management plans to keep investing aggressively after 2026 (the suppliers on the receiving end of that spend, from power to cooling, are the subject of a free report we put together on the AI infrastructure buildout).
Debt of $83.7 billion now tops cash of $82.4 billion. Operating margin fell to 20% from 40% a year ago. Consensus 2026 EPS has fallen to $30.6104 from $33.0006 90 days ago, and more youth-related trials are coming.
There are offsets, though. Excluding legal charges, operating income would have grown 11%, and operating cash flow rose 9.29%. The bear case stands at $689.15.
Meta Trades Cheaper Than Alphabet and Microsoft
The closest comparison is Alphabet (NASDAQ:GOOGL) because it also runs on digital ads funded alongside heavy AI spending. It grows a bit slower than Meta yet trades at a higher multiple.
The scale of Meta’s AI expansion is matched by Microsoft (NASDAQ:MSFT). It earns a premium multiple on an operating margin of 45.1%, even though its revenue grows more slowly.
| Company | Forward P/E | Quarterly Revenue Growth |
|---|---|---|
| Meta | 19x | 26.07% |
| Alphabet | 23x | 24.2% |
| Microsoft | 25x | 17.7% |
Meta grows the fastest of the three and has the lowest multiple. Next to these peers, our target looks reasonable, and arguably conservative.
Meta Looks Mispriced After the Sell-Off
I’m sticking with the 24/7 Wall St. price target of $784.17, a buy rating and 90% confidence. Ad revenue growth in the mid-20% range at a forward multiple below its peers tips the scale.
I’d view Meta favorably if Muse starts producing revenue in 2027 and capex stays inside guidance. A more cautious stance would make sense if Class C stock is used for large equity raises or if litigation costs keep rising. The core business is strong enough to fund this spending cycle.
Looking further ahead, here is where the 24/7 Wall St. price target model projects Meta could trade, assuming current growth trends hold.
| Year | Price Target: 24/7 Wall St. |
|---|---|
| 2026 | $675.13 |
| 2027 | $787.98 |
| 2028 | $891.11 |
| 2029 | $1,005.23 |
| 2030 | $1,086.61 |
The projections rest on Meta continuing its current strategy. Muse monetization could add significant upside, while dilution from Class C shares or more youth litigation could pull the stock below this path.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.