Our Model and Wall Street Agree on Amazon’s Target. Now the Quarter Has to Deliver.
Our proprietary model and the full Wall Street consensus landed on virtually the same Amazon price target, but one upcoming earnings report could confirm the trade or blow the thesis apart.

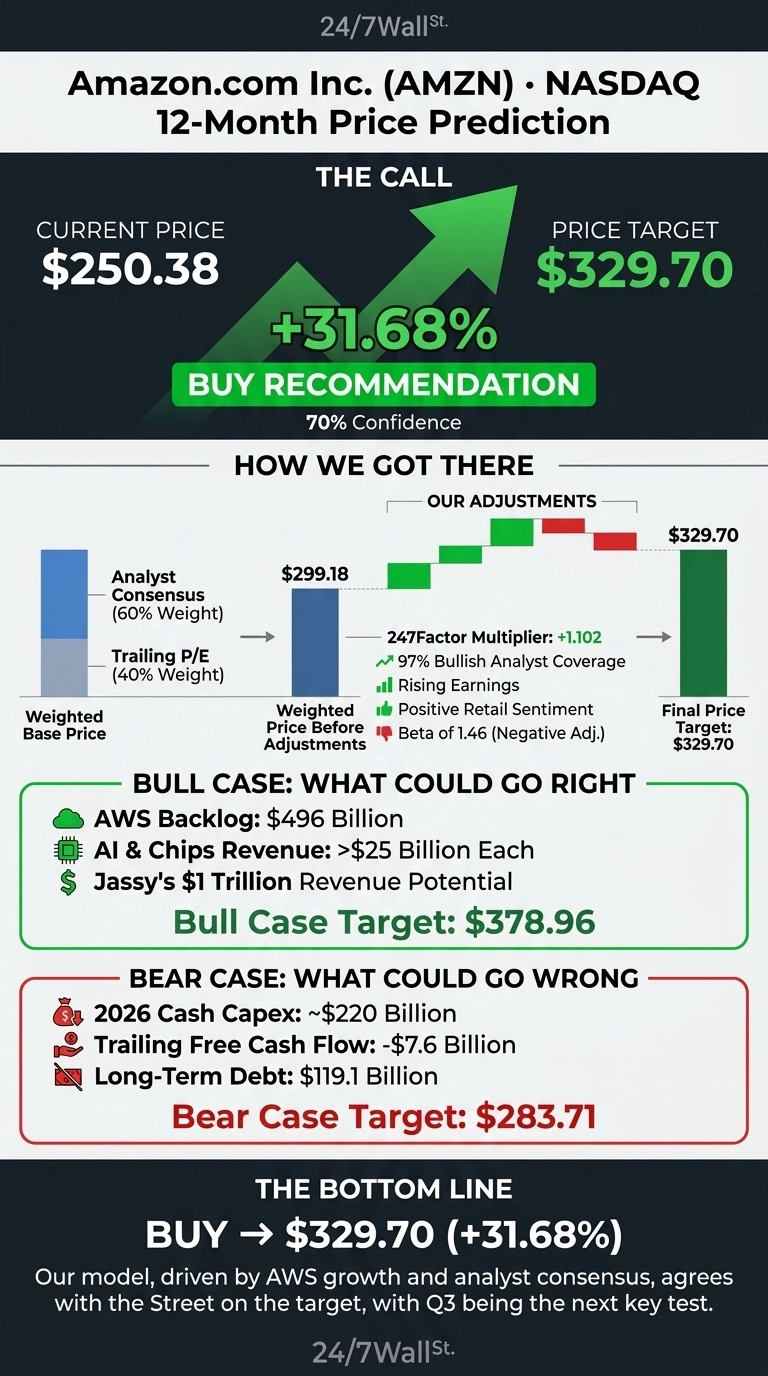
The 24/7 Wall St. price target for Amazon (NASDAQ:AMZN | AMZN Price Prediction) is $329.70. That is 31.68% above the $250.38 close. The model rates the stock a buy with 70% confidence.
| Metric | Value |
|---|---|
| Current Price | $250.38 |
| Price Target from 24/7 Wall St. | $329.70 |
| Upside/Downside | 31.68% |
| Recommendation | BUY |
| Confidence Level | 70% |
Our target stands within 0.61% of the Wall Street consensus target of $331.72. Q3 results are expected October 29 after the close. The company forecast to sales of $197 billion to $202 billion and operating income of $22.5 billion to $26.5 billion, compared with $17.4 billion a year ago.

Amazon Stalls Below Its High After a Blowout Q2
Shares fell 2.27% over the past week and 2.36% over the past month, which leaves the year-to-date gain at 7.86%. The stock trades about 12.8% below its 52-week high of $287.20. CNBC recently looked at what Amazon must do to get its “stumbling” stock back to record highs.
The latest quarter did little to explain the slide. Q2 revenue rose 19.6% to $200.61 billion, beating the $196.43 billion estimate. GAAP EPS of $5.75 included a $53.4 billion gain on Amazon’s Anthropic stake. Adjusted EPS of about $1.88 still exceeded consensus. AWS revenue grew 37% to $42.23 billion, and advertising rose 26%.

Why Bulls See $379 Within Reach
The bull case of $378.96 depends on AWS. Its backlog reached $496 billion, and the AI and chips businesses each run above $25 billion a year.
Andy Jassy said AWS has “the potential to be a $1 trillion revenue business.” Wall Street mostly agrees, with 16 Strong Buy and 43 Buy ratings, 2 Holds, and no Sells.

Capex Is the Risk Worth Watching
The bear case is $283.71. Amazon now expects about $220 billion in 2026 cash capex. Trailing free cash flow is -$7.6 billion, and long-term debt rose to $119.1 billion. Q2 operating income also got about $1.2 billion of help from tariff refunds and an energy-contract gain, and those may not repeat.
Management has an answer to the spending concern. Jassy said servers take a little under three years to break even. Most AI capacity is signed for at least five-year terms, so much of this spending is supported by contracted demand.
(All of that AI capacity has to be powered, cooled, and networked by somebody. We covered seven suppliers behind the data-center expansion in a free report here: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers).)
How Amazon Compares to Walmart and Alphabet
Walmart (NASDAQ:WMT) is Amazon’s closest retail rival. Walmart trades at 44x earnings with a 4.18% operating margin. With a lower multiple and a wider margin, Amazon makes our target look conservative next to Walmart.
In cloud, ads, and AI spending, Alphabet (NASDAQ:GOOGL) competes with Amazon. Google Cloud grew 82% last quarter. Alphabet’s 14x P/E is reduced by a $99.03 billion gain on equity holdings, much like Anthropic gains lower Amazon’s. Overall, the peer group makes our target look reasonable.
| Company | Trailing P/E | Operating Margin |
|---|---|---|
| Amazon | 21x | 11.16% |
| Walmart | 44x | 4.18% |
| Alphabet | 14x | 32.06% |
Our Model Rates Amazon a Buy Into Q3
The 24/7 Wall St. price target of $329.70 accounts for a buy rating at 70% confidence, and AWS is the main reason. The case gets stronger if Q3 operating income lands near the top of guidance and AWS keeps growing near its Q2 pace.
It gets weaker if capex rises again without matching growth in backlog. Our model and the Street now agree on the target, and Q3 is the next test.

These figures extend the 24/7 Wall St. price target model and assume current growth trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $262.13 |
| 2027 | $329.70 |
| 2028 | $374.57 |
| 2029 | $425.55 |
| 2030 | $483.47 |
The projections rest on Amazon continuing to execute on its current strategy. AI demand could add significant upside, and a capex overrun could cause significant downside.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.