Moderna Jumps 4% Despite William Blair Downgrade on Valuation; Novavax and BioNTech Edge Higher
Moderna stock is surging even after an analyst cited its 636% yearly gain as reason enough to step back, and the real question is whether Wall Street is pricing in a cancer breakthrough that has yet to prove itself outside…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

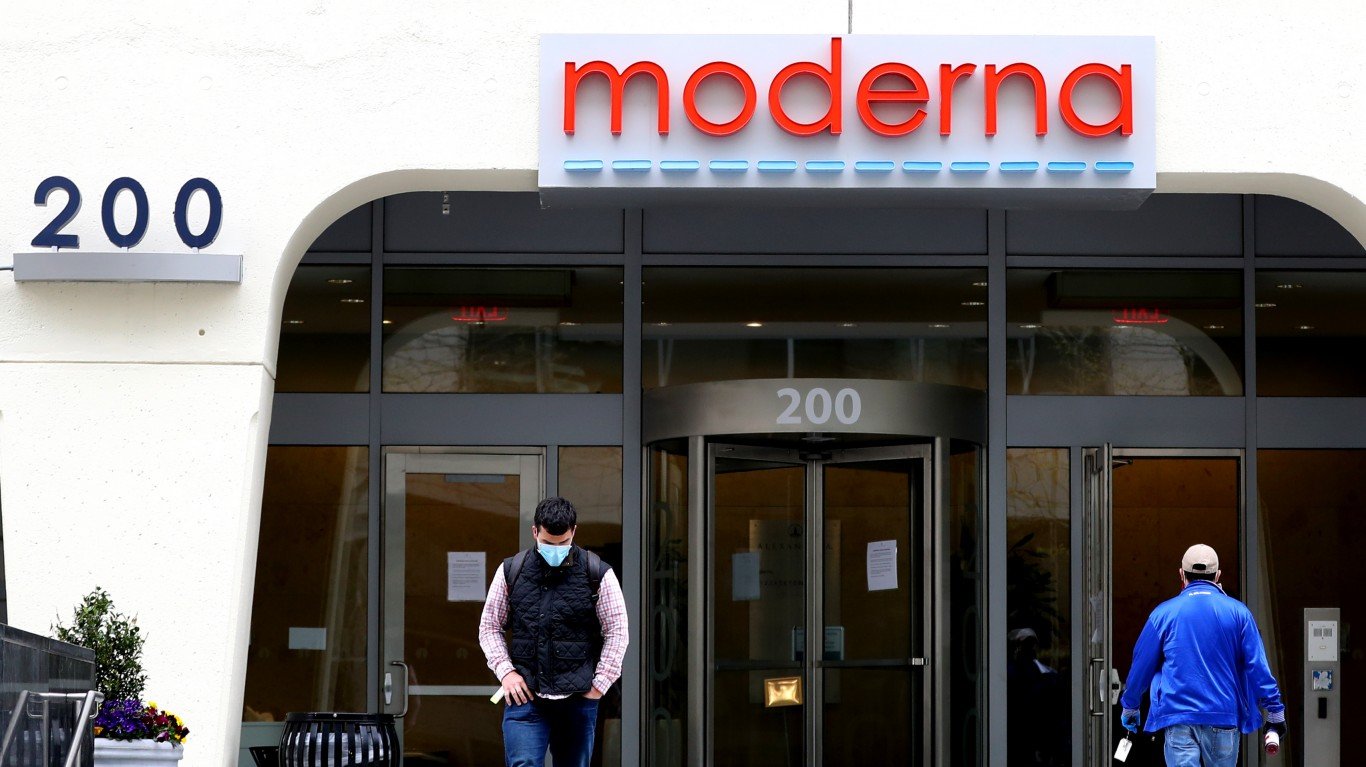
Shrugging off a valuation downgrade, Moderna (NASDAQ:MRNA | MRNA Price Prediction) is climbing as investors weigh strong cancer vaccine data against a share price that already reflects big expectations. Moderna stock stands at $217, up 4% this morning.
Novavax (NASDAQ:NVAX) stock is at $10.30, up 2%. At the same time, BioNTech SE (NASDAQ:BNTX) stock is at $88, up 0.6%.

Why William Blair Downgraded Moderna After Strong Melanoma Data
William Blair downgraded Moderna to Market Perform from Outperform on October 27, citing valuation after a 636% gain year to date.
Analyst Myles Minter sees 70% to 75% odds of success. He said Moderna’s share price implies that probability across expanded oncology indications, while the firm models $5.4 billion in peak melanoma sales for intismeran, shared equally by Moderna and Merck (NYSE:MRK). That leaves the firm’s net present value estimate only slightly above Moderna’s market value, though the analyst acknowledged that interim data for intismeran with Merck’s Keytruda in adjuvant melanoma supports a potential new standard of care.

The Phase 3 INTerpath-001 trial is from Moderna and Merck. Presented at the European Society for Medical Oncology (ESMO) 2026 congress and accepted for publication in The New England Journal of Medicine, it showed the combination cut the risk of return or death by 42% versus Keytruda alone. Moderna and Merck’s treatment also lowered the risk of distant metastasis or death by 38% after a median follow-up of 24.6 months.
Patients on that treatment posted two-year recurrence-free survival of 82.2%, compared with 70% for Keytruda alone in the Moderna and Merck study. Those results surfaced on social media on October 22 before their formal release, drawing early attention to Moderna stock. Today’s gain is holding up despite the downgrade.
Moderna Moves Apart From Its Vaccine Peers
Oncology now drives how Moderna trades, even as its approved respiratory vaccines, including Spikevax and mRESVIA, remain tied to seasonal demand, and the debate centers on whether intismeran, an individualized neoantigen therapy, can extend beyond melanoma into lung, renal and bladder cancers. Colder, lower-mutation tumors carry biological and clinical risk for that approach, and a Phase 2 INTERPATH-004 trial in renal cell carcinoma, expected to read out in late 2026 or 2027, is the key binary test for the company. Lung and bladder cancers, where checkpoint inhibitors already work, may be friendlier ground for Moderna than pancreatic or gastric tumors.
Manufacturing is the other open question for Moderna. Panmure Liberum noted intismeran takes approximately six to eight weeks to make per patient. The firm argued the data supports the off-the-shelf DNA vaccine approach of U.K.-listed Scancell, which avoids patient-specific manufacturing. Moderna has been establishing capacity in Massachusetts with Merck for a potential intismeran launch.
Each of Moderna’s closest vaccine peers runs a different business model. Novavax sells a protein-based COVID vaccine and increasingly makes licensing and royalty income from its Matrix-M adjuvant, while BioNTech, which co-developed the Comirnaty COVID vaccine with Pfizer, is shifting hard into cancer drugs. Pfizer stock is at $30, down 0.7%.
Year to date, Novavax is up 53%, far behind Moderna’s surge, while BioNTech is down 8% over the same stretch and Pfizer is up 25%. That quiet trade among vaccine makers suggests Moderna is being valued on its cancer pipeline.
What Comes Next for Moderna’s Cancer Vaccine Push
Moderna now faces the question of whether regulatory filings in adjuvant melanoma lead to an approval with broad scope. Moderna’s renal cell carcinoma readout could then show whether intismeran works beyond melanoma. Watch for evidence that Moderna can scale individualized manufacturing, including at an upcoming tour of its facility in Marlborough, Massachusetts.
Supporters can cite peer-reviewed data and a path toward a potential new standard of care in melanoma for Moderna. On the other hand, the share price may already price in success well beyond melanoma, and more analysts could echo the valuation downgrade. Strong renal results could ease that concern, while a miss could undercut the expanded-indication case. A cautious approach could make sense while the market waits for intismeran’s renal cancer readout.
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk.His work has appeared in The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, TalkMarkets, Finmasters, 24/7 Wall St., and others.With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.