NVIDIA, AMD and Broadcom May Invest in Meta, Their Own Biggest Customer. What That Signals
When a company's biggest chip suppliers start buying equity stakes in their own best customer, something unusual is happening in the AI supply chain. The question is whether that bet signals confidence in Meta's spending spree or something far more…

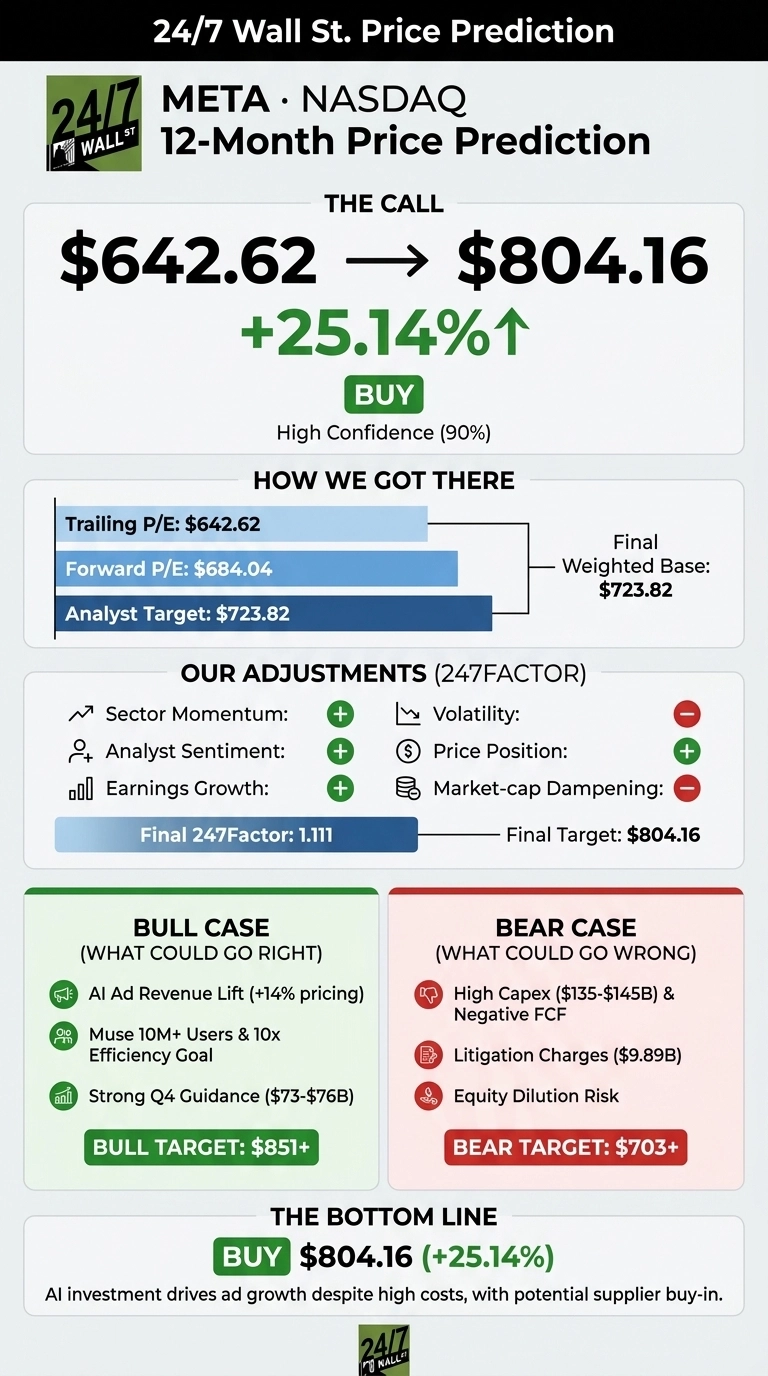
Our 24/7 Wall St. price target for Meta Platforms (NASDAQ:META | META Price Prediction) is $804.16 over the next 12 months. That means 25.14% upside from $642.62, and our model assigns the stock a buy rating.
| Metric | Value |
|---|---|
| Current Price | $642.62 |
| Price Target from 24/7 Wall St. | $804.16 |
| Upside/Downside | 25.14% |
| Recommendation | BUY |
| Confidence Level | 90% |

Meta is raising equity to fund AI spending through a large stock offering, and its suppliers NVIDIA (NASDAQ:NVDA), AMD (NASDAQ:AMD) and Broadcom (NASDAQ:AVGO) may take part.
These links already exist. Broadcom’s custom AI chip deal with Meta runs through 2029, and AMD’s agreement includes a warrant aligning Meta’s incentives with AMD’s success. If suppliers buy in, they are putting their own capital behind Meta’s demand for computing power.
Meta Slid After Free Cash Flow Turned Negative
Shares have fallen 9.42% in a week, 13.66% in a month and 2.43% year to date. The stock sits 17.6% below its $779.82 52-week high and 23.7% above its $519.37 low.
In Q3, revenue of $64.60 billion rose 26.07% and beat estimates. GAAP EPS of $3.83 missed expectations because of a $9.89 billion litigation charge. Without that charge, EPS would have been $7.40. Capex of $34.906 billion drove free cash flow to -$2.12 billion.

Why Bulls See $851 or More
AI is already raising Meta’s ad business. Ad pricing rose 14% and impressions grew 10%. Daily users reached 3.64 billion. Muse drew more than 10 million users in about six weeks, and management expects Muse’s computing cost efficiency to improve more than 10x within a year.
Q4 revenue guidance is $73 billion to $76 billion. Of the analysts covering the stock, 47 rate it Buy and 8 rate it Strong Buy, with a consensus target of $844.26. Our bull case is $850.99.

Spending and Litigation Risks Investors Should Track
Meta expects 2026 capex of $135 billion to $145 billion, compared with $72.215 billion in 2025.
Selling new shares dilutes existing holders, and more youth litigation trials are on the calendar. Our bear case is $703.14. To be fair, excluding the legal charge, Q3 operating income would have increased 11%.
Meta Trades Between Alphabet and NVIDIA on Valuation
Alphabet (NASDAQ:GOOGL) is the closest comparison: both run ad platforms and both are spending heavily on AI. Alphabet also had negative free cash flow of -$5.855 billion in Q2, yet it trades at only 14x earnings.
NVIDIA sells the computing Meta is buying and trades at 42x. Meta, at 23x, sits between the two, which makes our 24/7 Wall St. price target look reasonable.
| Company | P/E | Operating Margin |
|---|---|---|
| Meta | 23 | 41.44% |
| Alphabet | 14 | 32.06% |
| NVIDIA | 42 | 60.38% |
Meta Price Prediction 2026-2030
A buy rating is supported by the 24/7 Wall St. price target of $804.16 at 90% confidence. The key supporting factor is that ad pricing keeps rising. The outlook would strengthen if Muse starts producing revenue in 2027. It would weaken if capex keeps climbing while ad growth slows.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 (12-month) | $804.16 |
| 2027 | $816.32 |
| 2028 | $934.53 |
| 2029 | $1,073.74 |
| 2030 | $1,144.99 |
The projections rest on Meta continuing to execute on its current strategy. Results could land well above or below them depending on how Muse is monetized and how much dilution the offering creates.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.