One Number Could Tell Us Where Meta Stock Goes Next

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Our 24/7 Wall St. price target for Meta (NASDAQ:META | META Price Prediction) is $916.40 over the next 12 months. That implies 25.05% upside from a reference price of $732.82, and our model rates the stock a buy.
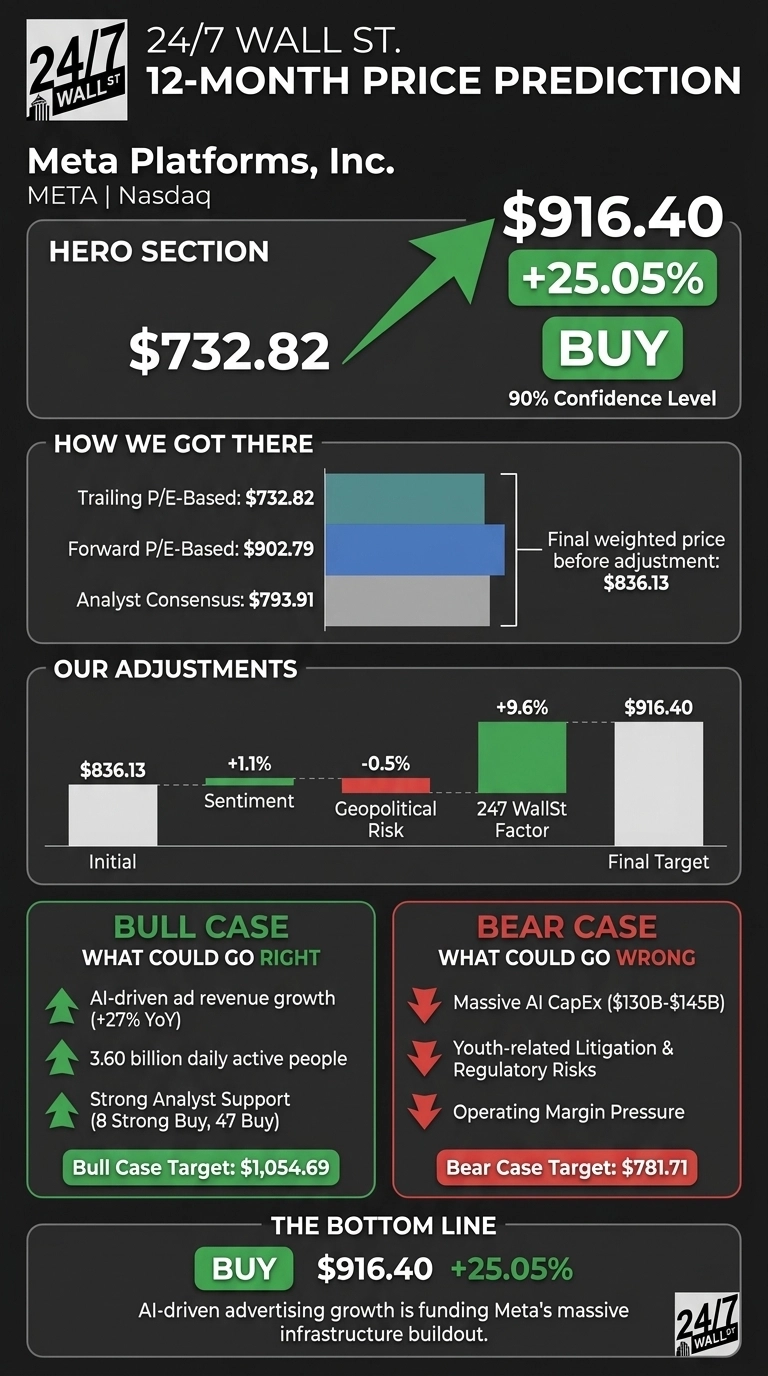
| Metric | Value |
|---|---|
| Current Price | $732.82 |
| 24/7 Wall St. Price Target | $916.40 |
| Upside/Downside | 25.05% |
| Recommendation | BUY |
| Confidence Level | 90% |

The number to watch is capital spending. Meta guided 2026 capex to $130 billion to $145 billion, up from $72.22 billion in 2025. If AI keeps ad revenue climbing at a 27% clip, the spending builds a moat. Our high confidence rests on near-unanimous analyst support and a forward multiple that looks reasonable.
A 26% Monthly Rally Runs Into Fresh AI Spending Jitters
Meta is up 26.3% over the past month and 10.79% year to date. It trades between a 52-week high of $779.82 and a low of $519.37. Shares fell this week on concerns about AI spending, even though Meta’s Muse agent was a September hit.
Q2 2026 earnings showed the same tension. Revenue of $60.80 billion rose 27.96% and beat estimates. Diluted EPS of $6.18 missed the $7.22 estimate. Operating margin fell to 31% from 43%, and free cash flow dropped to $784 million from $8.55 billion.

Why Bulls See $1,054 Ahead
AI is already paying off inside the ad engine. In Q2, ad impressions rose 14% and price per ad rose 12%. Meta’s Advantage Plus tools hit “over $75 billion in annual revenue run rate”, and model upgrades drove “a 15.7% uplift in conversions on Facebook.”
The apps reach 3.60 billion daily active people. More than 1 million businesses use Meta’s business agents every week. The finance chief also said Meta has “numerous ROI positive places” to put more compute.
Analysts are heavily bullish, with 8 strong buy, 47 buy, 7 hold and zero sell ratings. If that ad momentum holds, our bull scenario reaches $1,054.69.

What Could Go Wrong With a $145 Billion Budget
Long-term debt rose to $83.66 billion. Full-year expense guidance went to $165 billion to $169 billion. All of that buildout still has to be powered and cooled by somebody, and we pulled together seven suppliers doing exactly that in a free AI infrastructure guide.
Management warned that youth-related U.S. trials in 2026 may result in material losses. The Q2 miss included $2.40 billion in legal charges and $1.18 billion in severance. Management expects 2026 operating income above 2025 levels. Our bear scenario is $781.71.
Is Meta Pricier Than Alphabet and Pinterest?
Alphabet (NASDAQ:GOOGL) trades at 15x trailing earnings, compared with 27x for Meta. Its Q2 free cash flow was negative $5.855 billion. Meta’s faster ad growth and positive cash flow help justify its premium.
Pinterest (NYSE:PINS) is a pure social-ad peer that also sells AI-driven ad performance. Its revenue grew 18.17%, but it posted a GAAP operating loss of $55.198 million. Meta grows faster at far greater scale and earns a 41.44% operating margin. Next to Pinterest, our target looks reasonable.
| Company | Trailing P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Meta | 27 | 27.96% |
| Alphabet | 15 | 24.23% |
| N/A (GAAP loss) | 18.17% |
Meta Price Prediction 2026-2030
Our 24/7 Wall St. price target of $916.40 carries a buy rating and 90% confidence. Ad growth is paying for the buildout. View the stock favorably if Q3 revenue lands inside the $61 billion to $64 billion guidance and capex stays within its range. Grow cautious if spending guidance rises without faster ad growth.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $757.58 |
| 2027 | $938.61 |
| 2028 | $1,080.89 |
| 2029 | $1,219.81 |
| 2030 | $1,298.32 |
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.