Chamath Says Just 1% of Companies Drive 90% of AI Spending. Here’s Why That Matters for Your Portfolio
Chamath Palihapitiya just revealed where most AI revenue actually comes from, and the answer raises serious questions about how stable the entire AI supply chain really is for investors holding chipmakers, cloud stocks, or broad index funds.

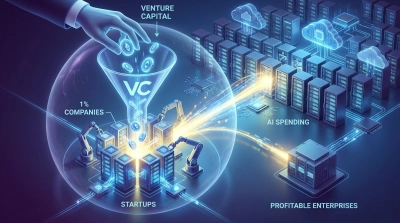
Chamath Palihapitiya has put numbers on the AI bubble debate, and they point to a narrow customer base. In an All-In podcast episode published October 23, 2026, Chamath Palihapitiya said 1% of companies account for 90% of AI spending. Chamath Palihapitiya added that 80% of that concentrated spending comes from unprofitable venture-backed startups. If most AI revenue traces back to companies that burn cash, then the revenue lasts only as long as investors keep writing checks.
In Palihapitiya’s own words: “So what I said was 1% of companies represent 90% of AI spending. So that’s tokens. And of that 90%, 80% of them are from unprofitable VC-backed companies.”
He offered the data in response to Griffin. Griffin, Citadel’s founder, said at his firm’s annual Future of Global Markets conference that AI is almost certainly a bubble. Griffin said he is bullish long term but worries companies are struggling to turn AI spending into productivity.
How Venture Money Turns Into AI Revenue
Palihapitiya walked through how the money moves: “VCs raised from pension funds and LPs and foundations and family offices. They put money into a startup; that startup takes that money and invests in growth.” When that startup needs more capital, it “raises a bunch of money from the same VCs. And it’s just this circularity.”
His conclusion ties back to Griffin: “For AI to really scale as a predictable driver of long-term earnings, it has to diffuse out of the startup ecosystem.”
Put simply, a big share of the tokens sold by model labs is paid for with venture dollars, and those labs then buy cloud capacity, while cloud providers buy chips, power, and buildings. Each supplier’s revenue depends on the one ahead of it in that chain.
What Happens to Suppliers If Funding Slows
Infrastructure plans now run far ahead of what profitable customers alone have shown they can pay for. On The AI Investor Podcast, 24/7 Wall St. noted that expected AI data center capital spending for 2026 had reached 845 billion, with 2027 expectations at nearly 1.4 trillion.
If venture funding tightens, unprofitable startups cut their token budgets first. Model labs would see revenue growth slow, reducing their computing orders, and the slowdown would reach cloud and hardware suppliers months later. The market has already reacted to that risk. During the same episode, a co-host noted that data center operator CoreWeave (NASDAQ:CRWV) had fallen 10% as tech sold off over capex concerns.
Why Open Source and Owned Data Centers Change the Math
Palihapitiya also said large enterprises are moving toward open-source models and building their own data centers. The All-In hosts gave an example in September. Trading firm Jane Street publicly announced $19 billion in cloud capacity contracts, including 6 billion with CoreWeave and 13 billion with Crusoe, while also using open source.
That matters because the profitable buyers Griffin wants to see arrive may direct their spending differently, and their money may go to computing capacity and free models, with fewer dollars paid per token to frontier labs. The winners from enterprise adoption could look quite different from today’s winners, which are funded by startup spending. Riding a boom like this is fine as long as you know what the exit looks like, which is the whole subject of our free bubble survivor’s handbook.
What Retirees Should Check in Their AI Exposure
Retirement-age investors often hold more AI exposure than they realize. Broad index funds, growth funds, and target-date funds lean heavily on the same chipmakers, cloud providers, and infrastructure names whose revenue Palihapitiya traced back to venture capital. Pension funds also sit at the top of his chain as limited partners in venture funds.
A few questions are worth asking:
- How much of your portfolio, across all your funds combined, depends on AI infrastructure spending?
- Could you avoid selling stocks for several years if AI names went through a long drawdown?
- Do your holdings include businesses that would benefit from enterprise adoption, such as companies that use AI to cut costs, along with the suppliers that sell to startups?
Our Takeaway
Palihapitiya’s numbers explain why AI supplier revenue can look strong and still be thin. As long as roughly 80% of top-tier spending comes from unprofitable startups, as Chamath Palihapitiya estimates, that revenue rises and falls with venture fundraising. Investors close to retirement should size their AI exposure for that risk. The signal to track is enterprise adoption: profitable companies paying for AI at scale, whether through open-source models, their own data centers, or frontier labs. Until that broadens, a meaningful share of the AI boom runs on venture money.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.