Supermicro Has Already Survived the AI Hype Cycle. What Comes Next?
Supermicro's revenue nearly doubled while its stock sat 80% below all-time highs, and a $60 billion order backlog trades at a valuation its rivals would consider a rounding error. Something in that equation does not add up.


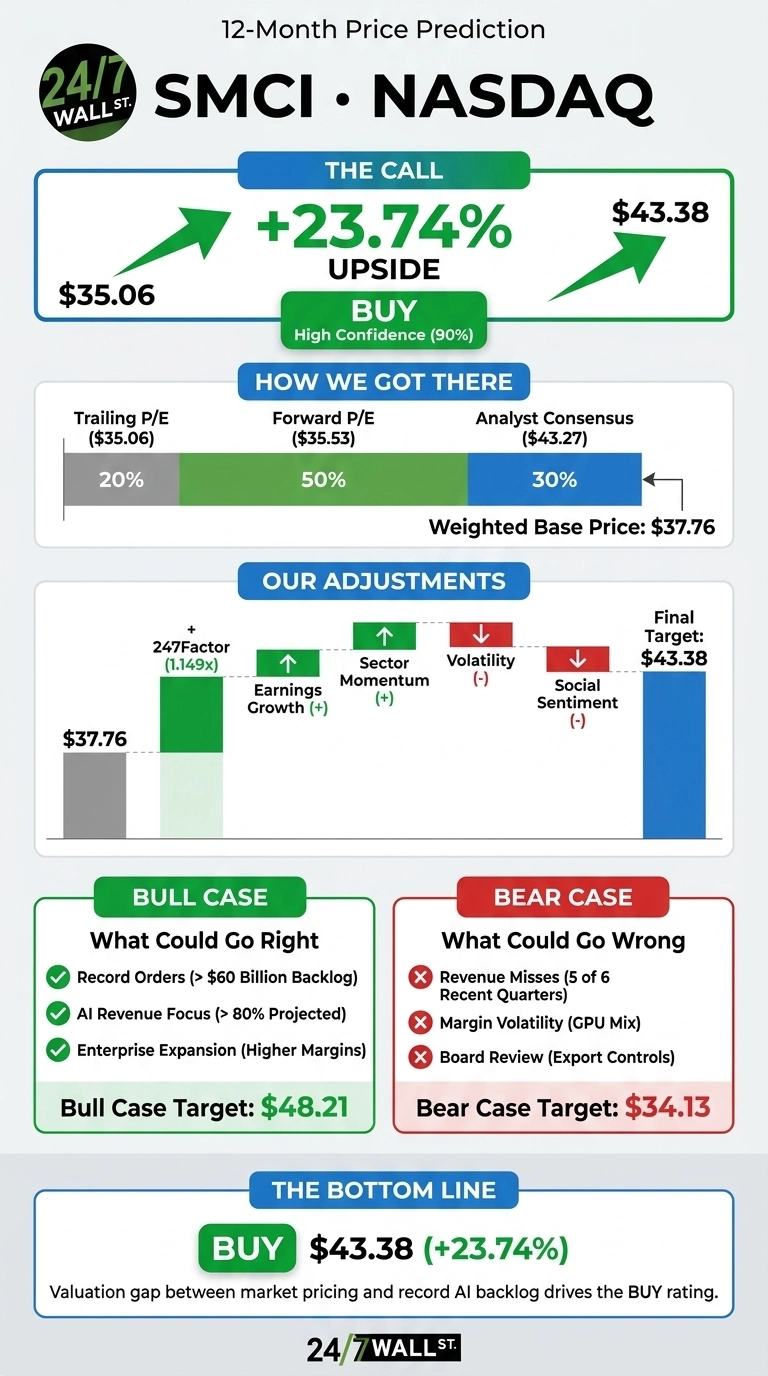
Super Micro Computer (NASDAQ:SMCI | SMCI Price Prediction) has come through a governance scare, a stock collapse and a full AI hype cycle, and its revenue nearly doubled along the way. Our 24/7 Wall St. price target for Supermicro is $43.38 over the next 12 months. That means 23.74% upside from $35.06.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $35.06 |
| 24/7 Wall St. Price Target | $43.38 |
| Upside/Downside | 23.74% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our model rates the stock a buy with high conviction. Supermicro trades at a trailing P/E of about 10x while guiding fiscal 2027 revenue to $65 billion to $72 billion.
To me, that gap between valuation and growth is the core of the story. The market is still pricing in the damage of the past two years, and the order book points somewhere else.

A Sharp Monthly Pullback Hides a Record Backlog
At noon the shares changed hands near $34.80. That is up 7.18% over the past week, down 19.56% over the past month, up 18.89% year to date and down 32.52% over the past year.
The stock sits about 35% below its 52-week high of $54.08 and roughly 80% above its low of $19.48. On October 27, it outperformed competitors on a strong trading day.
For fiscal Q4, revenue came in at $11.12 billion, up 93.2% year over year but short of the $11.56 billion consensus. Non-GAAP EPS of $1.70 exceeded the $0.96 estimate, and non-GAAP gross margin rose to 17.6% from 10.1% in Q3. CEO Charles Liang called the revenue shortfall “purely a timing story”.
Why Bulls See $48 and Beyond
Management reported over $60 billion in new orders, and Liang described about 70% of them as pure AI. Q1 guidance calls for $14.5 billion to $15.5 billion in revenue.
The Data Center Building Block Solutions (DCBBS) push adds software and services, and Liang said a “twenty percent of gross profit” contribution is close. Rack capacity is heading past 6,000 per month.
Supermicro is one of several picks-and-shovels names behind the AI data-center expansion (we rounded up seven of them, from power to cooling to servers, in a free report you can grab here).
Funds added in Q2: Renaissance Technologies raised its stake 113%, and Balyasny opened a new position. Our bull case is $48.21.

What Could Derail the Recovery
Revenue has missed estimates in five of six recent quarters. Q1 gross margin guidance of 10.4% to 10.8% shows that part of Q4’s jump will not last. Fiscal 2026 operating cash flow was -$6.81 billion, and the board’s review of export-control transactions is still open.
Analysts lean cautious, with 11 Holds against 3 Sell-side ratings. On the other side, Q4 free cash flow turned positive at $722 million, and net debt fell to $1.2 billion from $7.5 billion. Our bear case is $34.13.

Supermicro Trades at a Deep Discount to Dell and HPE
| Company | Trailing P/E | Gross Margin |
|---|---|---|
| Supermicro | 10x | 10.82% |
| Dell | 27x | 20% |
| HPE | 1,417x | 28.8% |
Dell Technologies (NYSE:DELL) is Supermicro’s most direct AI server rival. It carries a $95 billion AI backlog and trades near 27x earnings. Dell’s fatter gross margin explains part of that premium, but nowhere near all of it.
Hewlett Packard Enterprise (NYSE:HPE) competes for the same enterprise server buyers. Its server revenue grew 35.3% to $6.77 billion, though Juniper integration costs distort its trailing P/E. At our target, Supermicro’s means P/E of about 10x still sits far below both peers, so the target looks conservative.
A Discount This Wide Is Hard to Ignore
Our 24/7 Wall St. price target of $43.38 comes with a buy rating and 90% confidence. What tips the scale is the record backlog set against a single-digit forward multiple.
I’d find the case firmer if gross margins hold above 10% while revenue grows. I’d step back if revenue misses keep piling up or the board review turns up something serious. At these levels, the model considers the backlog more heavily than the risks.
Supermicro Price Prediction 2026-2030
Here is where the 24/7 Wall St. price target model projects Supermicro could trade if current growth trends and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $37.74 |
| 2027 | $43.38 |
| 2028 | $49.46 |
| 2029 | $54.11 |
| 2030 | $61.39 |
These projections assume Supermicro keeps executing on DCBBS and its AI backlog. Margin swings, customer data-center delays or the outcome of the board review could push results well above or below this path.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.