Alphabet is Even Further Misunderstood Following Earnings and I’m Loading Up
Wall Street saw a massive earnings miss and hit the sell button. I read the footnotes, checked what the actual businesses returned, and opened my wallet instead.

I added to my Alphabet (NASDAQ:GOOGL | GOOGL Price Prediction) position again on Thursday. The stock fell 12.64% to $283.82 that day, which CBS News called its worst day since the company went public. My reason for buying hasn’t changed. Alphabet controls where billions of people search, watch, and now work with AI, and it keeps turning that reach into faster-growing, more profitable businesses. This sell-off lets me buy that same company at a lower price.
One Accounting Line Explains the Miss
Wall Street focused on GAAP EPS of $2.12 against a $2.97 estimate. That was a 28.52% miss, and it ended a 12-quarter run of beats. I focused on the footnote. Alphabet reported an $8.70 billion loss on equity securities, which cut net income by $6.70 billion and reduced EPS by $0.55. Other income shifted to a net loss of $8.22 billion from a $12.76 billion gain a year earlier. Investment values move with the market. They tell me little about how Google’s businesses are running.
The businesses ran hot. Operating income rose 29.93% to $40.58 billion. Revenue climbed 24.6% to $127.58 billion, the 13th consecutive quarter of double-digit growth.
Three Reasons I Keep Adding
Google Cloud comes first. Revenue grew 103% to $30.71 billion, and segment operating income reached $11.12 billion versus $3.59 billion a year ago. CEO Sundar Pichai pointed to “strong demand for our TPU systems across a wide range of customers.” Alphabet sells its own AI chips alongside its cloud capacity, and having that whole stack is why I keep coming back.
Second, Search keeps growing alongside AI. Search and other revenue rose 12% to $63.35 billion. Pichai said query growth is “the highest it’s been in the last five years.” The Gemini app reached 1 billion users.
Third, the balance sheet pays for all of it. The debt-to-equity ratio stands at 0.143, interest coverage at 175.5x, and return on equity at 35.7%. The stock’s trailing earnings multiple is 13. I discount that multiple because equity gains inflated earlier quarters, including Q2 EPS of $9.11. I apply the same one-time logic in both directions, and operating income still shows a business that keeps growing. For income, the $0.22 quarterly dividend was raised 5% this year and yields 0.60%.
Why Alphabet Gets My Money Over Microsoft and Amazon
The obvious AI cloud alternatives are Microsoft (NASDAQ:MSFT) and Amazon (NASDAQ:AMZN). Microsoft carries an earnings multiple of 29, and Azure grew 48% last quarter. Amazon carries an earnings multiple of 34, and AWS grew 39%. Google Cloud grew faster than both, and its parent costs me the lowest multiple of the three. I’ll take the faster grower at the cheaper price.
Risk I Watch Closely
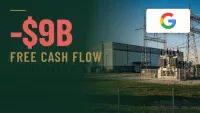
Spending is the real risk. Capital expenditures rose 114.4% to $51.36 billion, which drove free cash flow to negative $9.07 billion. Alphabet covered the gap by issuing $28.7 billion in senior notes. The company also sold 12 million Class A shares and 24 million Class C shares through its at-the-market program, which still has $27.6 billion available. That reduces my stake and adds interest expense. CNBC described the quarter as AI taking a bite out of search. If this spending doesn’t pay off, I own the consequences.
My thesis holds because the spending already produces profits. Operating cash flow reached $42.29 billion this quarter, and Alphabet generated $73.27 billion of free cash flow in fiscal 2025. Cloud profits show the expansion turning into earnings.
What Keeps My Buy Button Active
The stock sits 16.75% below where it traded a month ago and is down 9.15% year to date, even as operating income and Cloud revenue sped up. Pichai now describes a “half-trillion dollar revenue run rate.” Over 10 years, the shares rose 607.59%. The market read this quarter wrong, and every share I add at this price buys more of the business the market missed.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.