Prediction: This Could Be the AI Comeback Story of the Decade
Salesforce stock is down for the year yet something beneath the surface is accelerating at a pace that has 38 analysts turning bullish and one model projecting a path to targets that stretch well past current Wall Street consensus.


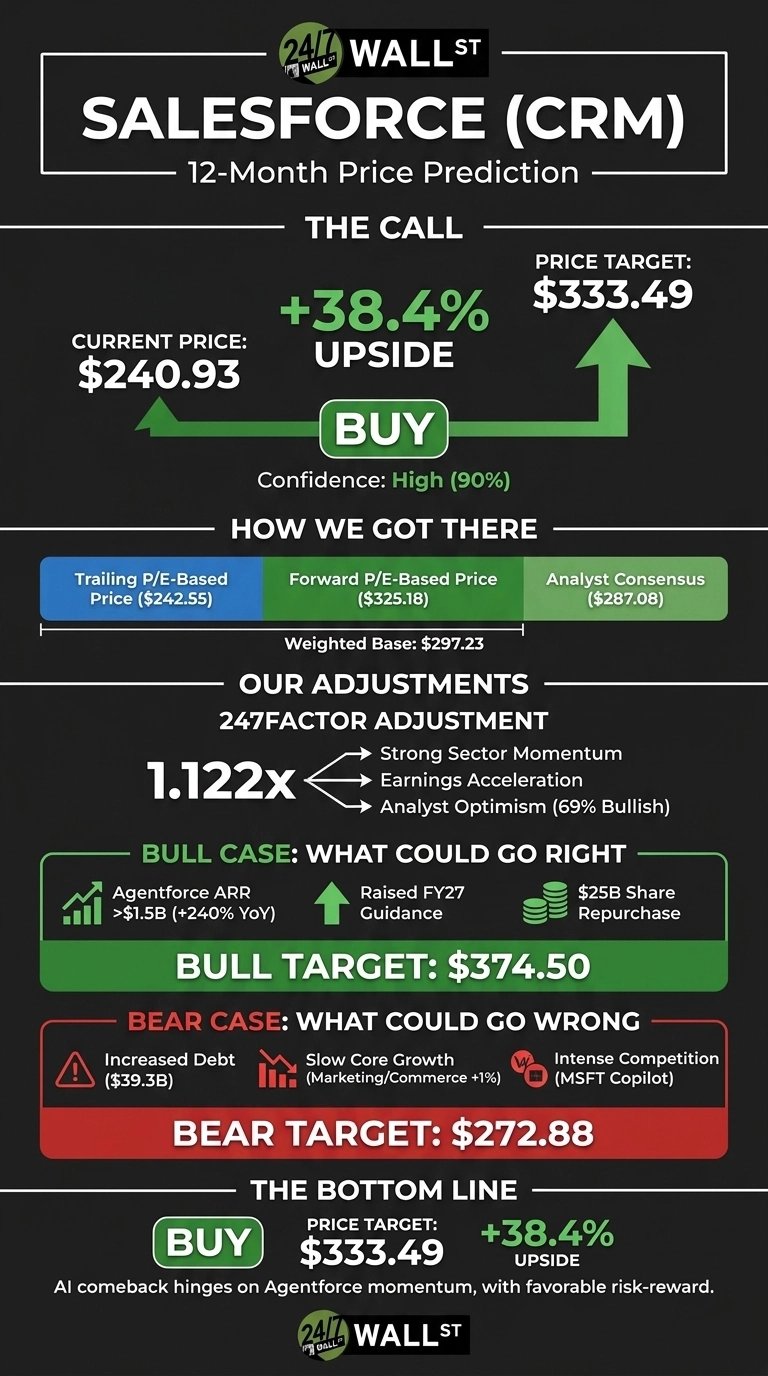
The 24/7 Wall St. price target for Salesforce (NYSE:CRM | CRM Price Prediction) is $333.49 over the next 12 months. From the current price of $240.93, that works out to 38.4% upside. The stock earns a buy rating with high confidence from the model.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $240.93 |
| Price Target: 24/7 Wall St. | $333.49 |
| Upside/Downside | 38.4% |
| Recommendation | BUY |
| Confidence Level | 90% |
Salesforce’s comeback hinges on Agentforce. Agentforce annual recurring revenue (ARR) has passed $1.5B, up over 240% YoY, and management raised guidance in August.
Even so, the stock is down 8.41% this year and trades at about 16x forward earnings. That multiple understates a business whose growth is speeding up.

A 33% Rally Since July Puts Salesforce Back on the Map
Shares are up 32.96% since late July and up 2.95% over the past month. They slipped 0.62% this week and trailed competitors on Tuesday. The stock sits 10.0% below its 52-week peak of $267.80, yet 65.0% above the low of $146.06.
Second-quarter fiscal 2027 revenue came in at $11.345B, up 10.8%, ahead of the $11.316B estimate. Non-GAAP EPS of $5.90 beat the $3.27 consensus, though $2.53 per share of that came from gains on strategic investments.
Current remaining performance obligations (cRPO), which track signed revenue due over the next 12 months, rose 14% to $33.50B. Full-year revenue guidance moved up to $46.1B to $46.4B.

Why Bulls See $374 Ahead
Agentforce and Data 360 together have reached about $3.90B in ARR, up over 210%. Agentic Work Units, a measure of the tasks AI agents complete, hit 3.2B in Q2, up 97% Q/Q. Chief operating officer Miguel Milano said agentic customers “are already at double the AOV with a perspective of nearly quadrupling”. AOV is annual order value.
A $25B accelerated share repurchase brought the diluted share count down to 821M from 962M, and management still targets $63B in revenue by fiscal 2030.
Wall Street mostly agrees: 38 analysts have bullish ratings on the stock, with a consensus target of $287.08. The bull case reaches $374.50.

Debt and Slow Core Growth Are the Risks Worth Watching
Noncurrent debt rose to $39.3B to pay for the buyback. Marketing and Commerce grew just 1%, and operating income was flat. Free cash flow growth is guided to only 4% to 5% for the year.
Copilot from Microsoft (NASDAQ:MSFT), now at more than 30 million paid seats, is a real competitive threat. Meanwhile, Q2 free cash flow rose 81.5%, and flat profits partly reflect Informatica integration and $94M in restructuring charges. Even our bear case of $272.88 sits above today’s price.
Salesforce Trades at an Oracle Multiple With Microsoft-Level Cash Flow
Microsoft competes directly with Salesforce through Dynamics 365 and Copilot. Shares trade at 27x forward earnings and 58.90x free cash flow, and revenue grew 17.8% last quarter.
Oracle (NYSE:ORCL) sells competing enterprise applications. Its forward multiple of 16x matches Salesforce’s, but heavy AI data center spending drive free cash flow to negative $5.396B last quarter.
| Company | Forward P/E | Latest Revenue Growth |
|---|---|---|
| Salesforce | 16x | 10.8% |
| Microsoft | 27x | 17.8% |
| Oracle | 16x | 29.61% |
At 13.77x free cash flow, Salesforce is the cheapest of the three on cash generation. Compared with these peers, our target looks reasonable, and arguably conservative.
Agentforce Momentum Tips the Scale
The 24/7 Wall St. price target is $333.49, with a buy rating and 90% confidence. The key factor is AI ARR compounding at triple-digit rates while the stock trades at a single-digit-growth multiple.
I would grow more confident if organic revenue picks up again in the second half, as management has promised. I would get more cautious if Agentforce growth stalls or debt starts pressuring cash returns. For now, the risk-reward looks favorable.
Looking further out, here is where our model projects Salesforce could trade if current growth and market conditions hold.
| Year | Price Target: 24/7 Wall St. |
|---|---|
| 2026 | $261.97 |
| 2027 | $333.49 |
| 2028 | $410.24 |
| 2029 | $472.50 |
| 2030 | $542.43 |
The projections rest on Salesforce continuing to execute on its agentic strategy. Faster AI monetization could drive the stock higher than these figures, while losing ground to Microsoft could drive it lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.