Salesforce Is Betting Big on AI. The Payoff Could Be Bigger Than Investors Expect
Salesforce's AI products are growing at triple-digit rates while the stock sits near a 52-week low, and that gap between momentum and valuation may be exactly what the market keeps getting wrong.


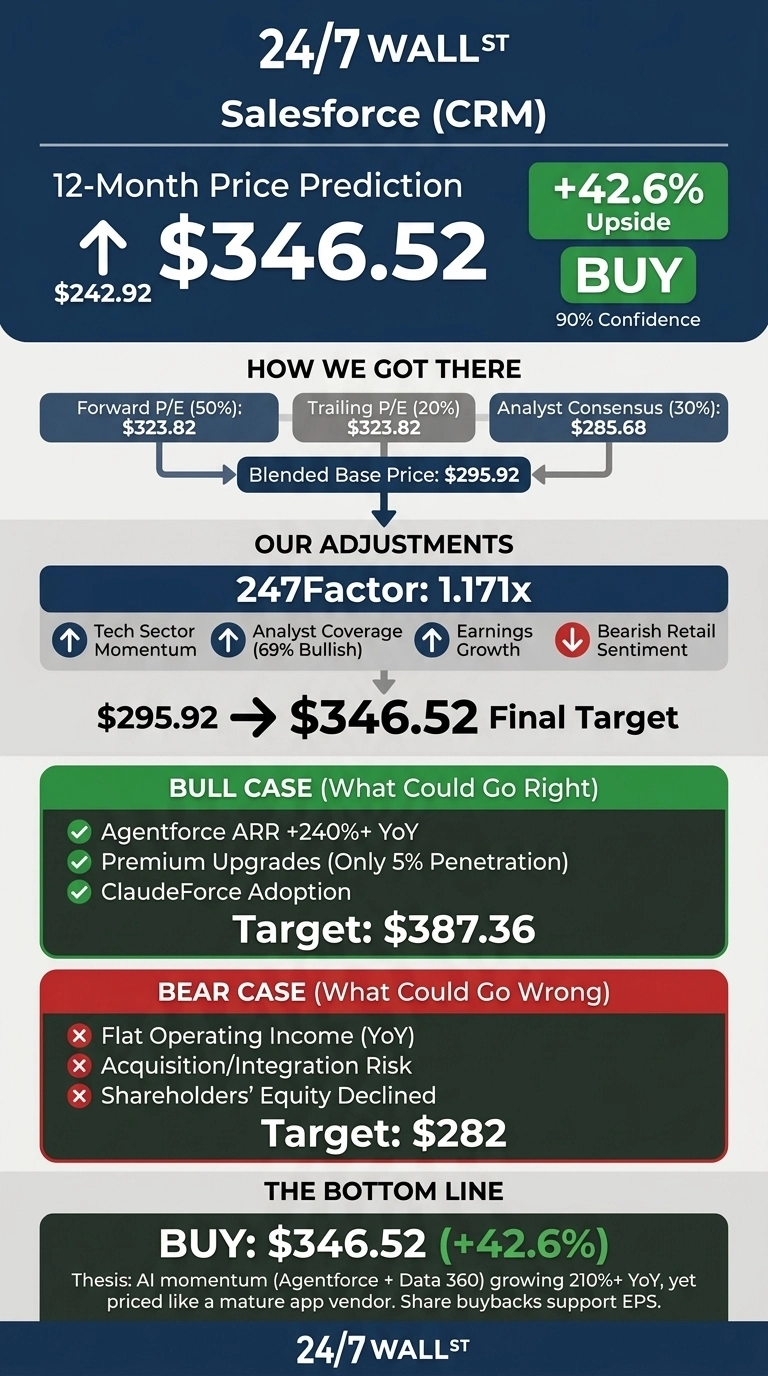
The 24/7 Wall St. price target for Salesforce (NYSE:CRM | CRM Price Prediction) is $346.52 over the next 12 months. Shares trade at $242.92, so the target implies about 42.6% upside.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $242.92 |
| Price Target from 24/7 Wall St. | $346.52 |
| Upside/Downside | 42.6% |
| Model Rating | BUY |
| Confidence Level | 90% |

Our model has high confidence in that rating. The thesis comes down to one point: Agentforce and Data 360 are growing much faster than the share price reflects, and a large buyback keeps reducing the share count.
The market still prices Salesforce like a mature app vendor. The AI numbers point to something more.
Braze Deal Revives the Cost Debate After a Choppy Year
Over the past week shares rose 2.06%, and over the past month they gained 2.1%. They are still down 7.65% year to date. The stock trades 9.3% below its 52-week high of $267.80 and 66.3% above its low of $146.06. On Tuesday, Salesforce announced a deal to buy Braze (NASDAQ:BRZE), and the stock fell as investors balked at the price tag (MarketWatch).
Second-quarter fiscal 2027 revenue came in at $11.345B, +10.8% YoY, beating consensus. Non-GAAP EPS of $5.90 exceeded the $3.27 estimate, although about $2.53 per share came from gains on strategic investments. Management raised full-year revenue guidance to $46.10B-$46.40B.
Why Bulls See $387 Within Reach
Agentforce ARR passed $1.5B, +240%+ YoY, and combined Agentforce and Data 360 ARR reached about $3.9B. Agentic Work Units hit 3.2 billion in the quarter, up 97% sequentially. Only 5% of eligible knowledge workers have moved to premium editions, which carry a 60% to 80% premium.
That leaves a long time for upgrades, and ClaudeForce requires premium editions. Analyst sentiment is positive too: 6 strong buy and 32 buy ratings against a consensus target of $285.68. The bull case reaches $387.36.

Acquisition Costs and Flat Profits Could Stall the AI Payoff
Operating income was $2.331B (flat YoY), and restructuring charges rose to $94M vs $4M. Free cash flow is expected to grow only ~4-5% this year. Shareholders’ equity fell 37.42% after the debt-funded buyback.
Integrating Informatica, Contentful, Fin and now Braze also adds execution risk. On the other side, the buyback cut diluted shares to 821M from 962M at an average price of $176 per share, and that will boost per-share earnings. The bear case of $282 still stands above today’s price.
Salesforce Trades Cheaper Than Microsoft and Generates More Cash Than Oracle
Microsoft (NASDAQ:MSFT) competes head-on through Copilot and Dynamics. Its AI run rate hit $37 billion, yet it trades at 30x earnings and 59x free cash flow. Salesforce trades at 27x and 13.85x.
Oracle (NYSE:ORCL) shows the capital-heavy path to AI. Revenue grew 29.61%, but free cash flow was -$5.396B. Next to these two, our 24/7 Wall St. price target looks reasonable.
| Company | Trailing P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Salesforce | 27x | 10.8% |
| Microsoft | 30x | 17.75% |
| Oracle | Not available | 29.61% |
AI Momentum Supports a BUY Rating
The 24/7 Wall St. price target of $346.52 comes with a buy rating at 90% confidence. The deciding factor for me is AI revenue growing past 200% while the stock trades at 16x forward earnings (the same AI expansion is raising a whole group of suppliers we profiled in a free report on seven AI stocks that aren’t chipmakers).
My view improves if premium-edition upgrades speed up. It weakens if deal costs keep operating income flat.

| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $252.93 |
| 2027 | $346.52 |
| 2028 | $443.40 |
| 2029 | $536.67 |
| 2030 | $594.23 |
The projections assume Salesforce keeps executing on its current strategy. The biggest key factors are how quickly Agentforce consumption grows and whether the acquisitions integrate smoothly.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.