International Paper Yields 5.5%, but Free Cash Flow Just Turned Negative
International Paper's 5.5% yield looks attractive until you examine where the dividend money is actually coming from. With free cash flow negative and capital spending elevated for years ahead, the math behind the payout deserves a closer look.


International Paper (NYSE:IP | IP Price Prediction) yields 5.54% with shares at $36.22. Its third-quarter report on Oct 28, 2026 showed the company spending more cash than it brought in. Free cash flow was $(267)M: operating cash flow of $339M could not cover $606M of capital spending.

A Payout Frozen Since Its Last Cut
The quarterly dividend has been $0.4625 since 2021, when it was cut from $0.5125. The next ex-dividend date is November 16, 2026.
Coverage in 2025 was thin. The company lost $3.516 billion, much of it from a $2.47B pre-tax non-cash goodwill impairment on its European unit. Operating cash flow of $1.698 billion fell short of capital spending of $1.857 billion, which left free cash flow at $(159)M. Even so, cash dividends paid rose to $977 million from $643 million in 2024. That means every dollar of the 2025 dividend was paid from money other than free cash flow (the same kind of mismatch we flagged in a free guide to the seven warning signs a big yield may be headed for a cut).
Why the Dividend Bill Got Bigger
The per-share rate didn’t change, so the bigger bill came from more shares. International Paper bought DS Smith in an all-share deal that closed Jan. 31, 2025. Every new share issued to DS Smith holders receives the same quarterly payment.
2026 Free Cash Flow Still Falls Short
Chief Financial Officer Lance Loeffler explained the third-quarter shortfall on the earnings call:
“This reflected cash payments for the second quarter’s heavy maintenance spending, annual interest payments on legacy DS Smith debt, and an inventory build following our planned outage season. For the full year, we expect to generate free cash flow of approximately $100 to $200 million.”

That range is far below what the dividend costs. Spending relief also looks a long way off. CEO Andy Silvernail said capital spending in 2027 should look like 2026:
“We’ve said that we’re going to be elevated in North America here for a couple more years.”
How Two Packaging Rivals Compare
Smurfit Westrock (NYSE:SW) brought in $874 million of third-quarter operating cash flow against $514 million of capital spending. It kept its quarterly dividend at $0.4523 and plans about $5 billion in dividends from 2026 to 2030. Packaging Corporation of America (NYSE:PKG) posted adjusted EPS of $3.04, ahead of the $2.9173 estimate, exceeding expectations. Revenue rose 12.46%, and capital spending was $247.3 million. Packaging Corp.’s CEO said, “Our mills ran at full capacity during the quarter.” Both rivals are paying for their dividends with cash from operations, which International Paper cannot yet do.
What Has to Improve
North America is turning. Operating profit there reached $427M, compared with a $(166)M loss a year earlier. Management expects fourth-quarter adjusted EBITDA of $700-$740M for the region. Silvernail put it this way:
“Our confidence in future profitable growth is grounded in what we have accomplished and the actions already underway, not an assumption that the environment will get easier.”
Three things would make the payout comfortable: capital spending comes down, Riverdale reaches full output, and price increases offset higher costs. The EMEA split adds a fourth piece. International Paper plans to keep about a 20% stake in DS Smith and will share its capital allocation plans after the separation. DS Smith’s Capital Markets Day is on Nov 3, 2026.
Can International Paper Keep Paying Its Dividend?
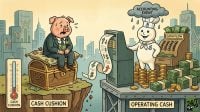
International Paper can keep paying the dividend for now. Cash stands at $815M, and management has not indicated a change. Right now, though, the money is coming from the balance sheet, because free cash flow does not cover the payout. Fourth-quarter free cash flow is the next figure to watch. The company needs a strong fourth quarter to reach its $100 to $200 million full-year target, and that result will show whether cash flow is starting to support the dividend.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.