Palantir Is Down 11% Over 12 Months: This Wall Street Pro Says 50% Gains to Come Over Next 12 Months as Momentum Rises
Palantir took investors on a brutal ride this year, but the analyst with Wall Street's highest target sees the pain as a setup for something bigger. Here is what the numbers say about whether the bulls or the skeptics have…

Palantir Technologies (NASDAQ:PLTR | PLTR Price Prediction) is now trading at $178.34. The average analyst price target is $212.50, suggesting about 19.2% of upside.
Palantir sells the Foundry, Ontology and AIP platforms that governments and large companies use to run AI on their own data. Investors watch closely because the company pairs rapid revenue growth with real profits. Third-quarter revenue rose 95.9% year over year to $2.31 billion, and its Rule of 40 score reached 158%.
The Street-high target points much higher. Barclays analyst Anthony Valentini has the Street-high target of $265.00, which implies roughly 48.6% upside. That puts his call close to 50%.
A 50% Round Trip Left Palantir Down 11% in a Year
Valuation did most of the damage. Shares traded near $207 a year ago and then lost 50% of their value before recovering, a technician noted on CNBC’s Fast Money. A drawdown that sharp is severe even for a high-growth stock. It came as investors repriced a stock at a P/E near 252. The 52-week range runs from $106.37 to $212.94.
The most recent drop came this week. Shares fell 10.31% over the past week and 3.13% when earnings arrived. Stock-based compensation is a concern, having risen to $318.9 million from $172.3 million. They also flag total contract value growth of 6% and accounts receivable of $1.88 billion, up from $1.04 billion at the end of last year.
Barclays, J.P. Morgan and Rosenblatt Hold Targets of $260 or Higher
Valentini’s thesis rests on three pillars. The first is AIP commercial expansion driven by bootcamp onboarding. The second is continued growth in U.S. government contracts, and the third is operating leverage that turns high margins into free cash flow (Barclays thesis). J.P. Morgan’s Brian Essex started coverage at Overweight with a $262.00 target, and Rosenblatt’s John McPeake keeps a $260.00 target. McPeake says Palantir is producing earnings and free cash flow “in spades”.
The latest quarter supports that view. U.S. commercial revenue rose 148% to $984 million and passed U.S. government revenue of $953 million for the first time. Adjusted EPS of $0.44 beat the $0.41 estimate, the company’s 10th straight beat. Management raised full-year revenue guidance to $8.530 billion to $8.534 billion.
Analyst ratings lean bullish, with a minority of Holds and Sells:
- Buy or Strong Buy: 20
- Hold: 9
- Sell: 1
- Strong Sell: 1
Estimates keep moving higher. The 2027 EPS consensus is $2.3445, up from $2.0945 90 days ago. Even so, the forward P/E stands at 86. Price targets are opinions and come with no guarantee.
Snowflake and MongoDB Fell Harder This Week, and Their Targets Sit Further Away
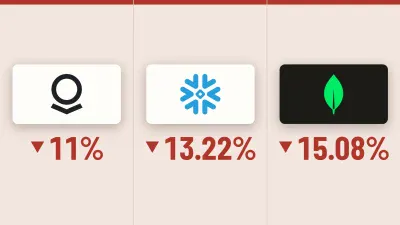
The selloff hit the whole group. Snowflake (NYSE:SNOW) fell 13.22% over the week but is still up 5.75% over 12 months. Its price of $290.49 against a $426.50 average target implies 46.8% upside. Analysts give it 45 Buy or Strong Buy ratings, six Holds and one Sell.
MongoDB (NASDAQ:MDB) dropped 15.08% over the week and 8.17% over a year, the path closest to Palantir’s. With the stock at $330.43 and a target of $452.50, the implied upside is 36.9%. It has 32 Buy or Strong Buy ratings and nine Hold ratings, with no Sell ratings.
Snowflake has the largest consensus upside of the three. Palantir has the lowest, and only the Street-high target brings it into Snowflake’s range.
Palantir Trails the S&P 500 While Holding Its 200-Day Average
At $178.34, Palantir has 19.2% implied upside to the $212.50 consensus set by 31 analysts. Shares are down 11.04% over one year, while the S&P 500 is up 10.28%. Year to date, Palantir is up 0.33% and the index is up 10.3%.
The moving averages send a mixed signal. The stock trades below its 50-day average of $186.90 but well above its 200-day average of $153.57.
Palantir’s Fundamentals Earn the Benefit of the Doubt
I’d find Palantir attractive here if U.S. commercial growth keeps running in triple digits and contract value starts to catch up with revenue. That would support the $4.8 billion to $5.0 billion free cash flow guidance and leave room to move toward $265. But I’d grow more cautious if receivables keep growing faster than collections and stock compensation keeps diluting shareholders. At a forward P/E of 86, a single slowdown could undo the recovery (riding a stock priced at the top of its range works until it doesn’t, which is the whole point of our free bubble survivor’s handbook).
On balance, I lean cautiously bullish. Raised guidance and rising estimates count for more than this week’s drop. Still, Palantir’s lowest consensus upside leaves it with less valuation buffer than Snowflake if growth stocks keep falling.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.