Intel Just Delivered Its Strongest Data Center Growth in 15 Years. Its Comeback Is Gaining Momentum
Intel's data center business just posted its best growth in over a decade, yet shares cratered in premarket trading on a combination of soft guidance and a factory incident. Here is why the selloff may be creating an opportunity most…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Intel (NASDAQ:INTC | INTC Price Prediction) is indicated at $68.25 in premarket trading, down 25.87% from Thursday’s $92.07 close after its third-quarter report. The 24/7 Wall St. price target is $98.57, which implies 44.4% upside. Our model rates the stock a buy with high confidence.
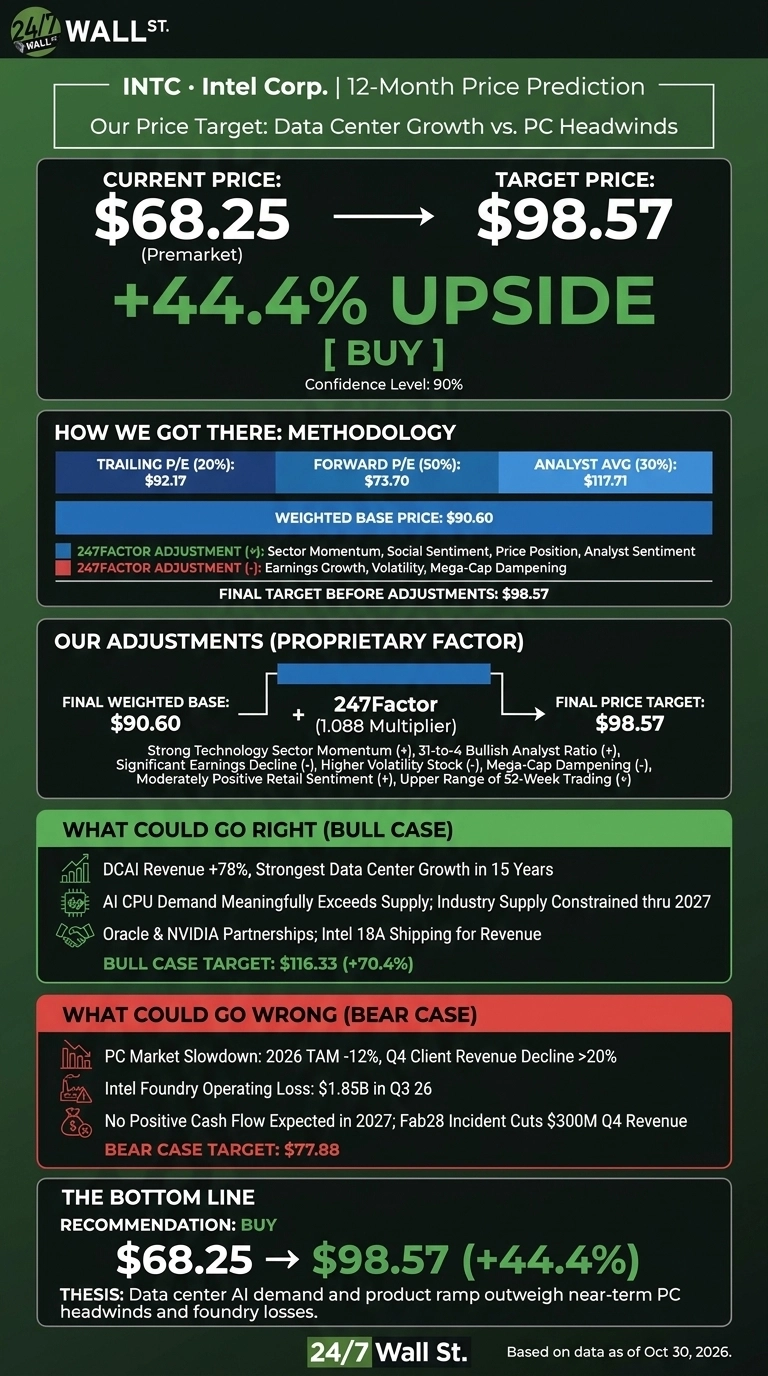
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price (Premarket) | $68.25 |
| Price Target — 24/7 Wall St. | $98.57 |
| Upside | 44.4% |
| Recommendation | BUY |
| Confidence Level | 90% |

Our model inputs were set before the post-earnings drop, which explains the wide gap. The selloff hit despite Data Center and AI (DCAI) revenue of $7.318 billion, up 78%, which Intel called its strongest growth for the segment in 15 years.
Investors focused instead on fourth-quarter guidance of $15 billion to $16 billion in revenue and $0.25 in non-GAAP EPS.
A 78% Data Center Surge Collided With a Soft Fourth-Quarter Outlook
Shares are down 20.17% over the past week and 41.13% over the past month, yet they remain up 84.96% year to date. The stock sits 52% below its $142.35 52-week high.
Revenue reached $16.513 billion, up 20.95%, and non-GAAP EPS of $0.52 exceeded the $0.3953 consensus. Intel’s earnings added fuel to a broader tech selloff Friday (per the WSJ). The reason: Intel expects client revenue to fall greater than 20% sequentially, and an incident at Fab28 will cut about $300 million from fourth-quarter revenue.

Why Bulls See $116 Ahead
Demand for CPUs is outpacing supply. Intel expects industry server CPU units to grow more than 30% in both 2026 and 2027. Clearwater Forest, its first Intel 18A server chip, is shipping for revenue, and Diamond Rapids is on track to scale in 2027.
Oracle (NYSE:ORCL) signed a multiyear deal to expand Xeon compute, and NVIDIA (NASDAQ:NVDA) picked Xeon 6 as the host CPU for its DGX Rubin NVL8 systems. CFO David Zinsner said Intel has “line of sight to long-term double-digit revenue growth with meaningful leverage and improving margins.”
Wall Street’s $117.71 consensus target rests on 14 Buy ratings and 1 Strong Buy. The bull case reaches $116.33, or 70.4% upside.

PC Weakness and Foundry Losses Could Stall the Rally
Intel expects the PC market to shrink by about 12% in units in 2026 and roughly 10% in 2027. Intel Foundry posted a $1.85 billion operating loss, and management does not expect positive cash flow in 2027 as spending rises.
The bear case sits at $77.88, a level set from the pre-selloff price. The premarket drop suggests the market is already pricing in something harsher. Still, the Fab28 hit looks temporary, and management is aiming at least 20% ROI on the nodes this spending funds.

Is Intel Cheaper Than AMD and NVIDIA?
Advanced Micro Devices (NASDAQ:AMD) is Intel’s direct x86 server rival. Its data center revenue grew 107% last quarter, and it trades at a 213 P/E.
NVIDIA sets the bar for AI compute and invested $5 billion in Intel stock. It trades at a 43 P/E with far fatter margins. Intel’s margin gap explains its discount. At roughly 33x forward earnings, the peer group makes our target look reasonable.
| Company | P/E | Gross Margin (TTM) |
|---|---|---|
| Intel | 33 (forward) | 34.77% |
| AMD | 213 | 49.5% |
| NVIDIA | 43 | 71.1% |
What Could Drive Intel’s Rebound
The 24/7 Wall St. price target of $98.57 carries a buy rating at 90% confidence. Data center demand that management says still exceeds supply is the deciding factor.
The key signal is whether DCAI grows by the mid-teens percent sequentially as guided for the fourth quarter. Widening Foundry losses or a PC decline that runs past mid-2027 would weaken the case. At this price, the model sees more upside than downside.
Our model projects Intel could trade at this level, assuming current trends hold.
| Year | Price Target — 24/7 Wall St. |
|---|---|
| 2026 | $98.57 |
| 2027 | $96.40 |
| 2028 | $103.03 |
| 2029 | $113.31 |
| 2030 | $114.14 |
The 2026 figure is our 12-month target. Intel would need to keep executing on 18A and adding server supply for these projections to hold. Winning external Intel 14A foundry customers could send results well above this path, while a deeper PC downturn could push them below it.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.