Intel’s Make-or-Break Moment Is Here. What Happens to INTC Stock Next?
Intel just posted its strongest revenue growth in fifteen years, yet the stock carries a beta that turns any road to recovery into a white-knuckle ride. Here is what the numbers reveal about how much further this rally can actually…

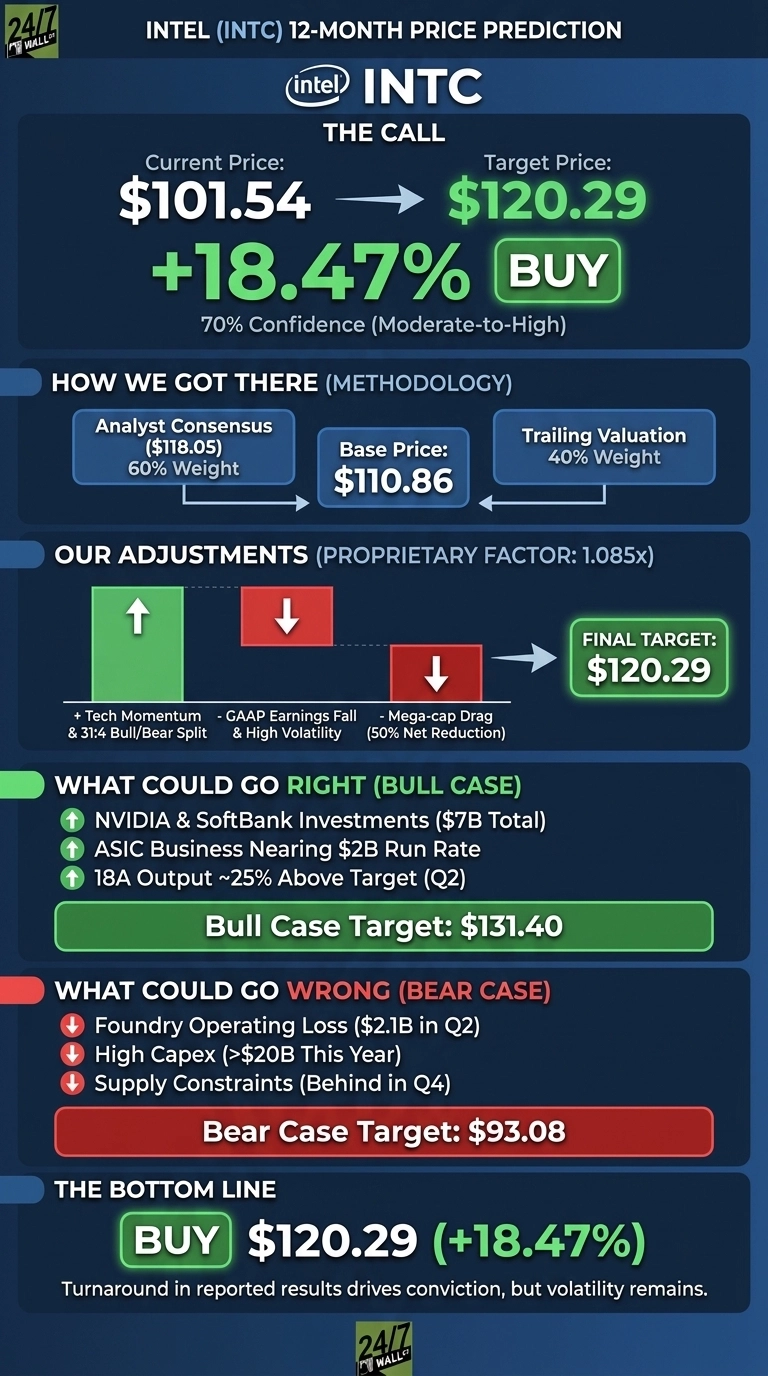
The chipmaker’s turnaround now shows up in reported results, and at today’s price the stock needs that progress to continue. Intel (NASDAQ:INTC | INTC Price Prediction) traded at $101.54 at midday Tuesday.
The 24/7 Wall St. price target sits at $120.29 over the next 12 months. That means 18.47% upside, and we rate the stock a buy with moderate-to-high confidence.
| Metric | Value |
|---|---|
| Current Price | $101.54 |
| Price Target — 24/7 Wall St. | $120.29 |
| Upside/Downside | 18.47% |
| Recommendation | BUY |
| Confidence Level | 70% |
Our conviction comes from accelerating data center demand and a margin improvement that Intel has now reported in its numbers. We stopped short of higher confidence because of the stock’s beta of 2.23, so the path to our target will likely be volatile.

A Huge 2026 Rally Hits an October Pullback
Intel shares are up 175.18% year to date. They have also fallen 12.61% in the past week. The stock sits about 17% below its 52-week high of $142.35 and well above its low of $32.89.
Earnings back up the rally. Q2 revenue rose 25.42% to $16.13 billion, beating the $14.45 billion estimate. Non-GAAP EPS of $0.42 exceeded the $0.2175 consensus. Data Center and AI revenue grew 59%. CEO Lip-Bu Tan called it “our strongest revenue growth in more than fifteen years.”
Why Bulls See $131 Within Reach
Our bull case reaches $131.40. Intel 18A output ran about 25% above target in Q2. Separately, NVIDIA (NASDAQ:NVDA) made a $5 billion equity investment and SoftBank put in $2 billion, and NVIDIA picked Xeon 6 as the host CPU for DGX Rubin NVL8.
The ASIC business is nearing a $2 billion run rate, and management is aiming $4 billion. Consensus 2027 EPS has climbed to $2.0827 from $1.5384 90 days ago. With 32 Hold ratings against 15 Buy or Strong Buy ratings, analyst upgrades could add momentum.

Foundry Losses Could Stall the Turnaround
The bear case lands at $93.08. Intel Foundry lost $2.1 billion in Q2 on external revenue of just $293 million. Capex will exceed $20 billion this year. On supply, CFO David Zinsner warned, “We will be behind in the fourth quarter.”
The $11.03 billion GAAP net loss was driven by a $12.53 billion non-cash charge on CHIPS Act escrowed shares. The foundry loss narrowed by $348 million from the prior quarter.
How Intel Compares to AMD and NVIDIA
AMD (NASDAQ:AMD) is Intel’s direct x86 rival. It trades at 40x forward earnings, compared with 63x for Intel, and its Q2 revenue rose 50.11%. AMD is growing faster at a lower multiple, which tells us Intel’s price already assumes a lot of recovery.
NVIDIA sets the AI compute benchmark and now has a stake in Intel. The stock is valued at 25x forward earnings while growing revenue 105.85%. Against these peers, our target looks reasonable. Further gains depend on Intel lifting its 34.77% gross margin.
| Company | Forward P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Intel | 63x | 25.42% |
| AMD | 40x | 50.11% |
| NVIDIA | 25x | 105.85% |
Intel Earns a Buy Rating Here
Our 24/7 Wall St. price target of $120.29 comes with a buy rating and 70% confidence. What tips the scale is the non-GAAP operating margin, which swung to 17.2% from -3.9%.
The bull case strengthens if Q3 returns the $0.38 EPS guidance and foundry losses keep shrinking. The outlook weakens if 14A customer commitments stall. The turnaround shows up in the numbers, though the stock’s volatility remains high.

Looking further out, here is where our model projects Intel could trade, if growth and market conditions stay on their current path.
| Year | Price Target — 24/7 Wall St. |
|---|---|
| 2026 | $98.70 |
| 2027 | $121.26 |
| 2028 | $139.93 |
| 2029 | $148.83 |
| 2030 | $166.28 |
Intel needs to keep executing its current strategy for these projections to hold. Winning external 14A customers could lift results well above these figures, while ongoing foundry losses could hold the stock back.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.